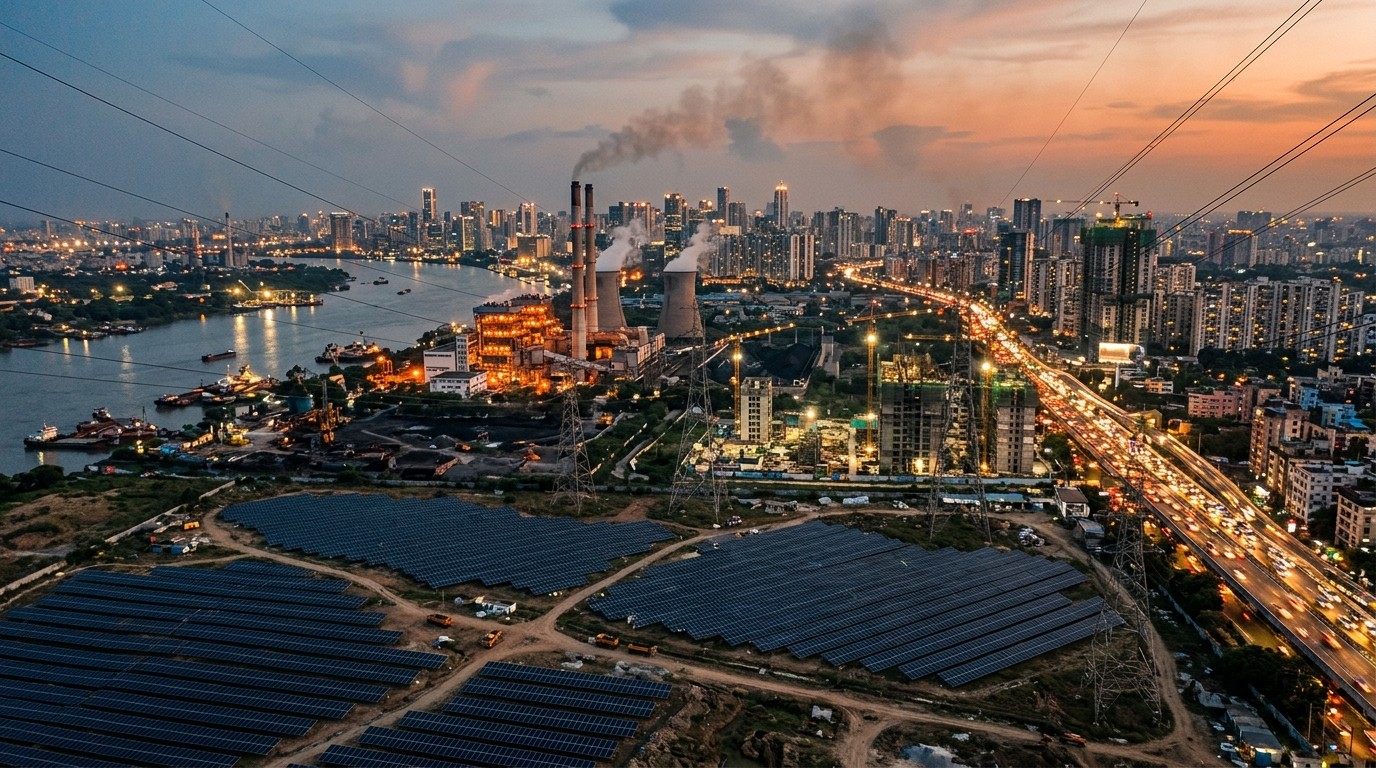

Have you ever tried to picture what it means when someone says world energy use could swell by more than half in a single generation? I have, and the image is not a neat chart. It is millions of first refrigerators, first air conditioners, first factory shifts, and first decent streetlights switching on in places that still ration power today. That is the quiet engine behind the forecast that global energy demand may jump around 60 percent by 2060 as developing nations power up.
Why Energy Demand Is Set To Surge
People in rich countries talk about energy as if the main problem is too much of it. Flip the map and the problem looks different. In parts of West Africa, yearly household electricity use can sit below what a single kitchen appliance burns in a wealthy city. That gap is not a talking point. It is the starting line for the next four decades of fuel and power markets.
Brazil, India, Nigeria, Indonesia, and a long list of peers are not waiting for a perfect grid. They are building whatever they can finance: gas plants, hydro, solar parks, coal units where the coal is cheap, and oil products for transport that still has no realistic substitute. I find that mix uncomfortable if you care about climate targets. I also find it honest. Growth does not pause for a seminar.
Industry analysts have framed the rise as roughly equal to adding another China to world consumption. You do not have to love that comparison to feel its weight. China already reshaped commodities once. A second wave, spread across many countries instead of one, would keep pressure on barrels, cargoes, metals, and grid kit for a very long time.
Development, Not Luxury, Is Driving The Numbers
This is not a story about extra gadgets. It is jobs, rising incomes, urban housing, cold chains for food, and clinics that can keep lights on after sunset. When incomes climb, energy use climbs with them. Air conditioning in hot cities is not vanity. It is productivity. The same goes for freight, cement, steel, and fertilizer.
Energy specialists who work on access keep repeating a blunt line: energy poverty is worse than most people in rich countries can picture. I think they are right. You can debate the fuel mix. You cannot debate the human starting point.
Demand growth is being driven by economic development, rising incomes, and job creation. The scale of energy poverty is far worse than most people in wealthy countries imagine.
– Energy access researchers
There is an awkward twist. While poorer nations fight for basic kilowatt-hours, richer ones are adding a new load of their own. Data centers and artificial intelligence clusters are lifting electricity use in places that already consume a lot. That does not cancel the case for development. It does make climate arithmetic harder, and it makes hypocrisy easier to spot.
An All-Of-The-Above Reality, Not A Fairy Tale
Renewables are no longer a side show. Cheap modules, better inverters, and faster project cycles have changed the math in sun-rich markets. Still, the people who sit closest to the forecasts keep saying the same thing. Growth will be met with a multiplicity of energies. Solar and wind matter. Hydro matters. Gas matters. Oil stays in transport and petrochemicals. Coal may even get a second look where security trumps everything else.
This demand growth is going to be met with a multiplicity of different energies. Renewables will be an important part of it. You are going to see perhaps more coal now, and oil and gas will continue to be part of the demand picture for longer than many people think.
– Veteran energy analysts
That last clause is the one markets should tattoo on a whiteboard. Oil and gas for longer than many people think. Peak demand speeches travel well on stage. They travel less well through a port in South Asia at 2 a.m. when diesel is what keeps the trucks moving.
How Cheap Clean Tech Changed The Map
One country now dominates the factories that stamp out solar gear, batteries, and a lot of the hardware that sits behind a modern renewable plant. That manufacturing wave has slashed costs. Pair low prices with jittery oil and gas markets, and you get a rush of installations in places that used to treat solar as a boutique option.
Several emerging economies have already moved faster, on a relative basis, than the largest rich-world grid. By late last year, a majority of tracked emerging markets across Africa, Asia, and Latin America were pulling a larger share of power from solar than the United States. Names that come up again and again include Brazil, Chile, Morocco, Kenya, Namibia, and a handful of smaller systems that simply have good sun and thin bureaucracies.
Is that a renewable revolution? In generation mix, yes, in some countries. In total energy, including heat and transport, not yet. Electricity is only one slice of the pie. Cooking fuels, industry, aviation, shipping, and road freight still lean on molecules. Anyone who confuses “more solar on the grid” with “fossil fuels are finished” is selling a story, not a balance sheet.
Why Leapfrogging Sounds Nicer Than It Pays
Rich nations like the word leapfrog. The idea is simple. Poor countries should skip the dirty decades and land on a clean grid. Fairness is the moral wrapping. History is the problem. The countries now giving the lecture burned coal, oil, and gas for a century while they got rich. Asking others to skip that ladder without writing a real check is a tough sell, and it should be.
Climate finance was supposed to close the gap. The record is messy. Pledges slip. Loans arrive dressed as grants. Projects stall in paperwork. I have watched this cycle long enough to treat grand announcements with a raised eyebrow. Money that does not show up on time is not money.
Even when hardware is cheap, systems are not. You still need land, transformers, substations, skilled crews, working courts, and a utility that can collect bills. Emerging economies cannot sit on their hands until the next cost curve arrives. People want power this decade, not after another round of conferences.
- Hardware prices fell, but grid upgrades did not fall as fast.
- Intermittent plants need backup, storage, or flexible gas.
- Permitting and land conflicts still kill good projects.
- Currency risk scares long-term lenders.
- Political cycles can flip tariff rules overnight.
None of that means renewables lose. It means they share the stage. If you invest as if the stage has only one actor, you will get surprised.
Oil, Gas, And The Long Tail Of Molecules
Transport is the stubborn piece. Passenger cars can electrify in dense, wealthy cities. Heavy trucks, aviation, and shipping move slower. Petrochemicals keep eating oil even if engines get cleaner. Gas, meanwhile, is the swing fuel that politicians love to criticize and grids love to use when the wind dies.
Price spikes and shipping chokepoints still matter. When a key waterway looks risky, importers shop for cargoes, restart idle plants, or lean on coal. That is not ideology. That is operations. Security of supply is a feature, not a footnote, once you are the minister who has to explain blackouts.
In my view, the market still underprices the option value of existing oil and gas systems. Pipelines, refineries, and LNG docks are already built. Political speeches do not retire them. Utilization does.
Coal’s Unwelcome Comeback In Some Plans
Nobody who cares about air quality wants more coal. Some governments will still burn it because it is local, familiar, and dispatchable. If gas is pricey and hydro is seasonal, coal becomes the ugly insurance policy. Forecasts that quietly lift coal in the near term are not celebrating it. They are admitting constraints.
Investors should separate moral preference from cash flow. A plant that runs because a city cannot risk outages will run, whatever the branding on a summit banner.
What The Mix Could Look Like In Practice
| Source | Role Through Mid-Century | Pressure Point |
| Solar and wind | Fastest growth in power generation | Grids, storage, land |
| Natural gas | Backup, industry, some heating | Price and import risk |
| Oil | Transport and chemicals | Efficiency and substitution |
| Coal | Residual baseload in some markets | Pollution and finance |
| Hydro and nuclear | Firm low-carbon power where feasible | Build times and politics |
Tables flatten a messy world, but they help. Notice what is missing: a single winner. That absence is the point.
Climate Goals Meet Arithmetic
If demand rises 60 percent and fossils remain a large slice, carbon math gets brutal. Efficiency helps. Better grids help. Methane cuts help. None of that erases a larger energy system serving more people who finally live closer to a decent standard.
Perhaps the most interesting tension is political, not technical. Emerging economies argue they should not carry the full burden of a problem they did not create at scale. Wealthy capitals reply that physics does not care who emitted first. Both statements can be true at once. Policy that pretends only one is true will fail in the real world.
I do not think “incredibly hard” is too strong a phrase for aligned climate targets under this demand path. Hard is not the same as hopeless. It does mean timelines that assume a clean sweep of fossils look decorative.
Where Capital Is Likely To Flow
Money will chase three piles. First, generation that can be built fast: utility solar, some wind, and gas peakers. Second, networks: wires, substations, ports, and storage. Third, fuels that keep industry and freight alive while the first two scale. Ignore the third pile and you will misread listed energy firms for years.
- Map which countries are adding people, factories, and cooling load at the same time.
- Check whether their grids can absorb more variable power without chronic outages.
- Watch who can actually finance baseload and backup, not just ribbon-cuttings.
- Follow shipping routes and chokepoints that still set gas and oil prices.
- Separate announced climate finance from cash that has cleared.
That list is boring on purpose. Boring is how you stay solvent when narratives get loud.
Energy Poverty Is Not An Abstract Chart
It is easy to sit in a climate-controlled office and talk about demand destruction. It is harder to tell a family that the plant that would have powered a welding shop should wait another decade for a prettier technology. Development agencies keep circling this point because the public in rich countries still underestimates it.
When someone notes that an average household in a low-income country can use less electricity in a year than a refrigerator uses in a high-income kitchen, pay attention. That sentence should rearrange priorities. Access first. Cleaner where possible. Perfect later, if later ever comes.
The Rich-World Demand Surprise
For years the script said rich countries were done growing energy use. Then computing loads arrived with a swagger. Training and running large models drinks power. So do the buildings that house them and the cooling they require. That surge does not match the moral lecture often aimed at Lagos or Jakarta.
I am not anti-technology. I am allergic to one-way sermons. If advanced economies add load for digital infrastructure, they should own that fact when they talk about global carbon space.
Market Signals Investors Keep Missing
Commodity cycles love extremes. One year fossils are dead money. The next year traders cannot find enough diesel. The through-line is underinvestment in supply that the world still uses, plus overcrowding in themes that photograph well.
Watch utilization rates, not slogans. A solar park with a weak grid is a stranded press release. A midstream asset that moves molecules into a growing city can look dull and still print cash. Risk management here is less about predicting a single fuel winner and more about owning optionality across the stack.
Simple demand lens:
  Rising incomes
  + Urban cooling
  + Industry and freight
  + Digital load in rich grids
  = Higher total energy use for longer
Ugly formula. Useful formula.
Policy Friction That Slows Everything
Permits take years. Local opposition can stall a transmission line that would unlock a whole renewable zone. Export credit rules can block coal even when a government sees no near-term substitute. Sanctions and shipping insurance can reroute barrels overnight. This is the sludge layer under every tidy scenario.
Good analysis treats sludge as a feature of the system. If your model assumes frictionless buildout, your model is a brochure.
What “Another China” Would Mean For Prices
A second China-sized gulp of energy would not copy the first one. The first one concentrated demand in one industrial machine with state-directed coal and later a renewable factory empire. The next wave is scattered. That scatter can be kinder to supply chains in some years and nastier in others, because coordination is weaker and politics more fragmented.
Metals for grids and batteries would still feel it. Tanker markets would still feel it. Equipment makers would still feel it. Soft prices in one cycle should not be mistaken for a permanent ceiling.
A Ground-Level Way To Read The Next Decade
Forget the end-state argument for a minute. Ask narrower questions. Which cities are adding middle-class housing the fastest? Which industrial corridors are getting new ports? Which utilities can collect revenue without collapsing? Those answers tell you more about barrels and terawatt-hours than a slogan about net zero dates.
In my experience, the investors who stay calm are the ones who accept mixed systems. They do not need the world to be only green or only brown. They need the world to be electrified enough to grow, and supplied enough to avoid panic.
The Uncomfortable Middle Path
So where does that leave a reader who wants both development and a livable climate? In the middle, unfortunately. More renewables, faster grids, serious methane work, less waste, and a frank admission that oil and gas are not extras in the short and medium run. Pretending otherwise is how countries get blackouts and how portfolios get whiplash.
Emerging economies will keep saying they cannot wait. They are not wrong. Technology costs help them more than they did ten years ago. Help is not the same as a finished transition. Anyone selling a finished transition on a 2030 poster should be asked who pays for backup at 9 p.m. in April.
Emerging economies cannot wait on the next wave of cost cuts before they grow their energy systems. People need power now.
Practical Takeaways Without The Hype
If you follow markets, treat the 60 percent figure as a direction, not a sacred integer. Forecasts move. Direction matters more. Demand grows where people get richer. Supply stays mixed. Climate targets get harder. Capital that can live with that mess will be less shocked than capital that needs a single story.
- Do not equate solar headlines with the end of oil demand.
- Do not ignore coal where energy security dominates politics.
- Do not assume climate finance will arrive on schedule.
- Do not forget rich-world digital load when lecturing poorer grids.
- Do not build a thesis that dies if one fuel stays resilient.
Those rules will not make you popular at a dinner where everyone already agrees. They might keep you closer to how systems actually run.
A Last Look At The Human Scale
Strip away the percentages and you are left with a simple contest. Billions of people want the services energy makes possible. The atmosphere has a budget. Industry has inertia. Politics has a short attention span. Those four facts can share a room. They cannot all get everything they want on the same timetable.
I keep coming back to that refrigerator comparison because it is rude and clear. Until that gap narrows, lectures about demand restraint will sound like a locked door. The next thirty-plus years of energy markets will be written in that gap: more power, more fuels, more wires, more arguments, and less purity than the brochures promised.
If the 60 percent path even comes close, the world will not choose between renewables and fossils in a tidy vote. It will use both, argue about both, and try to keep the lights on while it argues. That is not a thrilling slogan. It is a workable reading of the road ahead.