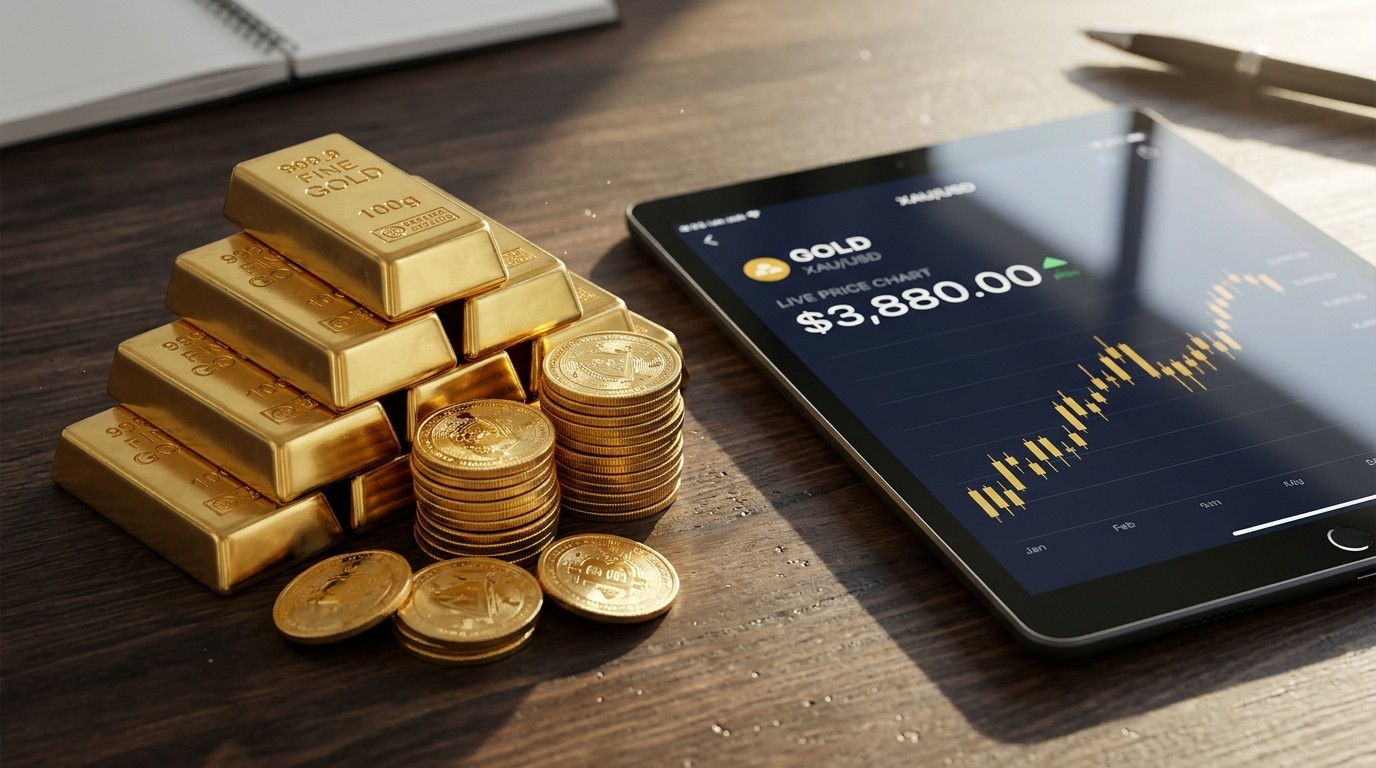

I checked the numbers this morning and felt that familiar mix of curiosity and mild relief. Gold’s spot price sat at $3,880.30 per ounce around 9 a.m. Eastern, a touch softer than yesterday’s $3,890.79 reading at the same hour. Nothing dramatic, yet the quiet dip still makes you pause. In a world that keeps throwing curveballs, this metal continues to act like the quiet friend who never panics.
Understanding Today’s Gold Price And Why It Still Matters
Gold has this reputation as the ultimate safe-haven asset, and for good reason. When economic headlines turn messy or political noise grows louder, money often drifts toward the yellow metal. It does not pay a dividend and it will not compound like a solid stock portfolio, yet it has held purchasing power across centuries. That simple fact keeps drawing people back.
I’ve watched friends treat gold as both an emergency cushion and a long-term portfolio balancer. Some buy a few coins when markets feel frothy. Others move larger sums into specialized accounts. The approaches differ, but the underlying goal stays the same: protection against the unknown.
Today’s slight pullback does not change the bigger picture. Inflation still lurks in conversations, and global uncertainty refuses to take a holiday. Gold tends to shine brightest when everything else feels shaky. That is why many of us keep at least a modest allocation, even if the day-to-day price action looks sleepy.
Buying Physical Gold The Straightforward Way
Holding actual metal in your hands carries a certain satisfaction that numbers on a screen simply cannot match. Bars, ingots, and coins remain the most direct route. You can find them through established online dealers or even at large retailers that many of us already visit for everyday needs.
APMEX has been around since 2000 and offers a wide range of products along with educational material that helps newcomers avoid rookie mistakes. JM Bullion entered the space a bit later yet built a solid reputation for competitive pricing and reliable service. Both buy back metal when you eventually decide to sell, which removes one common headache.
Shipping often turns free once your order clears a modest threshold, usually around two hundred dollars. That detail matters more than people admit. Nobody wants to watch a meaningful portion of a small purchase disappear into delivery fees.
Coins bring an extra layer of interest. Historic designs or limited mintages sometimes carry a premium beyond pure metal value. I’ve spoken with collectors who treat certain pieces almost like art. For pure investment purposes, though, plain bullion usually makes more sense because the spread between buy and sell stays tighter.
Storage becomes the real conversation once the package arrives. A home safe works for smaller amounts, yet larger holdings often push people toward bank boxes or private vaults. Insurance costs and peace of mind need careful weighing. Liquidating physical metal also takes an extra step compared with clicking a sell button on shares. You locate a buyer, arrange the hand-off, and wait for funds. The process is rarely complicated, yet it is never instant.
- Choose reputable dealers with transparent pricing and clear return policies
- Compare premiums over spot across several products before committing
- Plan storage and insurance before the metal ever leaves the seller
- Keep detailed records for tax purposes when you eventually sell
In my experience the biggest mistake newcomers make is buying first and thinking about security later. That order of operations rarely ends well.
Opening A Gold IRA For Tax Advantages And Hands-Off Storage
Physical ownership is not the only path. A gold IRA lets you hold approved bullion inside a retirement account. The custodian handles storage in an IRS-approved facility, and you gain the familiar tax treatment of traditional or Roth structures. Contributions may be deductible or growth may stay tax-free, depending on the account type you choose.
Fees exist, of course. Setup charges, annual administration, and storage costs can add up. Flat-fee structures tend to favor larger balances, while smaller accounts sometimes feel the drag more sharply. Several providers advertise first-year fee waivers once the account crosses a certain size, often fifty thousand dollars. That incentive can help offset early costs.
Minimum purchase requirements usually start around ten thousand dollars. Account balance floors vary. Some firms want twenty-five thousand before they feel comfortable; others set the bar lower. Transferring an existing IRA or 401(k) is possible, though the paperwork and timeline can stretch a few weeks.
I’ve found the buyback guarantees offered by certain companies particularly reassuring. Knowing you can exit at a competitive rate without extra friction removes one mental barrier. Still, gold IRAs do not generate income the way dividend stocks or bonds do. The only growth comes from a rising metal price. That limitation needs honest acknowledgment before money moves.
A gold IRA removes the daily storage worry yet introduces ongoing fees that pure physical ownership avoids. Balance those trade-offs carefully against your own time horizon and risk comfort.
Researching fee schedules side by side remains essential. Some firms publish clear numbers; others bury details in fine print. Transparency itself becomes a useful filter when choosing a partner.
Investing Through Gold ETFs For Simplicity And Liquidity
Exchange-traded funds tracking gold offer the easiest on-ramp for most people. You buy shares through any standard brokerage account the same way you would purchase stock. Some funds hold physical bars in secure vaults. Others track mining companies whose fortunes rise and fall with the metal price yet also depend on operational efficiency and management decisions.
Liquidity stands out as the clearest advantage. Selling takes seconds during market hours. No phone calls to dealers, no shipping arrangements, no storage anxiety. Expense ratios stay modest on the largest funds, often well under half a percent annually.
Brokerages with zero-commission stock and ETF trades make the entry cost almost invisible. Platforms that also provide solid research tools and educational content help newer investors understand exactly what they own. Fractional shares further lower the barrier; you can start with whatever amount fits your budget rather than waiting to accumulate a full ounce.
Mining-focused ETFs introduce extra volatility because company-specific risks layer on top of pure metal movement. Pure bullion funds stay closer to the spot price itself. Knowing which flavor you prefer prevents surprises later.
Perhaps the most interesting aspect is how cleanly these funds fit inside existing portfolios. Rebalancing becomes a simple matter of adjusting share counts rather than rearranging physical inventory. For anyone already comfortable with stocks and mutual funds, gold ETFs feel almost native.
Comparing The Three Main Paths Side By Side
Each route carries distinct strengths and friction points. Physical metal delivers tangible ownership and no ongoing management fees after purchase, yet storage and liquidity require extra effort. A gold IRA wraps the metal in retirement tax treatment and professional vaulting, but annual costs continue year after year. ETFs maximize convenience and trading speed while introducing a small expense ratio and removing the satisfaction of holding actual bars.
| Approach | Liquidity | Ongoing Costs | Tax Treatment | Best Suited For |
| Physical Gold | Moderate | Storage and insurance only | Capital gains on sale | Those who value tangible assets |
| Gold IRA | Lower | Setup plus annual fees | Retirement account rules | Long-term retirement savers |
| Gold ETF | High | Expense ratio | Taxable brokerage or IRA | Investors wanting simplicity |
No single choice wins for every person. Someone with a large taxable account and a strong preference for physical assets may lean toward bars and coins. Another investor focused on retirement growth might prefer the IRA structure. Busy professionals often default to ETFs simply because life already feels complicated enough.
Practical Considerations Before You Commit Any Capital
Position size deserves more attention than most people give it. Gold rarely belongs as the core of a portfolio. Many experienced investors keep allocations between five and fifteen percent, adjusting according to personal risk tolerance and existing exposure to other inflation-sensitive assets. Over-concentration can leave you underperforming during strong equity bull markets.
Premiums over the spot price vary by product and payment method. Wire transfers or checks sometimes unlock better rates than credit cards. Understanding those differences before clicking “buy” prevents quiet regret later.
Counterfeit risk remains low when dealing with established names, yet it never reaches zero in the private secondary market. Stick with recognized dealers and products that carry clear hallmarks or assay certificates. That simple habit eliminates most problems before they start.
Taxes arrive eventually. Physical sales outside retirement accounts trigger capital gains reporting. IRA distributions follow ordinary retirement rules. Keeping clean records from day one makes April far less stressful.
I’ve found that writing down the original purpose of the purchase helps later decision-making. Was this money meant as long-term insurance, a tactical hedge, or something closer to a collectible hobby? Clarity at the start reduces emotional selling when prices swing.
Common Questions New Gold Investors Keep Asking
How should a complete beginner start? Smaller coin purchases or a modest ETF position often feel less intimidating than a large IRA transfer. Once comfort grows, scaling up becomes straightforward.
What are the clearest advantages? Diversification, historical inflation resistance, and a tendency to move differently from stocks during stress periods. Those traits explain the enduring appeal.
What drawbacks deserve attention? Storage logistics for physical metal, ongoing fees inside IRAs, and the absence of yield across all three methods. Gold sits quietly; it does not compound on its own.
Is now a good moment? Nobody knows the exact bottom or top. Dollar-cost averaging across several months removes the pressure of perfect timing for most people. Today’s price simply becomes one data point among many.
Building A Personal Approach That Actually Fits Your Life
Some readers will finish this piece and order a few ounces of bullion this week. Others will open an ETF position inside an existing brokerage account before the market closes. A smaller group may begin the paperwork for a specialized retirement account. All three reactions can be reasonable depending on individual circumstances.
The quiet power of gold lies in its simplicity. It does not require brilliant forecasting or constant monitoring. It simply exists as a store of value that has survived empires, currencies, and countless market cycles. That endurance continues to attract capital whenever uncertainty rises.
Today’s price of $3,880.30 per ounce is neither a scream to buy nor a signal to avoid. It is merely the current clearing level between buyers and sellers. What matters more is the role you decide this metal should play inside your own financial picture.
Take the time to match the method to your temperament. If you enjoy the weight of metal in a safe, physical ownership may feel right. If you prefer set-and-forget convenience, an ETF or IRA structure will likely serve better. Either way, the decision rests with you rather than with any single headline or daily quote.
Markets will keep moving. Headlines will keep shifting. Gold will keep doing what it has always done: sitting quietly as one of the few assets that needs no promise of future cash flow to retain relevance. For many of us, that quiet reliability remains worth a measured place in the portfolio.
Whatever path you choose, move deliberately. Compare costs, understand the practical details, and keep the allocation sized to your overall plan. The metal itself has already proven its staying power across far longer stretches of history than any of us will personally witness. The only remaining question is how thoughtfully we decide to include it.
In the end the best approach is the one you can maintain without second-guessing every price tick. Consistency and clear purpose tend to matter more than catching the perfect entry. Gold rewards patience more reliably than clever timing, and that lesson has held true for generations of investors who simply wanted a reliable store of value when the rest of the financial world felt anything but reliable.