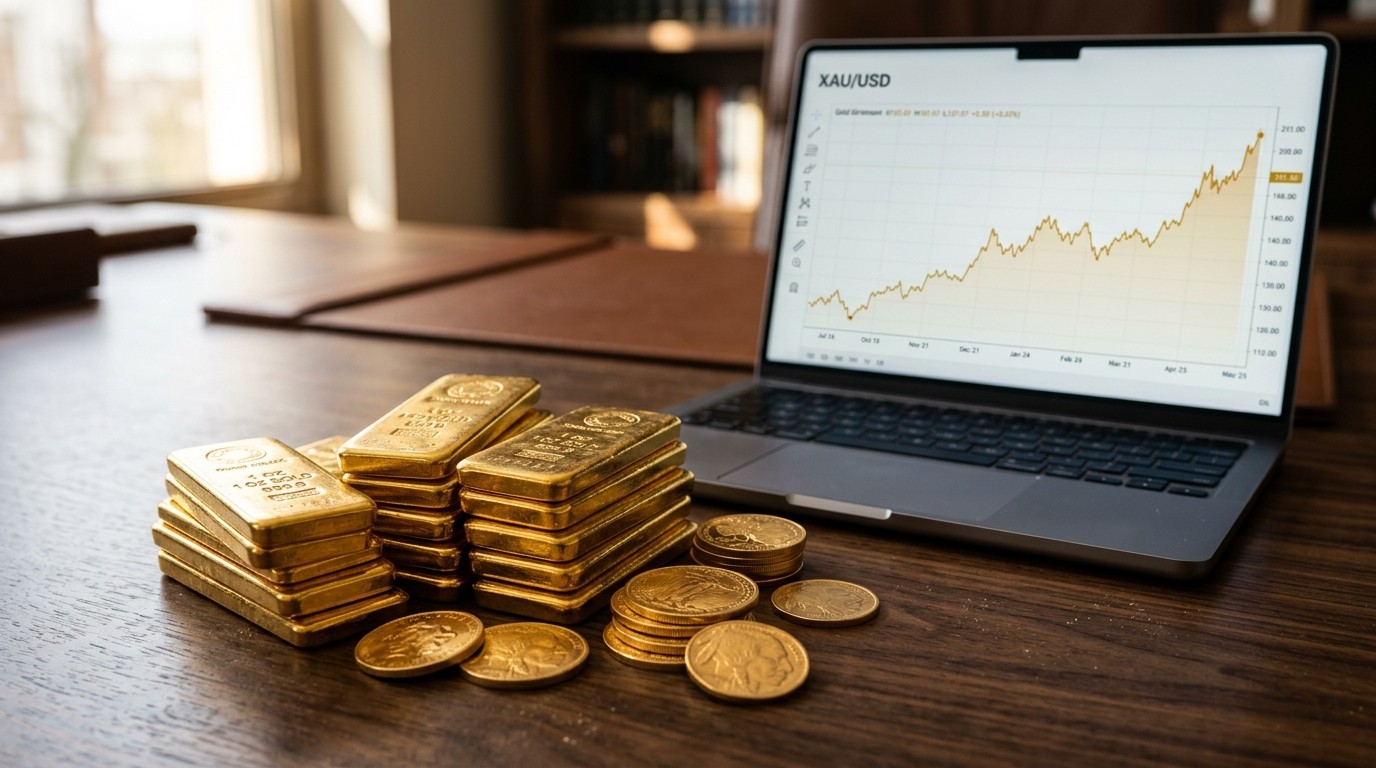

Have you ever stared at a gold quote on your phone and thought, wait, is this the moment I finally buy, or am I just late to a party that started years ago? This morning the metal was changing hands near four thousand three hundred sixty-four dollars an ounce, a hair softer than the prior session at the same hour. That tiny dip is not the story. The story is what people do after they see the number.
What The Gold Price Today Actually Tells You
A spot quote is a snapshot, not a promise. It reflects the last agreed price for immediate delivery of a standard bar in a major trading hub. It does not include the premium you will pay a dealer, the spread when you sell, storage, insurance, or the awkward pause when you realize a bar does not live in a brokerage app. I have watched friends treat that number like a coupon code. It is not.
Gold still behaves like a safe haven when politics get loud and inflation feels sticky. It does not pay a dividend. It does not compound by itself. It sits there looking expensive and occasionally looking brilliant. That tension is the whole game.
Gold is less an investment that works for you and more an asset that refuses to work for anyone else when systems wobble.
On September 18, 2026 the print sat at $4,364.46 per ounce around 9:00 a.m. Eastern, versus $4,364.63 a day earlier. You could miss that move if you blinked. You should not miss the structure underneath it. Demand for metal as insurance has stayed stubborn. Jewelry demand is another animal. Central banks have been quiet buyers for years. Retail buyers show up in waves after headlines.
Why A Tiny Overnight Change Still Matters
Small moves teach discipline. If you only buy after a two-hundred-dollar jump, you are training yourself to chase. If you only sell after a two-hundred-dollar drop, you are training yourself to panic. I prefer a boring rule: decide the role gold plays in the portfolio first, then ignore most of the daily noise.
Perhaps the most interesting aspect is how people confuse spot price with transaction price. Spot is wholesale-ish. Your invoice is retail-ish. The gap is the premium, and premiums swell when everyone wants the same coin at the same time. That is when “gold is up” and “your gold is more expensive to acquire” happen together. Annoying? Yes. Predictable? Also yes.
Three Practical Ways To Own Gold Without Getting Cute
You do not need a secret strategy. You need a method that matches how you live. Some people want a bar they can hold. Some want tax sheltering and a vault they never visit. Some want a ticker they can tap on a phone during lunch. All three can work. Mixing them without a plan usually does not.
- Buy physical bullion or coins and accept storage as part of the job.
- Use a precious-metals retirement account with an approved custodian and depository.
- Buy a fund that tracks gold or gold miners through a regular brokerage account.
None of these is morally superior. Physical metal is tactile and slow to sell. A specialized retirement wrapper is tidy and fee-heavy. A fund is liquid and one step removed from the bar itself. Pick the friction you can live with.
Buying Physical Gold Without Turning Your Closet Into A Vault
Bars and high-purity ingots are the straightforward route. Coins add design, history, and sometimes a collector premium that has nothing to do with the melt value. Online bullion specialists have been doing this for decades. Big-box retailers have wandered into the category too, which still feels slightly surreal the first time you see a bar next to household goods.
Before you click buy, answer two unglamorous questions. Where will this live? Who will buy it back without treating you like a tourist? If you cannot answer both, pause. A safe at home is not a plan if everyone in the house knows the combination. A bank box has hours and paperwork. A private vault has fees. Choose one on purpose.
Shipping thresholds matter more than people admit. Plenty of dealers waive freight above a modest order size. Payment method can change the quote. Card convenience is nice until the premium jumps. Bank transfer is slower and often cheaper. Cancelled orders can carry penalties. Read that part twice. I have seen otherwise careful buyers skip the cancellation line and then get loud about it on a forum. The contract was sitting there the whole time.
- Know the purity and the exact product, not just “some gold.”
- Compare the all-in price, not only the advertised ounce rate.
- Confirm buyback policies before you need them.
- Photograph serial numbers and keep invoices offline as well as online.
Liquidity is the hidden tax. Stocks become cash in a trading day. A bar becomes cash after you find a counterparty, ship or carry the metal, wait for assay if they insist, and accept their bid. That is not a reason to avoid physical gold. It is a reason not to treat it like an emergency fund you will tap on Tuesday afternoon.
Opening A Gold Retirement Account When You Want Less Hardware
A metals-focused individual retirement account lets you hold eligible bullion without storing it under the floorboards. A custodian handles the paperwork. A depository holds the bars. You get the usual tax wrapper benefits, depending on account type. You also get a stack of fees that do not exist in a plain stock fund.
Setup charges, annual admin, storage, and sometimes insurance show up whether gold rips higher or sits still. Minimum purchases often start around ten thousand dollars. Some firms want a higher ongoing balance. Flat fees punish small accounts. That is not a conspiracy. It is arithmetic.
In my experience, the brochure is always prettier than the fee schedule. Look for firms that publish numbers in plain language. Ask what happens in year two when the “we will cover the first year” offer expires. Ask how long a transfer from an existing retirement account actually takes. Three weeks is a long time if markets are moving and you are staring at a half-finished rollover.
| Approach | Typical Friction | Who It Fits |
| Physical bullion | Storage, insurance, slower sale | People who want metal they can inspect |
| Metals IRA | Fees, minimums, transfer delays | Retirement money that should stay sheltered |
| Gold-tracking fund | Tracking error, no coins in hand | Anyone who wants speed and small tickets |
Buyback language deserves a skeptical read. “Best possible rate” is marketing until you see how they define best. Flat storage can be friendlier than percentage storage once the account grows. The reverse is true when the balance is modest. Match the fee shape to the size you actually intend to fund, not the size you might fund after a bonus that has not landed.
Using Funds When You Want Gold Exposure Without A Scale
Exchange-traded products that hold bullion in vaults give you price movement with a ticker symbol. Mining-company funds give you price movement plus management risk, labor issues, and the occasional pleasant surprise when a miner runs tighter than peers. Those are not the same trade. Say that out loud before you buy the second one thinking it is the first.
Most full-service brokerages will let you buy these the way you buy anything else. Commission-free stock and fund trades are common now. That is helpful. It does not make gold cheap if you overtrade it. The metal already refuses to pay you a coupon. Adding a hobbyist trading habit on top is how people turn a hedge into a second job.
I like funds for the portion of gold that needs to be adjustable. Rebalancing is cleaner. Required minimum distributions from a conventional retirement account are simpler when the asset is a share, not a minted coin. The tradeoff is obvious. You do not hold the metal. You hold a claim packaged by a sponsor, watched by a custodian, and priced all day.
If you need the comfort of a physical object, a fund will always feel like a substitute. If you need flexibility, a bar will always feel like furniture.
Beginners, Sizing, And The Temptation To Go All In
How should a beginner start? With an amount that will not wreck sleep. Small coins or fractional bars teach the process. A first fund purchase teaches the quote, the spread, and the tax lot. A first metals retirement transfer teaches patience. Starting with a huge allocation because a chart looks vertical is how people learn the hard lesson about timing.
Portfolio construction talk can get preachy. Still, gold as a slice rather than a personality tends to age better. Ten percent is a number people throw around. Five percent can be enough if the rest of the book is already diversified. Twenty percent can make sense for someone who distrusts paper assets after a scare. There is no sacred percentage. There is only the percentage you will not abandon at the worst print of the year.
What are the genuine advantages? Diversification that does not move in lockstep with earnings seasons. A hedge that has a long cultural memory. A store of value that does not rely on a single government’s promise. What are the genuine drawbacks? Storage if you go physical. Fees if you go the specialized account route. Opportunity cost if equities keep compounding while your metal just sits there looking pretty.
Premiums, Spreads, And The Quiet Math Dealers Hope You Skip
Two products can both be “an ounce of gold” and cost different amounts. Popular coins carry extra demand. Odd-weight bars can be cheaper per ounce and harder to resell quickly. Proof finishes look lovely and often fail to repay the extra you paid when it is time to exit. I have a soft spot for simple, widely recognized products. Boring metal is easier to price.
Spreads widen when headlines scream. That is the market charging you for urgency. If you can wait a week, you often get a calmer bid and offer. If you cannot wait a week, you were using gold as a checking account, and that was the original mistake.
Rough all-in check before you click:
  Spot
  + product premium
  + payment surcharge
  + shipping or vault intake
  + sales tax where it applies
  = what you actually paid per ounce
Do that napkin math every time. It keeps you honest when a product page uses a giant font for the spot-linked number and a tiny font for everything else.
Storage, Insurance, And The Unromantic Side Of Ownership
Home storage is simple until it is not. Fires, theft, family disputes, and “I forgot which box” are not theoretical. A quality safe bolted down is better than a sock drawer. It is still a concentration of value in a residential address. Insurance riders exist. Read the sublimits. Jewelry coverage and bullion coverage are not automatically the same thing.
Allocated storage at a professional depository means specific bars assigned to you. Pooled storage means a claim on a pile. Allocated usually costs more and sleeps better. Ask whether your holding is segregated. Ask who audits the vault. Ask what happens if the depository changes owners. These questions sound tedious because they are. Tedious is how you avoid becoming a cautionary tale.
Taxes, Records, And Selling Without Making A Mess
Tax treatment depends on the wrapper and the jurisdiction. Collectibles rules can apply to physical metal in taxable accounts. Retirement accounts defer or shelter according to their type, with distribution rules that do not care how pretty the coin is. I am not your tax professional. I am the person telling you to keep every invoice like it is a passport.
When you sell physical metal, expect identity checks on larger tickets and a bid that is not the mid-market number you saw on a chart. When you sell a fund, expect a normal brokerage confirmation. When you take a distribution from a metals retirement account, expect process. Process is not optional. Plan the calendar, not just the price.
How Headlines Push People Into Bad Timing
Gold attracts attention when something else looks broken. Currency worries. Election noise. Banking stress. That is rational as a theme and dangerous as a trigger. Buying only when the comment section is on fire means buying when premiums are fat and patience is thin.
A calmer approach is a standing allocation with occasional adds. Dollar-cost averaging into funds is easy. Averaging into physical metal is lumpier because shipping and premiums punish tiny orders. That is fine. Use funds for the drip. Use physical for the core you intend to leave alone.
Rhetorical question time. If gold dropped three percent next month, would you feel smarter or dumber for buying today? If your answer depends entirely on that three percent, the position is too large or the thesis is too fragile. The metal is supposed to be ballast. Ballast that gives you vertigo is just more volatility with extra steps.
Miners Versus Metal, And Why People Mix Them Up
Mining shares can amplify gold’s move. They can also amplify a bad quarter, a political permit delay, or a cost spike in fuel and labor. Some investors like that torque. Others thought they bought “gold” and then discovered they bought a business. Read the holdings. If the product owns companies, you own operating risk. If it owns bars, you own metal risk and sponsor risk. Different animals.
I find miners useful as a satellite, not as a substitute for the core hedge. When they work, they work loudly. When they fail, they fail while gold itself is still doing the quiet job you wanted in the first place. That mismatch bothers me more than it bothers some traders. Fair enough. Know which camp you are in.
A Realistic Checklist Before You Spend A Dollar
- Write the purpose in one sentence. Hedge, speculation, or collectible interest.
- Pick the wrapper that matches that sentence.
- Cap the allocation so a dull decade in gold will not wreck the plan.
- Compare all-in costs across at least two sellers or sponsors.
- Document storage or custody in writing.
- Decide in advance what would make you sell, other than a scary headline.
That last item saves people from themselves. “I will sell if I need a down payment” is a plan. “I will sell if a stranger on a video sounds confident” is not a plan. You already knew that. Writing it down makes it harder to pretend otherwise at 11 p.m.
What Today’s Quote Should Not Do To You
A print near $4,364 should not make you feel late, brilliant, or doomed. It is one observation in a long series. The metal has been expensive by old standards for a while. It has also been doing the job many owners hired it to do: sit outside the usual stack of corporate earnings and policy meetings.
If you already own gold, today is a reminder to check premiums and custody, not a command to reshuffle everything. If you do not own any, today is as good as any other day to size a starter position you can explain to a skeptical friend. If you cannot explain it, wait. Confusion is expensive in this corner of the market.
I keep coming back to a simple bias. Own some if uncertainty is a feature of your life, which it is. Do not own so much that you start cheering for chaos. That emotional slip is common and a little ugly. Gold is insurance. People who fall in love with their insurance policy start hoping for accidents. Skip that part.
Putting The Pieces Together Without A Sales Pitch
Physical metal is for the owner who accepts keys, receipts, and slower exits. A metals retirement account is for tax-advantaged money that should stay in a vault with a paper trail. A fund is for flexibility and small increments. You can use more than one. You should not use all three just because a checklist on the internet made it look complete.
The price this morning was almost unchanged. That is useful. It gives you a chance to think while the tape is quiet. Tomorrow the number will be different. Your storage plan, your fee schedule, and your reason for owning the metal should not have to reinvent themselves every time the quote blinks.
Buy slowly if you are new. Read the cancellation terms. Photograph the bars. Know who takes them back. If that sounds less romantic than a gleaming stack on a social feed, good. Romance is a terrible custody policy. Clear process is how gold stays a hedge instead of becoming a story you tell about the time you overpaid and could not sell.
And if you only remember one thing from this whole walk-through, make it this. The spot price is the easy part. Living with the metal, the wrapper, and the exit is the work. Do the work first. Then the number on September 18, 2026 is just a number, which is exactly what it should be.