

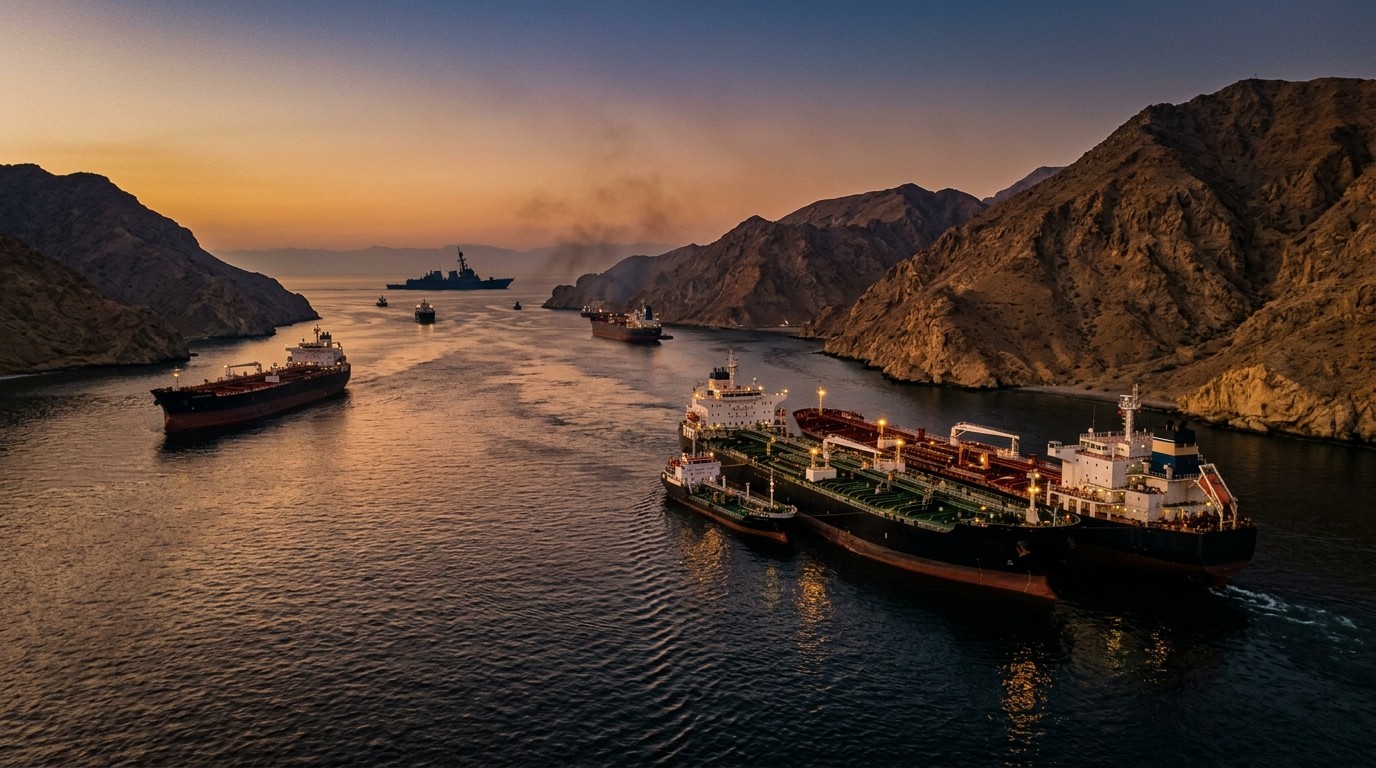

Here is the part that still feels slightly unreal. Crude moving through the Strait of Hormuz is back around the volumes traders treated as normal before the latest round of fighting. Fuel is not. That split is the whole story, and it is the reason diesel has become the market’s loudest headache.
Why Crude Looks Calm While The Fuel Market Does Not
I have watched energy markets long enough to know that a headline about “normalized flows” can hide a mess underneath. The latest tanker-tracking snapshot shows a seven-day average of about 13.5 million barrels a day of crude crossing Hormuz. That matches the prewar baseline. On paper, that sounds like the choke point is working again.
Look one layer down and the picture changes. Refined product shipments through the same waterway are running near 677,000 barrels a day. Before the war, that figure sat closer to 3.6 million. Crude can find workarounds. Gasoline, diesel, and jet fuel have a harder time doing the same thing.
That is why the global conversation has shifted from “is oil getting out?” to “why is middle distillate still missing?” In my view, that second question matters more for households, truckers, and factories than the first one.
The Uneven Rebound In Gulf Exports
Crude leaving the broader Middle East region, counting both the Persian Gulf and the Red Sea, has even overshot older norms. Recent seven-day averages near 19.5 million barrels a day sit above a prewar baseline around 17 million. Pipelines, escorts, and rerouting did more work than many people expected.
Refined barrels did not get the same rescue. Product tankers are fewer, more specialized, and more exposed when the security map turns ugly. A crude cargo can be shuffled onto another hull off Oman or the United Arab Emirates. A diesel cargo is less flexible once a refinery slate is disrupted or a loading window is missed.
The crude market has largely normalized even as refined product supplies remain constrained.
– Global commodities strategist
That sentence is doing a lot of work. Normalization in crude is not the same as comfort in fuel. Traders can hedge a barrel of sour crude more easily than they can replace missing winter diesel.
How The Shuttle System Kept Crude Moving
Security in the strait is still not normal. Attacks on tankers have continued, and some have been lethal. The market adapted anyway. In August, more than 70 percent of the crude that crossed Hormuz changed ships off the coast of the United Arab Emirates or Oman.
Think of it as a relay. Smaller or more protected shuttle tankers take the oil through the tightest stretch. Then the cargo is loaded onto another vessel that completes the run toward Asia. The arrangement lowers the time a long-haul ship spends in the most dangerous water.
It also depends on a heavy military escort. That is expensive. It is also a political commitment, not a free market feature. I’ve found that markets often treat a workaround as permanent the moment prices ease. This one is not permanent. It lasts as long as the escort holds and as long as crews are willing to keep doing the transfer dance.
- Shuttle tankers move crude through the highest-risk stretch
- Ship-to-ship transfers happen off safer Gulf of Oman waters
- Long-haul vessels then complete the voyage toward Asian buyers
- Military protection is the glue holding the system together
Gulf producers do not love this patchwork. An open strait is simpler, cheaper, and easier to insure. A relay system is a wartime improvisation wearing a peacetime costume.
Pipelines Did The Quiet Heavy Lifting
Pipelines deserve more credit than they usually get in these conversations. About 40 percent of Gulf crude is now bypassing Hormuz through Saudi and Emirati lines, compared with roughly 17 percent before the war. That is a structural shift, not a rounding error.
It is also not invincible. A drone strike launched from Iraq damaged the Saudi East-West line earlier this month and forced a temporary shutdown. Loadings later picked up again at the Red Sea port of Yanbu, a sign the line was returning to service.
During the outage, crude did not fall off a cliff. Why? Because barrels could swing back toward Hormuz and use the shuttle system. That flexibility is useful. It is also a reminder that both routes now depend on security conditions that can change in a night.
| Flow type | Recent picture | Prewar comparison |
| Crude through Hormuz | About 13.5 million bpd | Near baseline |
| Regional crude including Red Sea | About 19.5 million bpd | Above roughly 17 million bpd |
| Refined products through Hormuz | About 677,000 bpd | Far below 3.6 million bpd |
| Gulf crude bypassing Hormuz by pipeline | About 40 percent | About 17 percent |
Iran’s Own Exports Have Collapsed
While other Gulf barrels found a path, Iranian crude has cratered under a naval blockade and tighter financial pressure. The strategy is blunt: squeeze the main revenue stream and force a settlement. Officials have argued that remaining deliveries to China are winding down and that the trading window is closing fast.
Whether that pressure changes political terms is another matter. Some voices in Washington want to let the blockade work and wait. Others point out that there is still no hard proof the squeeze will reset core demands. That gap between economic pain and diplomatic movement is where markets stay nervous.
Tehran has claimed control of the strait throughout the conflict and has declared it closed more than once. Volumes moving through anyway undercut that claim in a practical sense. Influence is not the same as a veto when escorts and pipelines keep oil moving.
The Fuel Crisis Is The Real Economic Risk
Crude headlines are easier to write. Diesel is what hits the real economy. Trucking, farming, mining, construction, and a long list of industrial processes still run on middle distillates. When those barrels go missing, the pain shows up in freight rates, food logistics, and factory costs before it shows up in a neat chart of benchmark crude.
Supplies from the Middle East remain constrained. Attacks on Russian refining capacity have added another cut to the same thin market. Put those two shocks together and you get a global fuel squeeze even while crude seaborne volumes look almost respectable.
The biggest source of pain is the diesel market.
– Bank commodities desk
U.S. diesel prices have been at or near record highs. That is not a niche complaint from energy traders. It is a political problem. An export ban has been floated as a way to keep more fuel at home ahead of a difficult election calendar. The relief from a ban would likely be temporary. Demand does not vanish. It just gets rationed by price or by policy.
Perhaps the most interesting aspect is how quickly public debate jumps to crude when the shortage is actually in products. People hear “oil” and picture a tanker of raw crude. The shortage that can stall a harvest or a freight network is the refined barrel.
Why Refined Products Recover More Slowly
A crude stream is relatively fungible. If one grade is delayed, another can often substitute with a discount or a quality adjustment. A diesel molecule is the output of a specific refinery configuration, a specific sulfur spec, and a specific shipping schedule. Knock one of those over and the replacement is not sitting in a nearby tank farm waiting to be polite.
Product tankers also operate on tighter logistics. Storage for clean products is more specialized. Insurance and routing become harder when a waterway is contested. And once a regional refinery is forced offline or forced to cut runs, you cannot invent spare capacity overnight in Europe or Asia.
- Crude can be rerouted through pipelines and shuttle transfers.
- Product cargoes depend on working refineries and specialized ships.
- Attacks on refining assets remove supply that tankers cannot replace.
- Policy talk about export limits can freeze trade even before a rule is signed.
That sequence is why the rebound looks lopsided. The market solved the “get the raw barrel out” problem faster than the “keep the fuel pool full” problem.
Diplomacy Is Stuck, And That Matters For Prices
Iran offered to reopen Hormuz within a week if Washington returned to a summer memorandum that later collapsed. That earlier understanding included lifting the blockade and leaving room for a future administration system negotiated with Oman. The deal fell apart and fighting resumed.
The latest offer was rejected. Reporting from unnamed officials has pointed to a possible return to strikes after midterm elections. On the other side, there is talk of Iranian escalation into that same political window. None of that is a market-friendly calendar.
In my experience, energy markets can live with a bad status quo longer than they can live with an unclear path. A messy but stable escort system can be priced. A stop-start cycle of talks, threats, and sudden attacks is harder. Traders start adding a risk premium not because today’s barrel is missing, but because next month’s barrel might be.
What “Prewar Levels” Actually Hide
Matching an old seven-day average is not the same as matching an old risk profile. Before the war, a tanker crossed Hormuz as a routine commercial act. Now a large share of those barrels only move because of a military umbrella and a transfer at sea. The number on the page can look identical. The process behind the number is not.
Insurance costs stay elevated. Routing takes longer. Crews demand more. Shuttle logistics eat efficiency. All of that can be absorbed when crude is plentiful and refined products are tight. It becomes a bigger issue if another pipeline is hit, if escorts thin out, or if product inventories in importing regions keep sliding.
I’ve found that the phrase “back to normal” is one of the most overused sentences in commodities. Normal is a system that does not need a navy to finish a commercial voyage. We are not there.
Who Feels A Diesel Shock First
Freight companies feel it immediately. Then farms. Then any industry that moves heavy goods by road. After that, the shock leaks into consumer prices in a delayed and uneven way. A household may not buy a gallon of diesel, but it buys the goods that traveled on diesel.
That is why an export ban keeps coming up in political conversations. It is a visible lever. It is also a blunt one. Restricting outbound fuel can cool a domestic price spike for a short stretch and still leave global balances tighter, which eventually feeds back through other channels.
Is a ban coming? Maybe. Should markets treat it as a cure? Not really. Temporary relief is still relief, but it does not rebuild a missing product barrel from the Gulf or repair a damaged refinery somewhere else.
Asia Still Needs The Barrel
Most of the crude leaving the Gulf still points east. That has not changed. What changed is the way the barrel gets there. Transfers off Oman and the Emirates add a step. Pipelines to the Red Sea add another path. Neither path removes Asia’s need for reliable supply.
If product flows stay suppressed, Asian importers will keep hunting for diesel and jet fuel from farther afield. That lengthens voyages, raises freight, and keeps cracks elevated. Crude can look well supplied at the same time product markets feel scarce. Those two markets are related, but they are not twins.
Market split in one glance:
  Crude seaborne volumes: near or above old norms
  Product flows through Hormuz: still deeply impaired
  Price pain center: diesel and other middle distillates
  Political flashpoint: possible fuel export limits
The Durability Question Nobody Can Dodge
Can the shuttle system last? For a while, yes. Indefinitely, less clear. It burns money, ships, and political capital. Gulf governments also do not see it as a substitute for a functioning strait. They will use it. They will not celebrate it.
Pipelines help, until they are hit. Escorts help, until attention shifts. Diplomacy would help more than either, and diplomacy is the piece that keeps stalling. One former intelligence officer now in the energy advisory world put the direction of travel simply: both sides keep signaling escalation around the same political dates.
That is the uncomfortable backdrop behind every “flows have recovered” chart. The chart can be true today and still be fragile tomorrow.
How To Read The Next Few Weeks
Watch product loadings, not just crude loadings. Watch diesel cracks more closely than the front-month crude contract. Watch whether pipeline volumes stay high after repairs. And watch whether the share of ship-to-ship transfers starts to fade or stays stuck near wartime levels.
If crude holds near 13.5 million barrels a day through Hormuz while products stay under a million, the fuel squeeze remains the story. If product flows start climbing hard, some of the panic around diesel can ease even if geopolitics stay ugly. If escorts wobble, both stories get worse at once.
- Product tanker activity is the cleaner stress gauge
- Pipeline uptime is the hidden swing factor
- Escort intensity tells you how “normal” the strait really is
- Export-policy talk can move diesel before any rule exists
None of that requires a dramatic new attack to matter. A slow grind is enough. Markets get tired of workarounds. Costs pile up. Inventories do the quiet work of turning a shipping problem into a price problem.
A Personal Read On What Comes Next
I do not think the crude recovery is fake. The barrels are moving. The tracking data is not a mirage. I also do not think the fuel market has been fixed just because crude found a hallway around the wreckage.
The honest description is narrower. The Gulf learned how to export raw oil under fire. It has not fully learned how to export a normal slate of fuels under the same conditions. Until that second piece improves, diesel stays the pressure point and the economy stays more exposed than a calm crude chart suggests.
Will diplomacy reopen a cleaner route before politics force another military round? That is the question hanging over every loading program in the Gulf right now. The numbers look steadier than they did at the worst point of the war. The system underneath those numbers still feels like it is holding its breath.
If you only remember one thing, remember the split. Crude can look healed. Fuel can still be broken. That gap is where the next shock, if it comes, will likely start.



