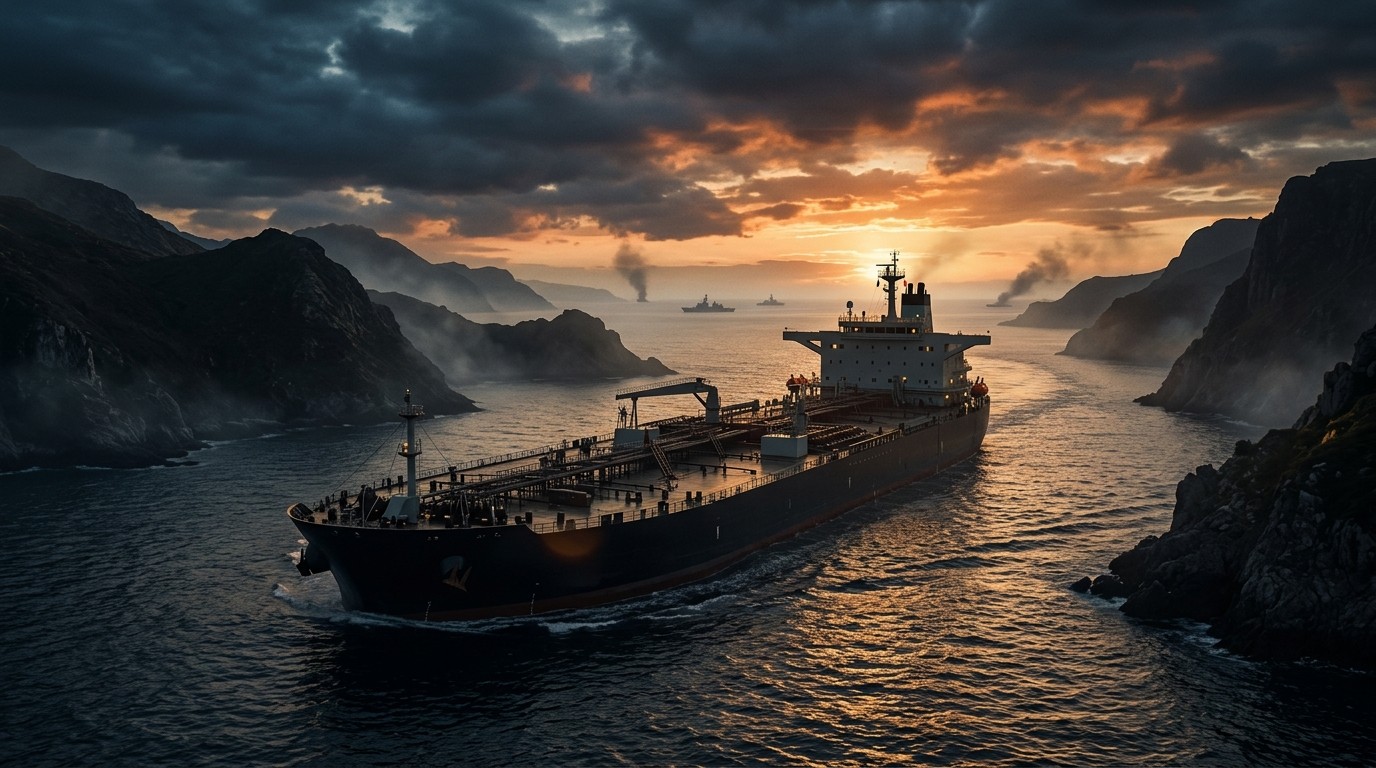

What if the month that looked like pure maritime chaos in the Gulf actually marked the high point of disruption rather than the start of something worse? That question kept circling in my mind after October delivered more commercial vessel attacks near the Strait of Hormuz than any previous period on record. Over thirty-five incidents. A number that should have sent crude prices into a sustained climb. Instead, markets moved the other way once fresh diplomatic signals appeared.
I have followed energy markets long enough to know that chokepoints rarely behave the way textbooks predict. Producers adapt. Shipowners reroute. Traders price in risk and then quietly reduce the premium when the physical barrels keep arriving. October offered a textbook case of this resilience. The attacks hit a record, yet overall flows through the region recovered to at least eighty percent of pre-conflict levels. Some alternative routes performed even better. The result? Brent and WTI futures dropped sharply when news of renewed talks between Washington and Tehran circulated just ahead of the U.S. midterm elections.
Record Attacks Meet Unexpected Supply Resilience
Maritime security in the Gulf has clearly deteriorated in recent weeks. That is not in dispute. The sheer volume of incidents in October tested every assumption about how quickly oil logistics could bounce back. Yet the data tells a more nuanced story than pure crisis. Physical supplies rebounded faster than many expected. Producers and shipowners leaned on longer routes, more complex logistics chains, and higher insurance costs. The barrels still reached the market.
This resilience came with a price tag. Shipping became more expensive and less predictable. Product markets stayed tight. Inventories remained depleted. The system absorbed the shocks but left almost no spare capacity for another major disruption. I find that last point particularly important. Markets can handle elevated risk for a while. They struggle when the buffer disappears entirely.
Why Flows Recovered Despite the Surge in Incidents
Several practical factors explain the rebound. First, alternative pathways absorbed part of the volume. Saudi shipments through the Red Sea, for example, helped offset some pressure on the traditional Hormuz corridor. Second, commercial operators adjusted schedules and increased the use of protective measures. Third, the attacks, while numerous, did not completely close the waterway for extended periods.
In my view, the most interesting development is how little lasting leverage the repeated attacks actually delivered. Rather than choking off crude shipments, the pattern of incidents appears to have accelerated adaptation. That outcome quietly reduces the strategic value of further escalation in the same style. When the market learns to live with elevated risk, the premium attached to that risk starts to erode.
Producers and shipowners have maintained exports through rerouting and more complex logistics, reducing the risk of an immediate supply shock. But this resilience has come at a price.
That assessment captures the current tension perfectly. Near-term supply looks more secure than the headlines suggested. Medium-term vulnerability remains high because inventories are low and product markets are stretched. Any fresh disruption would hit harder than usual.
Diplomatic Signals and the Midterm Calendar
Politics continues to drive the price action as much as the physical market. A renewed diplomatic push between the Trump administration and Tehran ahead of the U.S. midterms helped send oil futures lower. Markets tend to react quickly to any hint of reduced confrontation. The calendar itself adds another layer of uncertainty. Political incentives can shift rapidly around election periods, sometimes producing renewed escalation or further delays in talks.
Recent mediation efforts involving Qatar have raised hopes of progress. At the same time, the conduct of the parties involved offers little basis for confident long-term predictions. I have watched enough of these cycles to remain cautious. Progress on paper does not always translate into calmer waters overnight.
Still, the baseline scenario many analysts now favor is a prolonged but contained conflict. Gulf exports continue despite persistent regional tensions. Under that outlook, oil prices should gradually move lower over time as flows become more dependable and some of the geopolitical premium recedes. October’s record attack tally suggests this adjustment will be slower and more volatile than earlier forecasts assumed.
What a Credible Ceasefire Would Actually Change
Even a credible ceasefire would not immediately restore previous production levels, shipping patterns, or inventories. The recovery in exports has provided reassurance over near-term supply. Fragile security and tight fundamentals suggest that a full return to pre-conflict market conditions will take longer than many expected. That lag matters for traders and policymakers alike.
Consider the inventory situation. Stocks are already lean. Product markets have little room to absorb further shocks. Shipping costs remain elevated. These structural features mean that any genuine improvement in security would still leave prices supported for a while by the need to rebuild buffers. Demand could even receive a temporary boost from restocking activity once confidence returns.
The Shifting Balance of Maritime Leverage
Perhaps the most significant long-term implication is the erosion of leverage around the Hormuz chokepoint itself. When repeated attacks fail to halt the majority of flows, the strategic calculus changes. Tehran’s ability to use maritime pressure as a decisive tool appears diminished compared with earlier periods. That does not mean risk has disappeared. It does mean the market has found ways to mitigate it.
I have found that markets often overestimate the durability of chokepoint disruption and underestimate the speed of commercial adaptation. October provided fresh evidence of that tendency. The record number of incidents tested the system and the system largely held. Higher costs and greater unpredictability remain the price of that resilience, yet the barrels continue to move.
- Record attack volume in October tested recovery assumptions
- Physical flows returned to at least eighty percent of earlier levels
- Alternative routes and complex logistics absorbed part of the pressure
- Shipping costs rose and predictability fell
- Inventories stayed depleted, limiting shock absorption capacity
These points together paint a picture of a market that has absorbed a severe stress test without collapsing. That outcome should temper expectations of sustained price spikes driven solely by the current pattern of incidents.
Price Outlook Under a Contained Conflict Scenario
Under the baseline of a prolonged but contained conflict, the path of least resistance for oil prices points gradually lower. As flows become more reliable and the geopolitical premium recedes, the market can focus again on fundamental balances. That process will not be linear. Volatility is likely to remain elevated, especially while the political calendar remains active and security incidents continue at any meaningful level.
The recovery already seen in exports offers near-term reassurance. At the same time, the combination of fragile security and tight inventories means another major disruption could still produce sharp reactions. Traders must balance these two realities. In practice, that means positioning for a slow grind lower while keeping risk management tight around potential flashpoints.
One subtle factor worth watching is the eventual rebuilding of stocks. Once confidence improves enough for companies to restock more aggressively, that activity itself can support demand even as supply conditions ease. The timing of that shift remains uncertain, yet it forms part of any realistic medium-term outlook.
Practical Implications for Market Participants
For producers, the priority remains maintaining export volumes through whatever routes prove viable. Higher shipping and insurance costs eat into margins, but lost volume would cost more. For shipowners, the environment demands greater flexibility and careful risk assessment on each voyage. For traders, the key is distinguishing between noise from individual incidents and shifts in the overall flow picture.
I have noticed that many participants still treat every new attack as potential market-moving news. That reaction made sense earlier in the cycle. It makes less sense once the cumulative data shows sustained resilience. The market is learning. Pricing is adjusting. The process remains incomplete and subject to sudden reversals, yet the direction of travel is becoming clearer.
| Factor | Current Status | Implication |
| Attack Frequency | Record high in October | Elevated risk premium |
| Export Flows | Recovered to 80%+ | Near-term supply support |
| Shipping Costs | Elevated | Margin pressure |
| Inventories | Depleted | Limited buffer |
| Diplomatic Outlook | Cautiously improving signals | Potential premium reduction |
The table summarizes the core tension. High incident numbers coexist with recovering flows. Costs are higher, buffers are thinner, and diplomacy remains uncertain. That mix produces a market that is both more resilient and more fragile than it appears at first glance.
Looking Beyond the Immediate Noise
October may well prove to have been the peak month for ship attacks in this particular phase of tension. That does not mean the risk has vanished. It does mean the market has demonstrated an ability to adapt that few anticipated at the outset. Diplomatic progress, if sustained, could further reduce the geopolitical premium. Continued incidents without corresponding flow losses would reinforce the same conclusion.
The harder truth is that uncertainty remains considerable. Political calendars, mediation efforts, and on-the-water realities can shift quickly. A prolonged but contained conflict remains the most plausible baseline, yet contained does not mean calm. Volatility should be expected. Price declines should be gradual rather than abrupt. Inventory rebuilding will take time even under improved security conditions.
In the end, the story of October is less about the absolute number of attacks and more about what those attacks failed to achieve. They failed to choke off the majority of crude shipments. They failed to produce a sustained supply shock. They accelerated commercial adaptation instead. That outcome changes the strategic landscape around the Strait of Hormuz in ways that will matter long after the current news cycle fades.
Markets rarely reward the same tactic indefinitely. Once resilience becomes visible, the leverage attached to disruption declines. October provided a clear demonstration of that principle. Whether the coming months confirm the peak or deliver new surprises will depend on both diplomacy and the continued ability of producers and shipowners to keep the barrels moving. For now, the evidence points toward a slow, uneven path toward lower prices and reduced geopolitical premium, punctuated by the inevitable bouts of volatility that always accompany Gulf tensions.
The practical takeaway is straightforward. Treat the record attack tally as important context rather than a permanent new normal. Watch the flow data more closely than the incident headlines. Monitor diplomatic signals without over-interpreting every statement. And remember that resilience, once proven, tends to become self-reinforcing until a genuinely new form of pressure appears. That is the environment oil markets are navigating today, and it is likely to define price action for some time yet.