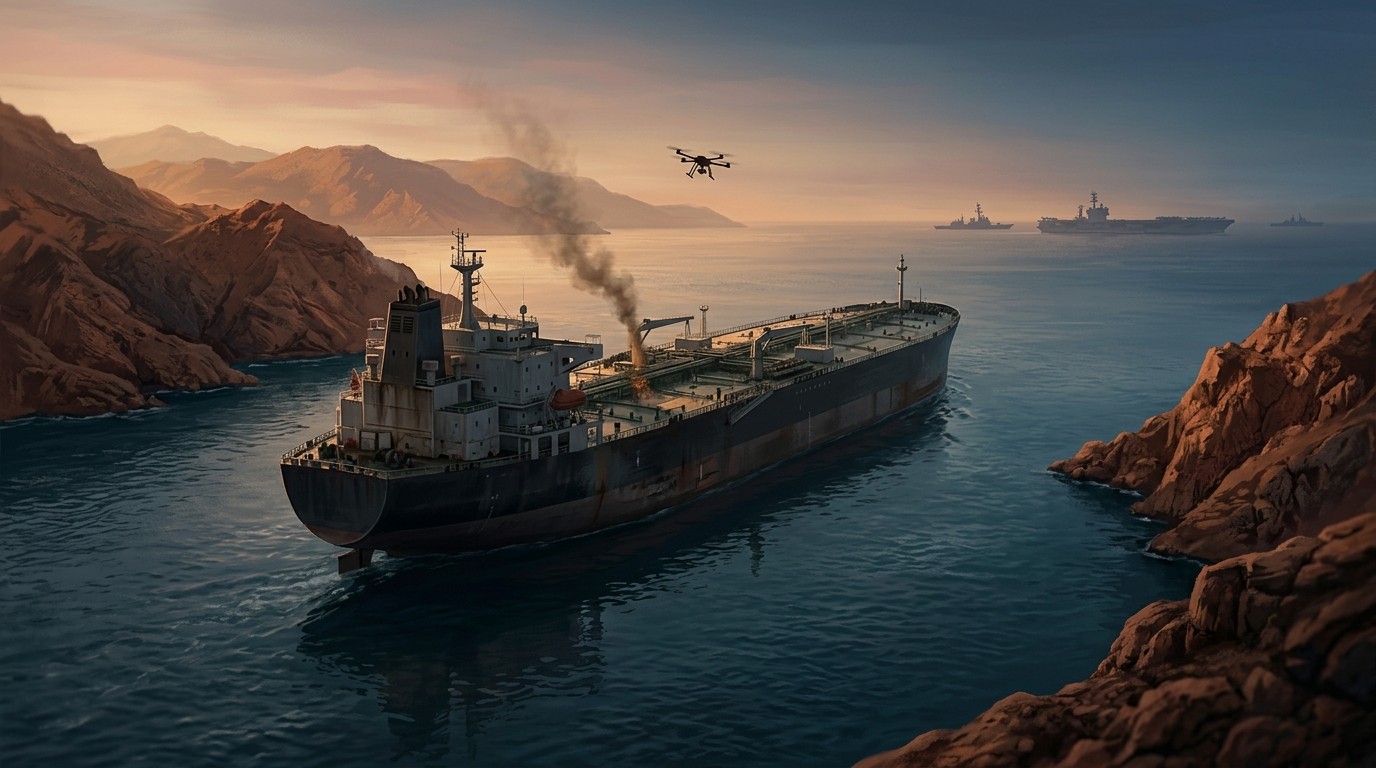

I checked the oil screen twice before I trusted it. Another commercial tanker had just been reported struck and damaged in the Strait of Hormuz, the sixth shipping alert in a couple of days, and the benchmark that usually jumps at a rumor of a dinghy was sitting there like nothing had happened. Brent had kissed nearly $104 overnight on a different headline, then slipped back under $100 as Asia handed the session to Europe and the early U.S. hours. A damaged hull in the world’s tightest energy lane, and the tape looked bored. That mismatch is the story.
If you trade energy, or you simply pay for gasoline, heating, and freight, you have been trained to treat Hormuz as a panic button. Roughly a fifth of the world’s seaborne oil has historically squeezed through that narrow corridor between Iran and Oman. A single credible disruption used to be enough to reprice the whole complex. This week the alerts stacked up, the damage reports kept coming, and the price reaction stayed strangely small. I’ve found that when the market refuses the script, it is usually telling you something the headlines are not.
Why Another Damaged Tanker Barely Moved The Tape
Start with what was actually reported, not with the movie version. Shipping monitors issued a fresh alert that a foreign tanker had been struck and damaged in the strait. Similar drone-style incidents had already marked the week. Unlike earlier episodes, these latest hits were not dominating front pages, and they were not dominating futures either. That gap between physical risk and financial reaction is where a serious reader should slow down.
Markets do not price the event. They price the change in the expected path of supply. A struck tanker is frightening on a human level. For a barrel, it matters only if it changes how many barrels clear the lane tomorrow, next week, and next quarter. If flows are already back near their pre-conflict pace, if shipowners are still willing to transit with a war-risk premium rather than a full diversion, and if buyers have alternate barrels in storage or on the water, the marginal incident can look loud and still be small in the model.
Perhaps the most interesting aspect is how quickly traders have started to separate harassment from closure. Harassment raises insurance, slows some voyages, and bruises a hull. Closure, even a partial one that lasts weeks, rewrites refinery runs from Rotterdam to Yokohama. The tape this week is voting for the first category. I am not sure that vote is wise. It is, at least, coherent.
What A Sixth Alert Actually Signals
Six alerts in a short window is not noise. It is a pattern. Shipping desks track these notices the way bond desks track auction tails: one odd print can be a glitch, a cluster is a regime. The cluster says someone with access to one-way attack drones, or to small craft that can mimic that profile, is willing to put steel on commercial hulls inside a chokepoint. Whether every strike is centrally directed or some are proxy improvisation matters for diplomats. For a charterer, the distinction is academic. The hull still has a hole.
There is a second signal inside the quiet coverage. When similar incidents used to lead every broadcast, the political cost of the next strike was higher. Lower visibility can lower that cost. I have watched this movie in other markets. Attention is a deterrent. When attention fades, the perpetrator tests whether the next step still draws a response. A muted oil price can accidentally send the same message: the market has absorbed you, so try again.
A damaged tanker is a fact about one ship. A week of alerts is a fact about the lane. Only the second one belongs in a risk model.
That is the frame I would keep. Do not romanticize a single plume of smoke. Do not ignore a sequence. The sequence is what underwriters, naval planners, and refinery buyers are actually discussing, even if the front-month contract looks calm on your screen.
Flows Came Back, And That Changed The Math
Recent flow tracking from major commodity desks has pointed to a recovery in crude movements through the strait, back toward the pace seen before the wider confrontation. If that reading is right, Tehran’s practical grip on the lane has loosened even while the headlines still sound ominous. Ships are moving. Buyers are lifting. The chokepoint is stressed, not sealed.
Recovery in flows does two things at once. It calms the prompt contract, because barrels are arriving. It also creates a false sense of permanence. A lane that is open today can be contested tomorrow if the political decision changes. Flows are a snapshot. Intent is a variable. Traders who treat the snapshot as a promise are the ones who get hurt when the variable flips.
Think of it like a bridge that has reopened after repairs while someone is still throwing rocks at the traffic. Commuters resume the route because the alternative is a long detour. The insurance company does not resume the old premium. Both reactions are rational. Oil has been behaving like the commuter. The insurance market, from what desk chatter suggests, has been behaving more like the underwriter.
The Overnight Spike That Faded
Context matters for the calm. Overnight, reports that a third aircraft carrier strike group and additional Marine ships were being prepared for the region pushed Brent toward $104. That is not a small move. It is the market doing what it is supposed to do when force posture changes. Then the contract gave the gain back as the session rolled west, sliding under $100.
Fade after a headline is normal. Algorithms buy the first print, humans sell the follow-through if inventories, spare capacity, and demand worries still lean the other way. What is less normal is fading a force-posture story and a hull-damage story in the same breath. One of those should have stuck. Neither really did, at least not in the front month.
In my experience, that kind of double fade usually means positioning was already long the fear. If funds had bought the conflict weeks ago, fresh headlines become an exit, not an entry. The price then looks complacent when it is actually just crowded. You cannot see that on a chart of the settlement alone. You see it in how little follow-through a genuinely new fact receives.
A Simple Map Of What The Market Is Discounting
Strip the noise and the oil market is currently discounting a narrow set of outcomes. It helps to write them down, because the mind tends to blur “bad” into “catastrophic” and then wonder why the price did not explode.
| Scenario | What changes for barrels | How the tape has treated it |
| Isolated hull strikes | Insurance up, a few delays, no lost volume | Mostly ignored after the first alert |
| Sustained harassment | Slower voyages, higher freight, some rerouting | Priced in the back of the curve, not the front |
| Pipeline or plant outage | Regional barrels offline for weeks | Spikes, then fades once flows resume |
| Partial lane closure | Millions of barrels seek a longer route | Not the base case this week |
| Wider strike campaign | Infrastructure and shipping both impaired | A tail risk, not a prompt price |
The table is a sketch, not a forecast. Still, it explains the boredom. The incidents reported this week sit in the top two rows. The price that would belong to the bottom two rows has not been asked to show up. Yet. The word that should bother you is yet.
Air Defenses Moving Toward The Energy Targets
While the futures screen shrugged, the force posture did not. Reporting this week described two additional Patriot batteries shifted into the Gulf, one toward a key Saudi oil facility and one toward a natural gas plant in Qatar. The systems and their interceptors were pulled from other regional commands. That detail is easy to skip. It should not be skipped.
A Patriot battery is built to deal with aircraft, cruise missiles, some ballistic missiles, and one-way attack drones. Moving two of them onto energy sites is a statement about what planners think the next target set looks like. They are not mainly worried about a parade. They are worried about the pipes, the plants, and the export points that turn geology into cash flow.
Pulling those batteries from somewhere else also has a cost that never makes the oil headline. Readiness in the region that gave them up is thinner until replacements arrive. Defense is a inventory problem, same as crude. You cannot intercept a drone with a press release. Every launcher parked over a gas plant is a launcher not parked somewhere else. I’ve found that investors who only watch Brent miss this second balance sheet entirely.
- One battery was described as covering a major Saudi oil facility after earlier damage to export routes.
- A second was described as covering a Qatari gas plant, which matters for global LNG as much as for crude.
- Interceptors moved with the launchers, which is the scarce item in any prolonged drone campaign.
- The transfer came from other commands, so the protection is real and the opportunity cost is real.
None of that is a prediction that the batteries will be used. It is evidence that people who get paid to be early are acting as if the energy system is the target, not a bystander. Markets can disagree with generals. They should at least notice what the generals are moving.
The Pipeline That Went Dark, Then Came Back
Last month, proxy forces were reported to have hit the East-West pipeline, the overland route that lets Saudi barrels reach the Red Sea without transiting Hormuz. The line was described as inoperable for weeks. Flows were restored only recently. That episode is the cleanest recent proof that energy infrastructure, not just tankers, sits inside the target set.
Why does a pipeline matter to a story about a tanker? Because it shows the substitute can be hit too. Traders love optionality. If the strait is risky, send the barrel west across the peninsula and out the Red Sea. If that pipe is down, the option disappears. A week of tanker alerts plus a recently repaired bypass is a tighter system than either fact alone.
Restoration is good news. It is also a reminder of repair time. Weeks offline is not a headline you fade in an afternoon. Refiners who lost those barrels had to cover. Some of that cover is still in the system as extra inventory or extra floating storage. That cushion helps explain the calm. Cushions deplete. They do not renew themselves because a futures trader feels relaxed.
A Third Carrier Group And The Troop Math
Alongside the Patriot moves, reporting described preparations to send a third aircraft carrier strike group and additional Marine ships, on the order of 9,000 to 10,000 more personnel. Carrier math is blunt. One group is presence. Two is a campaign posture. Three is the kind of density you assemble when you want options that do not depend on a single deck being in the right place.
Public comments from the U.S. president framed the choice in stark terms: a deal, or a renewed bombing campaign in the coming weeks, with language to the effect that Iran either signs or does not continue to exist in its current form. You do not need to endorse that framing to see what it does to an oil risk premium. It shortens the clock. Diplomacy with a deadline trades differently from diplomacy without one.
Here is the awkward part for anyone holding a short-vol energy position. The same week that produced a damaged tanker and a sixth alert also produced extra air defense on energy sites and talk of a third carrier. The futures market treated the package as a fade. Policy and logistics treated it as a buildup. Those two readings can coexist for a while. They do not coexist forever.
Price is a vote. Force posture is a preparation. When they diverge, one of them is early.
A desk rule worth keeping
Why Oil Can Fall While Risk Rises
This is the section friends in other markets always argue with me about. How can the physical risk be up and the price be down? Easily, if you remember what else is in the barrel.
Demand is not a backdrop. If industrial activity in the big importing economies is soft, a supply scare has to be large before it overwhelms the demand drag. Spare capacity outside the Gulf still exists, even if it is concentrated and politically awkward to call on. Strategic stocks, commercial stocks, and barrels already on the water act as shock absorbers. A strike that does not stop loadings is a story. A strike that stops loadings is a shortage. This week’s reports, so far, are stories.
There is also the positioning point I mentioned. If the conflict premium was bought in earlier, later headlines become supply of futures, not demand for them. Selling into strength is not the same thing as believing the strait is safe. It can mean a fund hit its risk limit and needs the line item smaller before the weekend.
And then there is simple fatigue. Traders are human. After weeks of alerts that did not become a closure, the next alert gets a smaller bid. That habituation is how squeezes start. The market stops paying for insurance exactly when the insurer would most like to collect. I would not call the current price reckless. I would call it conditional, and I would want to know which condition breaks it.
Insurance, Freight, And The Hidden Premium
The cleanest place to look, when the flat price lies, is the stuff around the flat price. War-risk premiums on hulls transiting the strait. Freight rates on the routes that avoid it. The time charter equivalent a owner demands before sending a modern vessel into a lane with six recent alerts. These numbers do not always flash on a retail app. They are where the fear actually clears.
A owner who can earn a normal rate in the Atlantic does not volunteer for Hormuz out of patriotism. The charterer has to pay up, or the ship goes elsewhere. That pay-up can rise for weeks before the headline crude contract admits anything is wrong. If you only watch the settlement, you will think the world is calm while the people who move the oil are already repricing the trip.
There is a practical consequence for anyone who buys refined products. Freight and insurance leak into the crack, then into the pump, with a lag. A quiet Brent print does not guarantee a quiet diesel print two weeks later if the ships that carry middle distillates are the ones demanding the premium. Energy risk is a chain. The tanker is one link. The invoice at the other end is another.
Where the premium hides when flat price looks calm:
  War-risk cover on the hull
  Freight on avoidance routes
  Time lost to slower convoying
  Refinery cover for a bypass that just restarted
  Interceptor inventory pulled from other theaters
What A Real Disruption Would Do To The Barrel
It is worth being concrete, because vague fear is useless. A partial interruption that pushed even a few million barrels a day onto the longer route around the Cape would not be a rounding error. Voyage times stretch. Tankers get tied up. The same fleet moves less oil per month. Spot freight spikes. Refiners in Asia and Europe bid for replacement barrels from farther away. The prompt contract, which shrugged at a damaged hull, would not shrug at a lost week of loadings.
The Cape route is not a theoretical backup. It is a real one, and it is expensive in days and in ships. Every extra week a vessel spends at sea is a week it cannot load again. That is why chokepoints punch above their geography. The strait is short. The consequence of avoiding it is long. People who say “they can just sail around” have usually never priced the around.
Add the pipeline variable. If the overland bypass is healthy, some Saudi volume never needs the strait. If the bypass is freshly repaired and still a demonstrated target, that relief is thinner than the map suggests. Iraqi, Kuwaiti, and other Gulf loadings have fewer elegant alternatives. A lane problem is not a single-producer problem. It is a system problem, which is why it belongs in a global markets note and not only in a regional brief.
Gas Is Not A Sideshow
One of the two Patriot batteries was described as protecting a natural gas plant in Qatar. That detail pulls LNG into a story that looks, at first glance, like a crude story. Qatari exports matter to European and Asian gas balances in a way that a single crude tanker does not. A drone campaign aimed at energy infrastructure does not have to sink ships to move the other half of the hydrocarbon complex.
I keep a small mental split for this. Crude is the thing everyone screenshots. Gas is the thing that shows up later in power prices, fertilizer costs, and winter heating debates. If planners are parking interceptors over a gas plant, they are not doing it for the photograph. They are doing it because a successful hit there would travel through utility bills on other continents.
For a portfolio, the implication is simple and often ignored. A Hormuz risk premium is not only a long-Brent idea. It can be a relative idea between crude, products, and gas, and it can be a freight idea before it is a commodity idea. Narrowing it to one futures contract is how people miss the move they were trying to catch.
How Investors Tend To Misread Chokepoint Weeks
A few recurring mistakes show up every time this lane gets noisy. Naming them is more useful than another map of the Gulf.
- Treating every alert as a closure, then feeling cheated when the price does not double.
- Treating a calm price as proof the lane is safe, which confuses a vote with a fact.
- Ignoring repair lags on pipes and plants, which is where the real lost barrels hid last month.
- Forgetting that interceptors and tankers are both inventories with replacement times.
- Assuming diplomacy and force posture cannot accelerate in the same fortnight.
The fifth one is the live risk. A public warning that a deal must come soon, paired with a third carrier group and extra batteries on energy sites, is an acceleration whether or not you like the politics. Markets are allowed to fade it. They are not allowed to pretend it was not said.
A Working Checklist For The Next Alert
You do not need a war room. You need a short list you can run when the next notice hits, so you are not trading the adjective in the headline.
- Did loadings stop, or did one hull take damage while others kept moving?
- Are tracked flows through the lane still near the recovered pace, or have they rolled over?
- Is the overland bypass still running after its recent restart?
- Did freight and war-risk quotes jump even if flat price did not?
- Did the force-posture story change, or is this the same carrier headline recycled?
- Are interceptors being drawn down faster than they can be replaced?
Run that list and most alerts sort themselves. The ones that fail two or more lines are the ones that deserve a position change. The ones that fail none are the ones the market is right to fade. This week’s sixth alert, on the public facts alone, looks closer to the second bucket. The surrounding military moves look closer to the first. That tension is the trade, if there is one.
Diplomacy With A Clock On It
Deadlines change probabilities. A negotiation that can drift for months is one distribution. A negotiation that has been publicly tied to a decision “in the coming weeks” is another. The second distribution has fatter tails, even if the center of it still says a deal gets sketched and the bombs stay in the rack.
I am not going to pretend to know which way that decision breaks. Anyone who tells you they do is selling something. What can be said, without theatrics, is that energy infrastructure has already been hit in this cycle, shipping alerts are clustering again, and the hardware being moved is the hardware you move when you expect aerial threats against plants and export routes. The oil price is allowed to wait for proof. Waiting is not the same as being protected.
There is a personal bias I should admit. I have sat through enough false chokepoint scares to distrust the first headline, and enough real outages to distrust the calm that follows the fifth. Both scars are useful. Neither is a model. The model is flows, freight, repair status, and whether the people with launchers are still adding to the region or starting to pull them back.
What Calm Gets Wrong About Repetition
Repetition is the underpriced feature of this week. One strike can be a probe. Six alerts start to look like a method. Methods scale. A actor who has learned that a damaged tanker produces a paragraph and a fifty-cent wiggle has learned something valuable, and not in a way that comforts a charterer.
Deterrence is partly a story the other side believes. If the story they believe is that commercial shipping can be brushed and the financial consequence stays small, the cost of the next brush falls. Extra Patriot batteries and a third carrier are an attempt to rewrite that story with hardware. Hardware takes time to arrive and time to matter. The gap between the announcement and the arrival is a window, and windows are when probes happen.
So the quiet tape is not proof of safety. It is proof that, so far, the method has not crossed into lost volume. Those are different sentences. Conflating them is how a careful reader becomes a surprised one.
Regional Commands And The Readiness Tradeoff
Moving batteries from other commands is a footnote in most market notes. It deserves a fuller look. Air defense is not an infinite pool. A theater that gives up launchers and interceptors is a theater that has decided the Gulf energy system outranks its previous task, at least for this rotation. That decision can be correct and still leave a hole behind it.
For energy investors the relevant point is priority. When scarce kit is pointed at oil facilities and gas plants, the official threat ranking has already been updated. You can disagree with the ranking. You should not claim the ranking does not exist. The market’s ranking, visible in a sub-$100 Brent print after a fresh hull strike, is softer. Divergent rankings are where mispricings live, in both directions.
If the next month is quiet, the batteries will look like expensive caution and the fade will look smart. If the next month includes a hit on a plant that those batteries were sent to cover, the fade will look like the thing people apologize for in letters to clients. Both outcomes are available from here. Position size should respect that, even if conviction leans one way.
Products, Refiners, And The Second-Order Bill
Crude is the celebrity. Products pay the bills. A refinery that loses a week of a specific Gulf grade does not simply “buy Brent.” It buys a substitute with a different yield, pays up in the spot window, and may cut runs if the substitute is wrong for the kit. That is how a shipping alert becomes a diesel story or a jet story without the flat price ever looking dramatic.
Last month’s pipeline outage was a preview. Weeks of lost bypass volume forced covering. Restoration brings the barrel back, but the product market does not rewind perfectly. Cracks can stay bid after the crude scare fades, because the refinery already changed its slate and the product inventory already took the hit. Anyone staring only at the overnight Brent spike and its fade missed that second bill.
I would watch middle distillates more closely than the headline crude print over the next few weeks. Not because a shortage is assured. Because that is where a cluster of small shipping frictions and a recently repaired bypass tend to show up if they show up anywhere.
The Human Layer The Screen Leaves Out
A tanker strike is also a crew story, and it is worth saying so without turning the note into a speech. People stand on those decks. A drone or a small-craft hit is not an abstraction to them, even if it is an abstraction to a futures blotter. The reason shipping alerts exist is that someone has to decide, in real time, whether to alter course, whether to request escort, whether the damage is survivable. Markets that forget the human layer eventually misread the operational one. Crews that will not sail are a supply shock no model has a cell for.
So far, the recovery in flows says crews and owners are still willing, at a price. Willingness is reversible. A week that stays at “damaged, continued” is one regime. A week that becomes “abandoned, blocked fairway” is another. The distance between those weeks can be a single bad hit in a traffic separation scheme. That is not alarmism. It is how narrow water works.
Prompt risk vs lane risk: one hull can be repaired; a fairway that crews refuse cannot.Reading The Next Fortnight Without The Noise
Between now and the political deadline that has been floated, three things will tell you more than the adjectives.
First, whether alerts stay at the level of damage or step up to interrupted loadings. Second, whether the third carrier group actually sails and whether the Patriot coverage stays in place or gets reinforced again. Third, whether tracked crude flows hold the recovered pace or slip as owners quietly decline fixtures. If all three stay benign, the fade was the right trade and the risk premium belongs in insurance, not in flat price. If one of them breaks, the calm was borrowed time.
I lean toward respecting the flow data until it turns, and respecting the force posture until it reverses. That is an uncomfortable pair. It means the base case can be “barrels keep moving” and the hedge case can still be “do not be naked a gap through a chokepoint in a deadline week.” You can hold both without being confused. Confusion is what happens when you need a single adjective for a situation that has two speeds.
A Note On What We Do Not Know
Attribution in these incidents is often faster in commentary than in evidence. A shipping alert can confirm a strike and a damage report without settling, in public, every detail of who launched what. Proxy networks, direct units, and opportunistic actors can produce similar scars on a hull. For a risk note, the operational fact is enough: commercial shipping in the strait is being hit, repeatedly, in a window when energy sites ashore have also been hit and when extra defenses are being parked on top of them.
Precision matters because sloppy blame produces sloppy trades. You do not need a courtroom narrative to respect a cluster of alerts. You do need to avoid building a position on a detail that has not been established. The established pieces are the alerts, the damage reports, the recovered-then-still-fragile flows, the pipeline outage and restart, the battery transfers, and the carrier preparations. That set is already enough to write a serious view.
Anything beyond that set is a forecast, and forecasts in this lane have a habit of expiring before the voyage does. Hold them lightly.
Where This Leaves A Practical Reader
If you came here for a price target, you are in the wrong note. If you came here to understand why a sixth Hormuz alert did not rewrite the screen, the answer is ordinary and a little unsettling. Flows recovered. The hits, so far, look like damage rather than stoppage. Positioning was already paid up for fear. Demand is not on fire. The market has decided this is harassment inside an open lane, and it has priced it that way.
The unsettling half is everything moving underneath that decision. Air defenses shifted onto oil and gas sites from other commands. A bypass pipeline that was dark for weeks only just restarted. A third carrier group is in the conversation, with thousands more personnel attached. A political clock has been described in weeks, not in seasons. None of those items are in the front-month settlement in a way you can point at. All of them sit in the distribution of what the next settlement might have to absorb.
I would rather be early to that distribution than loyal to the calm. Loyal to the calm is how the last comfortable print becomes the one you explain later. Early does not mean leveraged, and it does not mean certain. It means the checklist stays on the desk, the freight quote gets a glance before the flat price does, and a damaged tanker in a narrow strait is allowed to be small without being dismissed.
The screen can be right today and still be borrowing. Borrowed calm has a due date. In this case the due date may be a fixture that does not get done, a fairway that gets cluttered, or a decision in a capital that has already told you the window is short. Until one of those arrives, the barrels move and the price yawns. Just do not confuse the yawn with a guarantee.