
Have you ever watched a country grow so fast that every forecast about its power system feels outdated within a year? That is the feeling I get when I look at India right now. Electricity use keeps climbing. Factories want more. Homes want more cooling. Yet something unusual showed up in the latest two-year snapshot: coal power generation did not grow between the first half of 2024 and the first half of 2026. For a nation long treated as the world’s second-largest coal consumer, that pause is not a rounding error. It is the first such two-year stretch in more than half a century.
What The Two Year Pause Actually Means
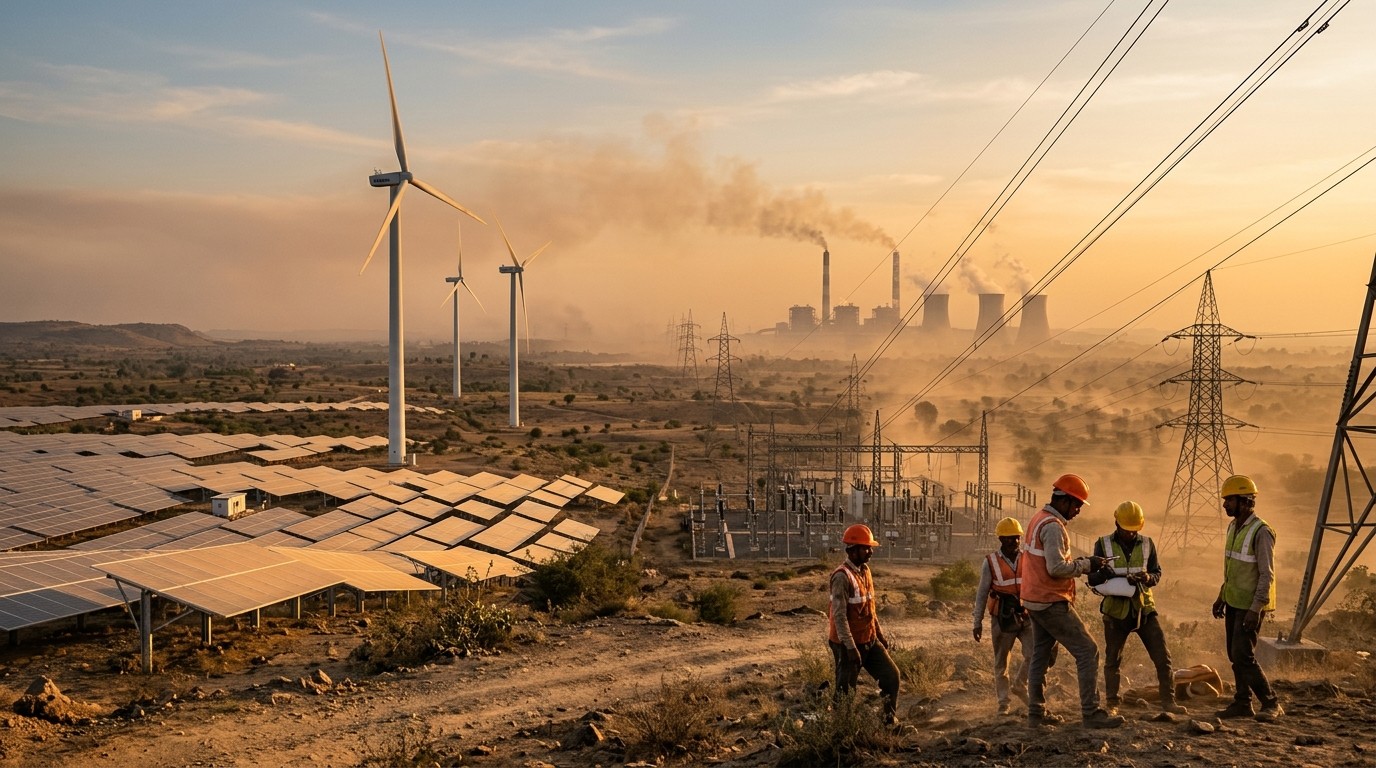
Let me be plain. Flat coal output does not mean coal vanished. It still supplies roughly two-thirds of total power. What changed is the increment. New demand was largely absorbed by non-fossil generation, and that increment was the largest on record for a comparable period. I’ve found that people often hear “clean energy boom” and imagine a sudden swap of one fuel for another. Reality is messier. The old workhorse stays. The new fleet just finally grew fast enough to keep the old workhorse from expanding its hours.
That distinction matters for anyone who tracks commodities, utilities, or emerging-market risk. A stall in generation is not the same as a stall in capacity. Plants can still be poured in concrete while the existing fleet runs fewer extra hours. India is living in that split-screen moment.
Record Non Fossil Generation, Not A Fairy Tale
The clean build-out did the heavy lifting. Solar parks, wind corridors, hydro swings, and nuclear baseload together delivered the biggest jump in non-fossil electricity India has posted for a first-half comparison of this kind. You can almost hear the grid groaning under the speed of the additions. Some days the sun does exactly what planners hoped. Other days clouds and weak wind leave operators staring at the coal stack like an old insurance policy they promised they would not need.
In my experience, record additions look prettier on a slide than they do at 6 p.m. in a heat wave. Peak demand still arrives when solar is fading. Storage is growing, but not at the same tempo as panels. So the boom is real, and so is the residual anxiety. Both can be true at once.
The period from the first half of 2024 to the first half of 2026 saw the largest increase in non-fossil power generation on record in India.
That line, from energy analysts who track hourly and monthly balances, is the core of the story. Demand rose. Coal did not have to rise with it. For a system that spent decades treating coal as the default answer to every extra kilowatt-hour, that is a structural shift, even if the shift is incomplete.
Why Coal Still Looks Immovable From The Control Room
Ask a grid operator what keeps the lights on during a brutal May afternoon and you will not hear a speech about net-zero slogans. You will hear about ramp rates, spinning reserve, and the fear of cascading trips. Coal units, for all their emissions baggage, still offer dispatchable megawatts at a scale batteries have not fully replaced. Authorities also want to avoid blackouts when heat waves crush records. That political memory is sticky. One ugly outage can undo a year of cheerful capacity charts.
So coal remains a key pillar of the mix. About two-thirds of output still comes from it. I keep coming back to that fraction because it refuses to shrink as fast as the headlines about new solar auctions. Capacity can look green on paper while energy, the thing people actually consume, stays brown for longer.
- Coal still covers most annual electricity, not just emergency hours
- Heat waves keep baseload and mid-merit plants politically precious
- Renewables cut the growth of coal use before they cut the stock of coal use
- Transmission bottlenecks can leave clean plants stranded while coal runs nearby
None of that makes the two-year pause meaningless. It simply means the pause is a flow story, not a stock story. Generation flattened. The installed coal fleet did not retire in sympathy.
The Construction Pipeline Nobody Should Ignore
Here is the part that surprises readers who only skim the boom narrative. A total of 43 gigawatts of coal-power capacity was under construction as of the end of June 2026. That is not a museum piece. That is steel, boilers, and multi-year capital still moving. Overall coal-fired installations continue to rise even while generation stalled for two years.
Why build more if output is flat? Because planners think in peaks, not averages. Because states still sign plants that take years to finish. Because industrial policy still treats domestic coal as a hedge against imported fuel shocks. And because “avoid blackouts” is a sentence that wins arguments in rooms where carbon accounting does not.
I’ve sat with enough investment notes to know this pattern. Capital lags data. By the time the two-year pause is visible in charts, the concrete for the next units is already poured. Those units will want hours. They will compete with cheaper midday solar. They may run less than designers hoped. They will still sit on the books as stranded-risk candidates or as reliability assets, depending on who is speaking.
| Signal | What It Shows | Investor Read |
| Flat coal generation, 2024 H1 to 2026 H1 | Clean additions absorbed demand growth | Coal hours under pressure |
| Record non-fossil generation increase | Fastest clean surge on record for the window | Equipment and grid names in play |
| 43 GW coal under construction | Capacity still expanding | Future utilization risk |
| Two-thirds coal in the mix | Energy, not capacity, stays coal-heavy | Transition is multi-decade |
Fossil Capital Has Not Left The Building
Despite the record clean surge, major capital still chases fossil pathways. New coal-power capacity is only one file on the desk. There are plans for coal-to-chemicals conversion and a push to lift domestic coking coal for steel. That last item is easy to forget if you only watch the power market. Steel does not run on cheerful rooftop panels. It wants metallurgical coal with specific chemistry. Import bills hurt. Domestic mines look like strategy, not nostalgia, to a planner who remembers supply scares.
Is that sustainable in a climate-constrained world? Fair question. Officials tend to answer with a different question. How do you keep industry competitive while the grid is still learning to balance weather-driven supply? One senior energy adviser at a government policy think tank put it bluntly late last year: coal will remain a key part of the power system for the next two decades. The line that stuck with me was simpler.
We cannot be subjective about coal. The question is how sustainably we can use it.
– Government energy policy adviser
Subjective is doing a lot of work in that sentence. It is a way of saying ideology will not keep factories open. It is also a way of keeping optionality. “Sustainable use” can mean better plants, higher efficiency, less local pollution, or just a slower fade. Listeners hear what they want.
Demand Growth Is The Quiet Character In This Play
None of this drama exists without demand. India is adding air conditioners, data halls, metro lines, and electrified process heat. When demand grows and coal generation stays flat, renewables and other non-fossil sources are, by definition, covering the extra slice. That is the optimistic reading, and it is mostly fair.
The less cheerful reading is seasonal. A mild monsoon or a savage heat dome can shove the system back toward coal in a single quarter. Two-year averages hide those spikes. I have learned to distrust any energy story that only cites a half-year versus half-year print without asking what the worst week looked like.
Perhaps the most interesting aspect is how ordinary the demand driver is. It is not a speculative bubble. People want cooler rooms. Industry wants reliable power. That banality is why the pause in coal generation is impressive. The system absorbed a very human kind of growth without feeding the coal stack more fuel, at least across that window.
Reliability, Heat, And The Politics Of Not Blinking
Blackouts are not an abstract risk. They are television footage, opposition speeches, and ruined inventory. That is why coal keeps a political bodyguard. Renewables can be cheap at noon and still leave a minister exposed at dusk. Storage and flexible gas can close that gap. They are not yet cheap and abundant enough everywhere the gap appears.
So the clean boom and the coal pipeline are not opposites in the Indian playbook. They are a hedge pair. Build the new stuff as fast as auctions allow. Keep enough thermal iron in the fire that a bad weather year does not become a legitimacy crisis. You can dislike that logic and still recognize it as logic.
- Watch peak-hour residual demand, not only annual generation shares.
- Track how many new coal megawatts actually synchronize, not just get announced.
- Follow storage tenders the way commodity desks follow inventory reports.
- Separate power-sector coal from coking coal for steel. Different markets, different politics.
- Ask whether transmission is keeping up with the best solar states.
If you only do the first item, you will understand why officials refuse to declare victory. Residual demand after sunset is where careers get tested.
Markets Hear Two Stories At The Same Time
Commodity desks used to treat Indian coal appetite as a one-way escalator. A two-year generation pause chips that habit. Seaborne thermal coal is more sensitive to Chinese swings than to Indian ones on many days, but a structural flattening in Indian burn still changes the longer map. Mining firms, rail freight, and port planners all live on volume assumptions. Flat generation with rising capacity is an awkward combo for those assumptions.
Equity investors split into camps. One camp sees renewable manufacturers, developers, and grid hardware as the only ticket worth holding. The other camp notes that utilization risk on new coal plants does not cancel cash flow on existing ones, especially if tariffs and availability payments still work. I lean toward a both-and stance. The boom is the growth engine. The coal fleet is the ballast. Ballast is dull until the storm hits.
Currency and rate watchers should care too. Energy import bills move the external account. More domestic non-fossil generation can trim some fuel imports. More domestic coal mining can trim others. Chemicals-from-coal schemes try to substitute yet another import line. Whether those schemes pencil out is a separate, and often uglier, spreadsheet.
What “Sustainable Use” Could Mean In Practice
If coal stays for two decades, the fight shifts from existence to quality. Higher plant efficiency. Better particulate controls. Smarter cycling so units do not sit dirty and idle. Less water stress in already dry basins. None of that turns coal into a climate hero. It can turn a messy phase-down into a less brutal one for local air and for workers whose towns were built around pits and boilers.
There is a human layer here that tidy energy models skip. Mining districts do not rebrand overnight. Rail towns do not become solar towns because a slide deck said so. A serious transition plan talks about skills, pensions, and land. A unserious one only talks about gigawatts.
I’ve found that the most honest conversations admit trade-offs out loud. Clean energy is winning the incremental megawatt-hour. Coal is defending the difficult hour. Policy is trying to keep both constituencies from exploding. That is not elegant. It is recognizable.
The Next Two Years Will Test Whether The Pause Sticks
A two-year flat line can be a turning point or a weather-assisted blip. The test is simple to state and hard to pass. Can non-fossil generation keep covering demand growth while storage and transmission catch up? Can new coal units enter service without dragging generation back onto an upward slope? Can heat extremes be met without a political panic that greenlights another wave of plants?
Watch monsoon quality. Watch industrial output. Watch how fast batteries actually commission, not how fast they get pledged. Watch whether coal-to-chemicals remains a talking point or becomes a capex cycle. Those are the hinges.
Simple scoreboard I keep on a notepad:
  Demand growth: still structurally strong
  Clean incremental supply: record in the latest window
  Coal generation: flat across two years
  Coal capacity: still being built
  Political constraint: no blackouts, full stop
If demand accelerates faster than clean firm power, the flat line breaks upward. If storage and grids surprise to the upside, the flat line can become a gentle decline. I would not bet the farm on either extreme this week. I would bet that the argument gets louder, because the data finally gave both sides a fact they can wave.
A Cleaner Reading For Anyone Who Has To Decide Something
If you allocate capital, treat the pause as evidence that renewables can police coal’s growth, not as evidence that coal assets are finished. Price utilization risk into new thermal projects. Favor grids, storage, and developers who can deliver at peak, not only at average. If you set policy, stop talking as if capacity additions and energy shares are the same chart. They are not.
If you simply follow the news, keep the sentence short enough to remember. India just lived through a historic stall in coal generation while demand rose, because clean power had its best growth burst on record. The country is still pouring coal plants and still talking about chemicals and coking coal. That is not hypocrisy so much as a system that refuses to choose a single identity.
Will the next two-year print look like this one? I do not know, and anyone who claims certainty is selling something. What I do know is this: once a fifty-year habit breaks, even briefly, the burden of proof shifts. Coal must now explain why it should grow again. Clean energy must explain why the pause was not a lucky streak. That is a healthier argument than the one India had when every extra watt defaulted to the same fuel.
The hook that opened this piece still sits with me. Fast-growing countries are supposed to burn more of the old fuel until someone forces a change. This time the change arrived as arithmetic. New electrons showed up in enough volume that the old electrons did not need to multiply. The plants still rise on the horizon. The smoke still exists. But the growth story, for two full years, belonged to something else. That is worth sitting with before the next heat wave tries to rewrite the chart.