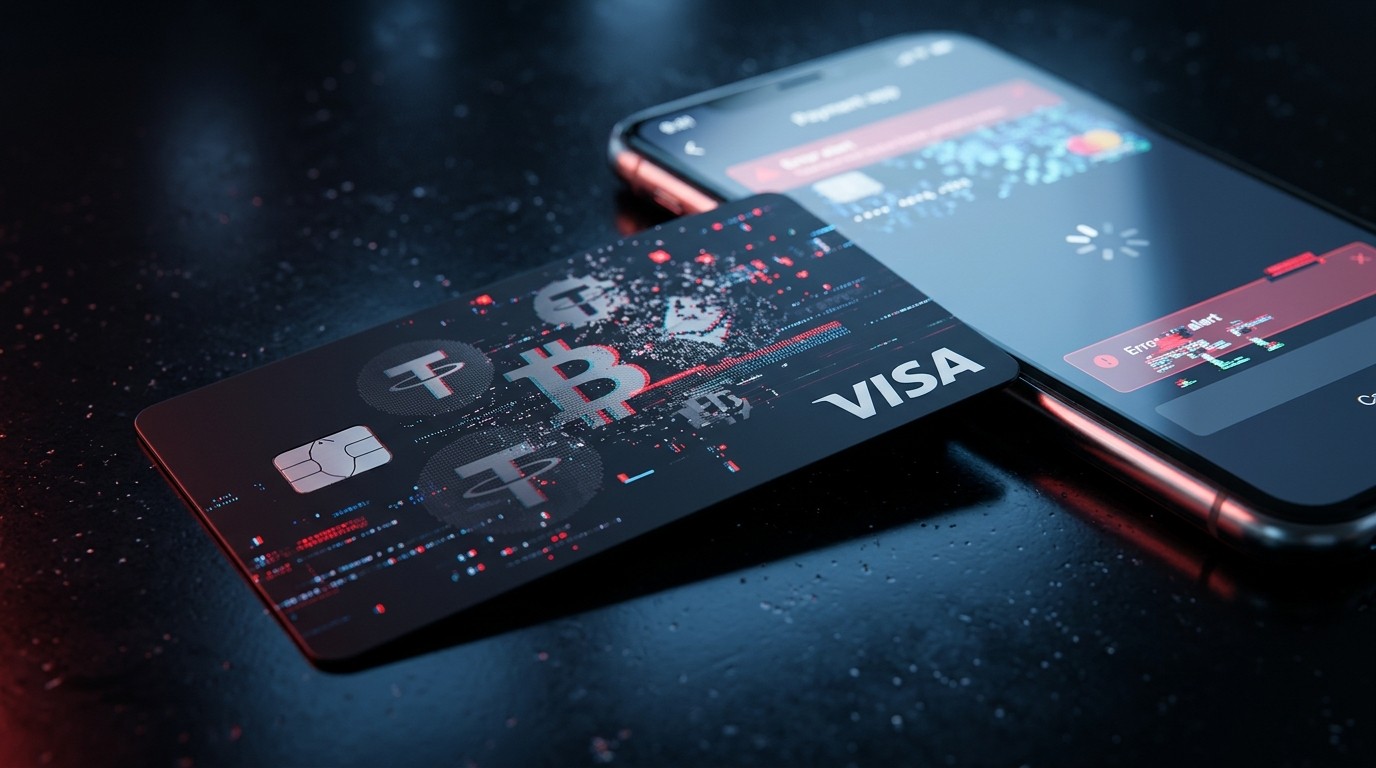

Have you ever signed up for a shiny new crypto card, excited about the cashback and the ease of spending digital assets in everyday life, only to watch the whole thing disappear almost as fast as it arrived? That is exactly what just happened with MEXC’s Global Card. Launched with plenty of fanfare at the end of August, the Visa-linked product is already being shut down. The exchange confirmed the service will stop completely on November 18 at 15:30 UTC. For many users the news landed with a dull thud. One minute you could pay for groceries or online shopping with USDT through Apple Pay or Google Pay. The next, the card is history.
Why MEXC Is Ending Its Visa Crypto Card So Quickly
The official line is straightforward. MEXC says the decision came after its third-party card issuer made service adjustments. Existing cards will stop working for new transactions and new applications are closed. Yet the timing raises eyebrows. The shutdown lands less than two weeks after U.S. authorities moved to restrict the exchange’s access to the American financial system. While the company has not directly linked the two events, the sequence feels hard to ignore.
I have followed these kinds of product launches for a while, and this one always felt ambitious. A virtual Visa card that let people spend stablecoins across more than 180 countries, with cashback ranging from 4 percent to 10 percent and monthly rewards capped at 800 USDT for higher-tier users. No KYC required for the card itself in many regions. It looked like a genuine bridge between crypto wallets and everyday spending. Then, barely three months later, the bridge is being dismantled.
From Temporary Pause to Permanent Closure
The story did not start with a sudden permanent shutdown. On November 14 the exchange first told customers that Global Card payments and deposits would go offline for maintenance until November 18. At the time it still sounded temporary. Users were advised to move remaining balances to their exchange accounts while older transactions continued to settle normally. That four-day window has now become the final chapter.
By Wednesday the language had changed. The service will not resume. The issuer’s adjustments made continued operation impossible, according to the announcement. For cardholders who had set up recurring payments the advice is clear: cancel those subscriptions or switch to another method before the cutoff. Missing the deadline does not leave money stranded, but it does remove control over the timing.
How Remaining Balances Will Be Handled
MEXC has laid out a fairly orderly process for returning funds. Before the November 18 deadline users can still open the Global Card page and withdraw any leftover balance into their Fiat accounts. After that point the exchange will take a snapshot of outstanding card balances on November 21 at exactly 15:30 UTC. That three-day buffer allows pending transactions to clear.
Once the snapshot is taken the corresponding amounts will move automatically into users’ Spot accounts within three business days. No extra request is needed. Refunds from completed purchases will land in Fiat accounts once the exchange receives them. Outstanding cashback rewards continue on their original schedules. Elite VVIP members who qualify for zero-fee benefits will see those reimbursements credited to Spot accounts before December 15.
Transaction histories, order records and cashback details will stay available for three months after closure. After that window closes the data disappears from user dashboards. Anyone who needs statements for taxes or personal records should download them sooner rather than later. In my view this part of the process looks reasonably user-friendly, especially compared with some past exchange product sunsets that left people guessing for weeks.
The Larger Regulatory Shadow Hanging Over the Exchange
While the card issuer’s changes are the stated reason, the broader context cannot be ignored. Earlier this month U.S. authorities identified the exchange as a foreign financial institution of primary money laundering concern linked to Russian illicit finance. The formal order, published in the Federal Register, takes effect on December 10. It restricts certain transfers involving the platform and its affiliates through covered U.S. financial institutions.
According to the findings, the exchange processed roughly 16.7 billion dollars in transactions connected to illicit activities between May 2021 and May 2026. The allegations cover sanctions evasion and cybercrime involving actors from Russia, Iran and North Korea. Importantly, the order does not freeze customer assets worldwide or ban trading on the platform itself. It does, however, create serious friction for any service that touches the traditional banking rails.
Other major exchanges reacted quickly. One large platform blocked withdrawals directed to MEXC accounts and began subjecting incoming deposits linked to the exchange to extra compliance checks. Another exchange’s chief executive publicly advised users against sending funds directly from MEXC, citing the risk of further investigations. These moves happened even at platforms with limited U.S. exposure, which some observers found surprising.
We are ready to fully cooperate.
– Exchange chief executive
The exchange itself has said it is reviewing its anti-money laundering and sanctions compliance procedures with legal advisers. Its chief executive stated that contact had already been established with the U.S. agency through American law firms and that a written request had been acknowledged. Core services such as deposits, withdrawals and trading continue to operate normally for now.
What the Card Offered While It Lasted
It is worth remembering what users actually received during the short life of the product. The virtual Visa card allowed spending of Tether’s USDT through standard payment networks. Apple Pay and Google Pay integration made it feel almost like a regular debit card in more than 180 countries. Cashback rates started at 4 percent and climbed as high as 10 percent depending on the user’s status, with a monthly ceiling of 800 USDT for the highest tier.
Applications were already blocked for U.S. residents under the exchange’s regional rules. For everyone else the proposition was simple: keep funds in crypto, spend them almost anywhere cards are accepted, and earn rewards along the way. In a market where many crypto cards come with high fees or limited merchant acceptance, this one looked competitive. That is partly why the abrupt end feels jarring.
Perhaps the most interesting aspect is how quickly the product moved from launch to closure. Three months is barely enough time for users to form habits around a new payment method. Many people who applied probably never even received physical cards if any were planned, or had only just begun testing the virtual version. The experiment was short-lived by any measure.
Practical Steps Cardholders Should Take Right Now
If you still hold funds on the card, the clock is ticking. The cleanest path is to withdraw the balance into your Fiat account before the November 18 cutoff. After that date the automatic snapshot and transfer to Spot will still protect the value, but you lose the ability to choose the exact timing and destination.
- Open the Global Card section inside the exchange app or website and initiate a full withdrawal of any remaining balance.
- Cancel or update any recurring payments that currently rely on the card so you avoid failed charges later.
- Download transaction histories and cashback records while they remain accessible.
- Watch for the automatic credit to your Spot account after the November 21 snapshot.
- Keep an eye on any pending refunds that may still arrive in your Fiat wallet.
These steps are straightforward, yet people sometimes overlook the small details when announcements arrive mid-week. Taking care of them early removes one more source of stress.
Broader Questions About Crypto Payment Products
This episode highlights a recurring tension in the industry. Crypto exchanges keep launching cards and payment tools that promise seamless spending of digital assets. At the same time, the traditional financial system and regulators continue to scrutinize the flows that pass through those products. When pressure rises, the card is often one of the first features to disappear because it sits closest to the banking rails.
I have seen similar stories play out before. A new card launches with attractive rewards. Adoption grows. Then a compliance issue or banking partner decision forces a quiet or not-so-quiet retreat. Users are left transferring balances and looking for alternatives. The cycle repeats because the demand for convenient crypto spending remains real.
Is the 16.7 billion dollar figure cited by authorities accurate in every detail? Some independent researchers have publicly questioned whether the number might be overstated relative to the exchange’s overall volume. They also ask why other platforms with comparable historical practices have not faced identical restrictions. Those questions will likely linger long after the card itself is gone.
For everyday users the practical takeaway is simpler. Any product that relies on third-party card issuers and traditional payment networks carries an extra layer of risk. Regulatory developments on one side of the world can cascade into service changes almost overnight. Diversifying how you hold and spend crypto remains one of the few reliable defenses.
What Happens to Trading and Core Services
Importantly, the card shutdown does not equal a full platform shutdown. Trading pairs, deposits and withdrawals of cryptocurrencies continue to function. The exchange has been careful to emphasize that point. The restriction targets specific transfer types involving U.S. financial institutions rather than imposing a global freeze. Still, the atmosphere around the platform has clearly changed.
Other exchanges have already tightened their own policies regarding transfers to and from the platform. That creates a kind of secondary effect. Even if you can still trade inside the exchange, moving value in or out may become slower or more complicated. Liquidity and convenience can suffer long before any formal trading ban appears.
In my experience, these periods of elevated scrutiny often last longer than the initial news cycle suggests. Compliance reviews take time. Banking partners reassess relationships. Users gradually adjust their habits. The card’s disappearance is simply the most visible early consequence.
Lessons for Anyone Using Exchange-Branded Cards
If there is a broader lesson here, it is about concentration risk. Keeping large balances on any single exchange product, whether a card, earn account or trading wallet, always carries platform-specific risk. Regulatory actions, technical issues or business decisions by partners can all interrupt access. Spreading activity across a few different venues and self-custody options remains prudent.
Cashback rates that look generous on day one can disappear just as quickly when the underlying partnership changes. The 4 to 10 percent rewards sounded excellent while they lasted. Now they serve as a reminder that promotional terms are not permanent. Treat them as temporary bonuses rather than a reliable income stream.
Finally, the speed of this particular shutdown underlines how quickly the environment can shift. Three months from launch to closure is unusually short even by crypto standards. Anyone evaluating similar products in the future might reasonably ask harder questions about the durability of the banking and card-issuing relationships behind them.
Looking Ahead After the November Cutoff
Once the service officially ends on November 18 and the balance snapshot is taken on the 21st, attention will turn to how smoothly the automatic transfers occur. Most users should see funds appear in Spot accounts without further action. Any delays or discrepancies will need prompt support tickets. Keeping screenshots of the final card balances before the cutoff is a sensible precaution.
The larger regulatory process will continue into December and beyond. The formal restrictions take effect on the 10th of that month. How other market participants, banks and competing exchanges respond in the following weeks will shape the practical impact more than the card closure itself. For now the exchange continues to operate its core markets while engaging with authorities through legal channels.
Crypto payment products are not disappearing as a category. Demand for ways to spend digital assets in the real world remains strong. What this episode does show is that the path from idea to durable product still runs through traditional finance partners and regulatory gatekeepers. When those relationships come under pressure, the consumer-facing feature is often the first to go.
For the users who adopted the MEXC Global Card, the next few days are about practical cleanup. Withdraw what you can, cancel what you must, and download the records you may need later. The experiment was brief. The lessons about counterparty and regulatory risk will probably last longer.
In the end, the story is less about one card and more about the fragile bridges still being built between crypto and everyday money. Those bridges can be exciting while they stand. They can also be dismantled with surprising speed when the foundations are questioned. Paying attention to both the rewards and the structural risks remains the only realistic approach for anyone who wants to use these tools.
The coming weeks will reveal whether the automatic balance transfers proceed cleanly and whether further service adjustments appear. Until then, cardholders have a clear, short checklist and a firm deadline. Handling those steps promptly is the best way to close this particular chapter without unnecessary friction.
Crypto markets move fast. Payment products sometimes move even faster, both on the way up and on the way down. This latest example simply makes that reality harder to overlook.