
Have you ever pulled up to a pump, stared at the diesel number, and felt that quiet little jolt in your stomach? I have. Not because I live for commodity charts, but because that price is never just a number. It is freight costs, grocery shelves, farm work, and the weekly budget of people who do not have a spare hour to debate energy policy. This week that jolt got sharper. A large Midwest plant went offline after a power failure, and the region is now staring at a tighter diesel market than most drivers expected to see in September.
Why One Plant Offline Can Shake An Entire Region
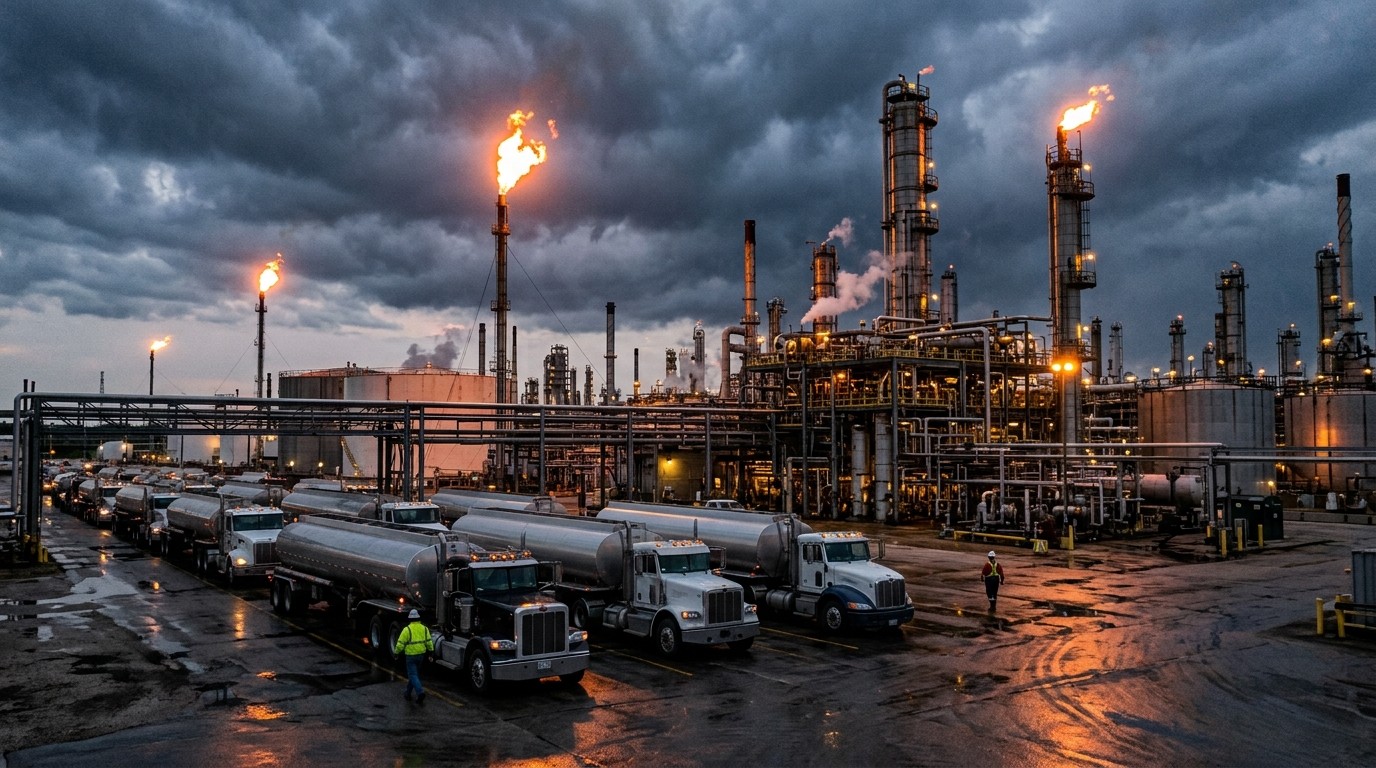
Here is the plain version. A 275,000-barrel-a-day facility southwest of Chicago stopped running after electricity failed and safety systems kicked in. Power later came back. Production did not snap back with it. That gap matters more than the press-release language ever admits. Refineries are not light switches. They are long, hot, carefully balanced machines. When they trip, the restart can take days. Sometimes longer. I have found that markets price the uncertainty faster than plants can recover from it.
The plant in question can turn out around 11 million gallons of gasoline and diesel a day. That is not a rounding error. It is roughly 6% of Midwest refining capacity and about 1.5% of the national total. Lose that for a short stretch and you get local tightness. Lose it for a longer stretch and you get a price story that travels from Illinois into Indiana, Ohio, Wisconsin, and Michigan.
Power restoration is not the same thing as fuel production. That distinction is where the real risk lives.
There is also the messy detail that floodwater overwhelmed a pump at the site. So this was not a single clean event. It was a stack of problems: an outage on primary and secondary utility lines, a safety flare, water where water should not be, and a restart clock that nobody outside the control room can honestly predict.
The Diesel Problem Was Already Sitting There
If this outage had landed in a sleepy market, it would still sting. It did not land in a sleepy market. National pump diesel has already climbed to a record near $6.45 a gallon. Spot diesel around the Great Lakes has been called the highest in the country, with talk of levels near $240 a barrel in wholesale terms. That is the kind of number that makes fleet managers rewrite routes and farmers delay work they cannot really delay.
I keep coming back to a simple point. Gasoline gets the headlines. Diesel does the heavy lifting. Trucks, trains, barges, harvest equipment, construction crews. When diesel jumps, the cost does not stay at the rack. It walks into the price of almost everything else. Perhaps the most interesting aspect is how quickly people forget that after the sticker shock fades.
Industry voices have already flagged a familiar squeeze. When diesel margins look richer than gasoline margins, refiners lean toward diesel. That can leave gasoline thinner than expected even if crude itself is not the main villain. In other words, a diesel crunch can become a gasoline problem by the back door. It is not elegant. It is how the system actually behaves.
What Drivers In The Great Lakes Should Watch
Regional risk is not evenly spread. That is worth saying out loud. One analyst note circulating this week put Ohio at high risk of the sharpest gasoline jump. Wisconsin and Indiana sat in a medium-risk bucket for a moderate move. Michigan and Illinois looked lower to medium, with the uncomfortable caveat that prices could still push past $5 a gallon if the outage drags. Diesel, meanwhile, was expected to rise across most of those states, and not by a polite little tick.
- Ohio faces the clearest chance of a large gasoline spike if product stays tight.
- Wisconsin and Indiana look exposed to a moderate but noticeable jump.
- Michigan and Illinois may see a slower move that still threatens the $5 mark.
- Diesel looks likely to climb in most Great Lakes markets, not just one or two.
Does that mean every station will reprice overnight? No. Retail lags wholesale. Some sites hedge. Some sit on inventory. Some wait and hope the plant comes back before the next delivery cycle. Then a Monday morning arrives and the board changes anyway. Anyone who has watched a regional fuel squeeze knows that rhythm. Quiet first. Then sudden.
A Restart Is Not A Guarantee Of Relief
People like clean endings. Energy markets rarely offer them. Electricity can be restored on Thursday and still leave a unit cold on Friday. Pumps, compressors, heaters, and control logic all have to come back in the right order. A flood-related pump issue adds another layer. If operators find more damage once they walk the units, the calendar slips. I have seen plants look “back” on paper while actual product rates stayed well below nameplate for days.
That is why the capacity figure matters. This site is one of the larger diesel-oriented plants serving the Midwest. Take even part of that slate offline and nearby terminals start drawing harder on remaining barrels. Inventories can look fine in a national table and still feel thin in a single PADD pocket. Geography is stubborn like that.
A prolonged shutdown would tighten regional fuel availability and raise the odds of further price increases across Illinois, Indiana, Ohio, Wisconsin, and Michigan.
There is a comparison some market veterans keep making, and it is not subtle. High diesel can echo the kind of consumer shock people still remember from the 2008 gasoline spike. Different fuel. Same household math. When a working family spends more to commute and more to stock a pantry, the “energy story” stops being abstract.
How A Local Outage Ties Into A Global Crunch
It would be convenient to treat this as a one-plant Midwest tale. It is not. Refining disruptions have been stacking up in more than one region. When several facilities stumble at once, spare capacity shrinks. Traders stop assuming product can be borrowed from the next state over. Freight becomes a bottleneck instead of a solution. That is when a local outage turns into a wider price signal.
Commodity desks have been warning that a global diesel squeeze can pull gasoline with it. If a barrel of crude can be steered toward higher-margin distillate, that is where it goes. Fair enough from a plant-economics standpoint. Less fun if you are buying regular unleaded on the way to a second shift. In my experience, that trade-off is the part public conversation usually skips.
So yes, the Joliet stoppage is a Midwest event. It is also a reminder that product markets are tighter than crude headlines sometimes suggest. Crude can look available while diesel still feels scarce. Those two facts can sit in the same week without contradicting each other.
What This Means For Households And Small Businesses
Let’s get practical. If you drive a diesel pickup, a box truck, or anything that lives on the highway, you already know the pain. If you run a small shop that depends on deliveries, you will feel it even if you never touch a pump yourself. Freight surcharges do not arrive with a press conference. They just show up on invoices.
- Watch wholesale diesel in the Great Lakes, not only the national average.
- Assume retail prices can lag a few days, then move in a cluster.
- Give extra room in delivery schedules if carriers start stretching routes.
- Keep an eye on gasoline as well, because refiners may keep prioritizing diesel.
Is that overcautious? Maybe. I would rather be early than explain a surprise $20 fill-up to someone who budgets in cash. The people most exposed are not traders. They are contractors, farm operators, commuters with long drives, and stores that restock three times a week. Those groups do not get a hedge book. They get a receipt.
A Closer Look At Capacity And Why Six Percent Matters
Six percent does not sound dramatic until you remember how regional product markets work. Fuel does not teleport. Pipelines, barges, and trucks move it, and they move it on a schedule. When one large plant drops out, neighboring units can raise rates only so far. Many were already running hard. There is only so much slack in a system that has spent years consolidating capacity.
Think of it like a crowded highway with one lane closed. Traffic does not politely redistribute. It bunches. The same thing happens with distillate. Terminals nearest the outage feel it first. Then the tightness travels along the usual supply paths. By the time a national average catches up, local drivers have already paid the premium.
| Factor | Why It Matters | Near-Term Risk |
| Plant size | About 275,000 barrels a day | High if offline lasts |
| Product slate | Heavy gasoline and diesel output | High for pump prices |
| Location | Serves Chicago and Great Lakes demand | High regional impact |
| Restart lag | Power back does not equal barrels back | Medium to high |
| Existing diesel strength | Record retail and elevated spot | High price sensitivity |
That table is not a forecast. It is a way to keep the moving parts in one place. The market will still do what markets do. It will overreact, underreact, then settle somewhere uncomfortable in the middle.
The Quiet Role Of Utilities And Weather
It is easy to treat a refinery as an island. It is not. This outage was traced to utility lines feeding the site, both primary and secondary. That should make anyone in industrial planning sit up. Redundancy is supposed to be the whole point of dual feeds. When both go, the plant does not get a polite warning. It trips.
Floodwater at a pump is the other unglamorous piece. Energy infrastructure and water have a long, bad history together. You do not need a hurricane headline for that to matter. A local flood event plus a grid hiccup is enough. I keep thinking about how many facilities look robust until the week they are asked to prove it.
None of this is an argument that operators failed in some cinematic way. Safety flares exist because they are supposed to exist. Shutting down is often the responsible move. The market just does not applaud responsible moves. It reprices them.
Gasoline May Not Get A Free Pass
Diesel is the headline fuel here. Gasoline still sits in the blast radius. If refiners keep chasing distillate margins, gasoline yields can stay constrained even after this plant returns. That is the chain some commodity strategists have been describing. It is also the chain that catches commuters who think they are insulated because they do not buy diesel.
Ohio’s elevated risk of a larger gasoline jump is the clearest example. You can have a diesel-centered outage and still watch unleaded do the damage in a neighboring state. Product flows are not loyal to state lines. They follow pipes, racks, and whatever barrel is left after the last bid.
Will every market clear $5? Nobody serious should pretend to know. The useful question is different. If the restart slips, where does the next incremental barrel come from, and at what delivered cost? That question decides whether this stays a one-week scare or becomes a month-long grind.
What History Suggests When Distillate Gets Tight
Past squeezes tend to follow a pattern. First comes the operational surprise. Then wholesale spikes. Then retail catches up in uneven waves. Then politicians notice. Then the plant comes back, inventories stabilize, and everyone pretends the system was sturdier than it looked. Until the next surprise.
The 2008 comparison is not perfect. The fuel mix was different. The macro backdrop was different. Still, the household feeling rhymes. A working tank of fuel becomes a line item that crowds out other spending. That is when “record diesel” stops being a market phrase and becomes a kitchen-table phrase.
I do not think panic helps. I do think pretending a 275,000-barrel plant is a footnote helps even less. Capacity that concentrated in one corridor should be treated as a live risk, not a trivia fact.
Investors Are Watching More Than The Pump
Equity and commodity desks will read this as a margin story as much as a consumer story. A sudden drop in regional supply can lift crack spreads for plants that keep running. It can also raise questions about reliability, insurance, and the cost of keeping aging units on line. Those are not abstract questions if you follow energy stocks or midstream names tied to product movement.
For broader markets, the transmission channel is inflation psychology. Diesel feeds freight. Freight feeds goods. Goods feed the prices people see on shelves. One outage will not rewrite a national inflation print by itself. A cluster of refining disruptions can still color the mood. Mood matters when rates, growth, and consumer spending are already in the same crowded room.
That is why this sits comfortably in market news rather than in a narrow operations note. The plant is local. The price signal is not.
Practical Questions People Are Already Asking
Should you fill up now? If you are already low and you live in one of the higher-risk states, waiting for a perfect number is a hobby, not a plan. Should fleets pre-buy? Some will. Some cannot. Storage is not free and cash is not infinite. Should anyone expect a quick fade in spot diesel? Only if the restart is clean and nearby plants can cover the hole. That is a lot of ifs.
Rhetorical as it sounds, the better question is how much slack the Midwest really has left. After years of closures and conversions, the region does not look overbuilt. It looks efficient. Efficiency is great until the day you need a spare unit that is no longer there.
What the market is pricing in simple terms:
  Lost barrels today
  Uncertain restart timing
  Already elevated diesel
  Limited nearby spare capacity
Put those four lines together and the price reaction stops looking mysterious. It looks almost obvious. The only debate is how long the first line stays true.
The Human Texture Behind The Barrel Count
I keep picturing a driver in northern Indiana checking a fuel app before sunrise. Not a trader. Just someone who needs to be on a jobsite by seven. That person does not care about nameplate capacity. They care whether Thursday’s price is still there on Friday. A story like this is easy to write in barrels. It is lived in gallons.
Same for a farm operation heading into late-season work. Diesel is not an optional input. You cannot harvest on hope. If rack prices stay elevated, the season’s math changes. That change does not show up in a flare photo. It shows up later in food costs and equipment decisions.
This is the part of energy coverage that still feels underdone to me. We talk about units and outages. We talk less about the people who absorb the first price print and cannot pass it on.
What Would Ease The Pressure
A clean restart would help. Higher runs at neighboring plants would help. Product flowing in from other regions would help, assuming logistics can handle it. A dip in broader distillate demand would help too, though that usually arrives for reasons nobody wants, like slower freight and weaker industry.
- Confirmed return to stable processing rates at the affected site
- Visible rebuild in regional distillate inventories
- Softer wholesale diesel around the Great Lakes
- No additional unplanned refining losses stacked on top
Until those pieces show up, talking about “relief” is mostly hope dressed as analysis. Hope is fine. It should not be the plan.
A Note On Narrative Versus Operations
Social posts moved faster than the plant did. That is normal now. A flare photo travels. A filing about a flooded pump travels. The slower work of bringing units back does not travel as well. If you only follow the first wave, you will think the crisis is either over or apocalyptic. It is usually neither. It is a grind with a price tag.
I would rather stay with the operational facts. The plant went down after a power failure. Electricity was later restored. Fuel production is not automatically restored with it. Regional diesel was already expensive. A long outage would make that worse. Those sentences are enough. They do not need extra theater.
Record diesel is not only a pump story. It is a freight story, a food story, and a household-budget story wearing a fuel-gauge face.
Where This Leaves The Midwest Fuel Picture
The Midwest is not out of fuel. That claim would be sloppy. It is facing a tighter distillate balance at a moment when prices were already high. That combination is enough to keep stations, fleets, and families on edge. If the restart is quick, this becomes a sharp week and a fading footnote. If the restart is messy, the Great Lakes will keep paying for a plant that is not making barrels.
Either way, the episode is a reminder. Modern fuel supply looks abundant until a single large site blinks. Then you see the seams. Then you remember that diesel is the quiet backbone of the real economy. Then you watch the board at the station and do the same math everyone else is doing.
I do not know the exact hour this facility returns to full rate. Neither does anyone posting confident timelines from a phone. What I do know is simpler. Capacity came off at the wrong time, in the wrong region, in a market that had little patience left. Drivers will feel that before the official language catches up. And if the next few days stay quiet on the operations side, the price side probably will not.