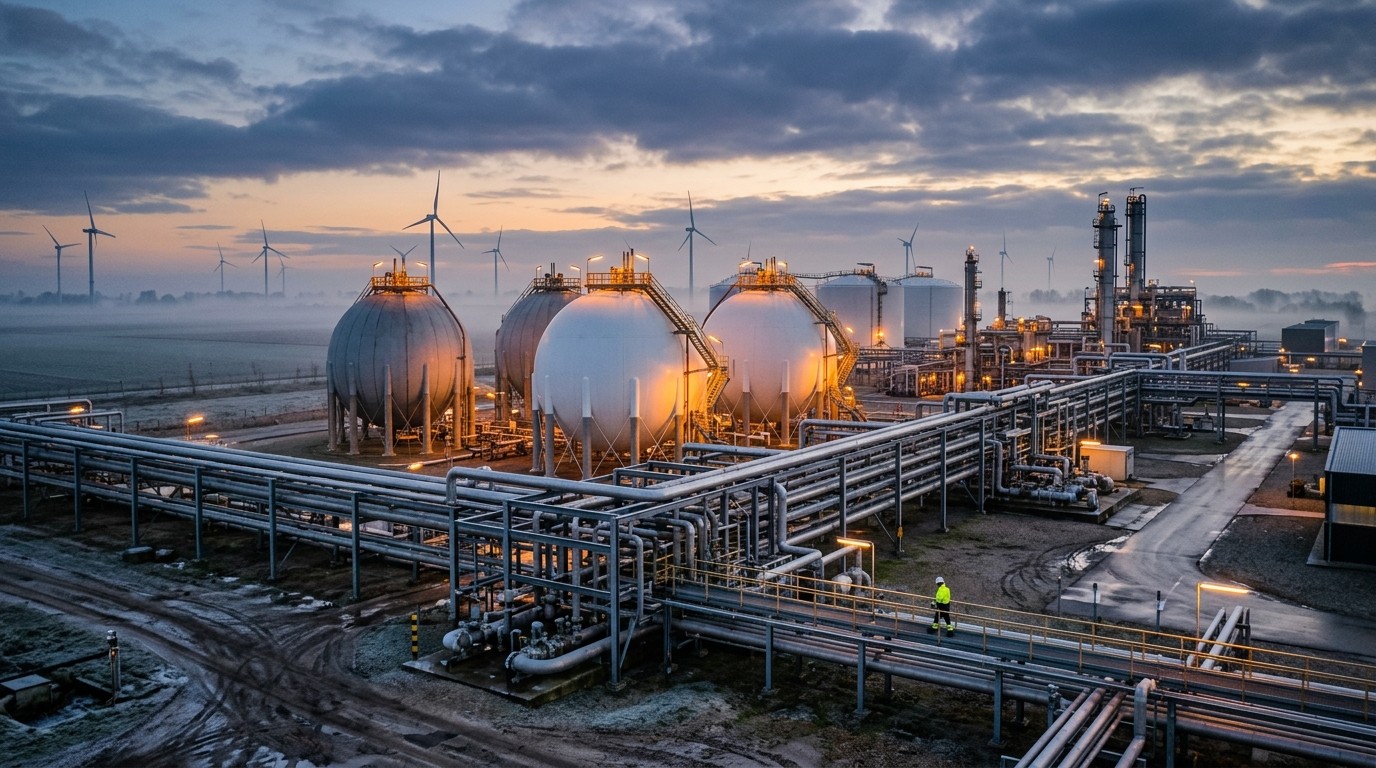

Have you ever watched a government write a check it never wanted to write, then ask why the rule that forced the payment still exists? That is roughly where the Netherlands finds itself after a summer spent stuffing gas into caverns and tanks at a price that would make most finance ministers wince. The bill landed near $1.14 billion, or about one billion euros, and The Hague is no longer whispering about it. Officials now say the European winter storage system is poorly designed, expensive for the wrong people, and increasingly out of step with how gas actually moves.
Why The Dutch Want The Storage Rule Torn Up
I keep coming back to a simple mismatch. The current framework leans on storage capacity more than on how much gas a country actually burns. That sounds tidy in a briefing note. In practice it can push a modest consumer that happens to host a lot of tanks into a much larger financial role than its own households and factories would ever justify.
The Netherlands is not the biggest burner on the continent. It is, however, a major natural gas hub and home to the benchmark futures market that traders across Europe still treat as the reference price. When Brussels sets filling targets by available space rather than by local demand, a hub country can end up carrying inventory that serves a wider system while the invoice sits on a national desk. Climate Minister Stientje van Veldhoven put it bluntly in a letter to parliament: building those inventories should fall mostly on market participants, not on taxpayers who already paid once through higher winter bills.
The task of filling storage should rest mainly with companies that trade and consume the molecule, not with governments forced to meet a continental quota.
– Paraphrased from the Dutch ministerial position
That is not a tantrum. It is an argument about incentives. If the state keeps stepping in every summer, private desks have less reason to hold inventory through the shoulder months. Why lock capital in a cavern when a ministry might do it for you?
A Summer That Made The Rule Look Expensive
This filling season was ugly. Prices jumped after the Iran conflict and after only a trickle of cargoes made it through the Strait of Hormuz. Prompt gas became scarce in the mind of the market even when winter was still months away. That is how you get backwardation: near-term contracts trade above later ones. Holding supply for January looks like a losing trade when October already pays more.
In that structure, a mandate is not a gentle nudge. It is a forced purchase into a rising front month. Governments that treat the target as non-negotiable buy high so that a spreadsheet in Brussels stays green. I find that hard to defend as prudent public finance. You can call it insurance. You can also call it buying inventory at the worst point on the curve because a calendar said you must.
Weeks ago the Dutch network operator already flagged that national sites might miss the official fill level before winter. That was one of the first hard signs that Europe could enter the cold months thinner than planners hoped. Missing a target is not automatically a blackout. It is a warning that the buffer is smaller, the weather option is more expensive, and any late cargo delay bites harder.
Capacity Versus Consumption: The Core Design Flaw
Imagine two neighbors. One uses little heat but owns a huge cellar. The other burns gas all winter and has almost no cellar at all. A rule that says “fill 90 percent of whatever cellar you own” will squeeze the first household and leave the second under-insured unless someone else shares the stock. Scale that up to member states and you see the Dutch complaint.
A consumption-weighted target would still demand a serious buffer. It would just assign the cost closer to the burn. Capacity-weighted targets are easier to audit. Tanks either hold gas or they do not. Demand is messier. It moves with weather, industry, and the luck of a mild November. Regulators like clean metrics. Markets live in the messy ones.
- Capacity rules are simple to measure and hard to game on paper.
- Consumption rules track risk more honestly but need better demand data.
- Hub countries can be asked to store “for Europe” without a clean reimbursement path.
- Traders delay filling when the curve pays them to stay short of inventory.
Perhaps the most interesting aspect is political, not technical. Once a government has spent a billion euros in a single season, the next coalition will ask who benefits. If the answer is “the wider market,” voters will want the wider market to write the next check.
Germany’s Parallel Problem And A Different Tool
Germany holds one of the largest storage complexes on earth, yet recent readings showed sites only about 57 percent full in late September. That is historically low. The national storage association has already warned that a colder-than-average winter could leave the system short. Berlin is not arguing to scrap the European target so much as to scale up an existing market instrument: autumn tenders for long-term options, often called LTOs, that pay traders to stand ready with volume.
That is a different philosophy. Instead of the treasury buying molecules outright, the state buys an option on molecules. If prices behave, the option may never be exercised and the public cost stays smaller. If winter bites, the option pulls gas into the system when it is needed. I prefer that shape of intervention, with one caveat. Options only work if counterparties are solvent and if the product is sized for a real cold snap, not for a mild December that makes everyone look clever.
| Country posture | Storage picture | Preferred lever |
| Netherlands | Hub with costly public fill | Rewrite EU mandate, shift cost to market |
| Germany | Huge capacity, low fill ratio | Expand long-term options tenders |
| Wider EU | Uneven inventories into winter | Keep headline targets for political cover |
Two big economies, two instincts. One wants the rulebook changed. The other wants a bigger market tool inside the existing rulebook. Both are reacting to the same curve: expensive prompt gas and a storage season that did not refill on autopilot.
What Backwardation Really Does To Winter Planning
People outside trading desks treat “backwardation” as jargon. It is not mysterious. If gas for next week is dearer than gas for next March, you are being paid to use supply now and hope later. Storage is the opposite trade. You buy now, park the molecule, and sell it later. When the later price is weaker, the park-and-wait trade loses money before you even count cavern fees.
So traders shrug. Ministries panic. The mandate tries to override the price signal. Sometimes that is the point of a mandate. Sometimes it just means the public sector becomes the buyer of last resort at the worst moment. In my experience, that pattern repeats in commodity policy whenever politics cannot live with a thin buffer and markets will not hold one for free.
Hormuz risk made the signal louder. Fewer cargoes through a chokepoint raise the chance that the next cargo is late. Late cargoes support prompt prices. Prompt strength deepens backwardation. Deep backwardation empties the incentive to store. You can see the loop. Breaking it takes either cheaper prompt supply or a subsidy that makes storage profitable again. The Dutch bill is that subsidy, paid in one lump.
Who Should Carry The Inventory Risk?
There is a respectable case for public involvement. Gas shortages are not a private inconvenience. They shut factories, raise heating bills for people who cannot hedge, and spill into electricity when gas plants set the marginal price. A pure free-market winter can look efficient in July and brutal in January.
There is also a respectable case for making shippers, utilities, and large industrials hold tickets. They earn the margin when they sell heat and power. They can pass some of the carrying cost through regulated tariffs or retail contracts. If they fail to stock, they face imbalance penalties. That is cleaner than a finance ministry wiring money into a storage operator because a European ratio slipped.
- Define the buffer in days of national and regional demand, not only in percent of tanks.
- Assign a minimum stock obligation to licensed suppliers, with tradable tickets.
- Keep a slim strategic reserve for tail-risk weather, financed off-budget if possible.
- Use options tenders before outright state purchases of physical gas.
- Publish the curve impact so voters can see when filling is cheapest.
None of that is glamorous. It is plumbing. Winter policy is mostly plumbing. The drama arrives when the pipes are empty and the speeches begin.
The Hub Problem Nobody Wants To Price Honestly
A hub creates a public good. Liquidity at the Dutch title transfer point lets utilities in other countries hedge. Storage near that point supports the hedge. If the host country pays to keep tanks full so that the index remains credible, the rest of the market free-rides on Dutch fiscal capacity. That is the unspoken line in the ministerial letter.
You can compensate a hub. You can socialize the cost through a European levy. You can let the hub run leaner and accept a jumpy benchmark. What you should not do, if you care about durable rules, is pretend the host is just another average member state. Average member states do not host the contract everyone else marks to market.
A benchmark market without a funded buffer is a benchmark that will gap when the first cold week arrives.
I have found that energy debates often skip this part because it sounds like special pleading. It is not. Financial centers argue the same way about clearing houses and lender-of-last-resort backstops. Infrastructure that others rely on is not free.
Winter Scenarios That Keep Planners Awake
A mild winter would let Europe skate by with thin stores, imported cargoes, and a bit of demand destruction in industry. Prices would stay noisy but manageable. A normal winter would tighten the system in January and February, especially if a few LNG cargoes slip. A hard winter plus another shipping scare would turn storage from a policy talking point into a physical constraint.
Germany’s low fill ratio matters here because German demand still swings the regional balance. Dutch tanks matter because they sit next to the price that funds every hedge. If both are light, neighboring systems cannot casually lean on them. That is when you hear about industrial curtailment, interruptible contracts, and emergency coordination calls that never look good on television.
Is panic useful? Rarely. Is complacency cheaper? Only until the first week of ice. The honest stance is unfashionable: accept that buffers cost money in summer so that rationing costs less in winter, then argue in public about who pays the summer bill.
What A Smarter Mandate Could Look Like
Scrap does not have to mean abandon. The Dutch push is better read as a demand to change the formula. Tie minimums to forecast winter demand bands. Allow banking of over-compliance across years so a cheap summer can fund a tight one. Create a small joint reserve that hub states operate against a fee paid by all off-takers of the benchmark. Let options sit in front of physical state buying.
You could even keep a headline percentage for politics, then add a second test based on days of cover. If tanks are 80 percent full but that only equals twelve days of peak burn, the headline number is a vanity metric. Days of cover is what a cold snap actually eats.
A practical winter test:
  1. Days of peak demand in store
  2. Share of inventory held by commercial players
  3. Cost of the last 10 percent of fill
  4. Option cover versus physical cover
  5. Hub compensation if tanks serve the index
That list will never trend. It would, however, stop ministries from celebrating a ratio that hides an empty risk budget.
Prices, Politics, And The Temptation To Kick The Can
High filling costs arrive at a bad moment for any government. Households already associate gas with last year’s sticker shock. Industry already shops for locations with cheaper power. Spending another billion to meet a Brussels ratio is a gift to the opposition unless you can show that the alternative was worse.
So officials look for a rewrite. That is rational. It is also late. Rules written after a crisis tend to over-insure. Rules rewritten after a costly summer tend to under-insure. The cycle is familiar: scare, stockpile, invoice, revolt, loosen, scare again. Breaking the cycle means admitting that security of supply is a recurring line item, not a one-off hero purchase.
I do not buy the idea that markets will magically hold enough gas if you simply delete the mandate. Not in backwardation. Not after a shipping shock. Not when working capital is expensive. Delete the bad metric, yes. Delete the need for a buffer, no.
What Traders, Utilities, And Households Should Watch
Watch fill rates into October, not speeches. Watch the shape of the curve. If winter months stay cheap versus prompt, commercial storage will lag unless someone pays them to fill. Watch German tenders. If option volumes rise, Berlin is trying to rent flexibility instead of owning gas. Watch Dutch legal and parliamentary language. If The Hague gathers allies, the European text may move before the next filling season.
- Thin inventories raise the chance of sharp January spikes even without a new geopolitical shock.
- A rewrite of capacity-based targets would shift who carries the working-capital burden.
- Hub liquidity can suffer if local tanks run structurally lean.
- Household tariffs may still embed storage costs, only through different channels.
For households the story is simpler than the market microstructure. Someone pays to keep gas underground. If companies pay, it shows up in contracts. If governments pay, it shows up in budgets and eventually in tax or debt. There is no free cavern.
A Blunt View After The Billion-Euro Summer
The Dutch complaint is easy to caricature as a rich hub wriggling out of solidarity. Read it more carefully and it is a warning about metric design. Measure the wrong thing and you spend real money on the appearance of safety. Measure days of cover, assign obligations to the firms that sell the molecule, and keep a narrow public backstop for the tail, and you still have a policy. You just stop pretending that a tank-percentage is the same as a winter plan.
Will Brussels move fast? Unlikely. Winter rules are hard to reopen when winter is already on the calendar. That does not make the Dutch letter idle noise. It puts a price tag on a quiet assumption: that member states will keep buying whatever the filling season demands. After a $1.14 billion season, that assumption looks expensive. After a cold February, a thin store would look expensive too. The only open question is which invoice Europe would rather face, and who is holding the pen when it arrives.
If you trade the complex, you already know the next few weeks matter more than the next few communiqués. If you just pay a heating bill, you will feel the outcome either as a spike or as a quieter surcharge that never makes the front page. Either way, the storage fight is no longer a technical annex. It is a bill, a curve, and a winter that has not yet shown its hand.