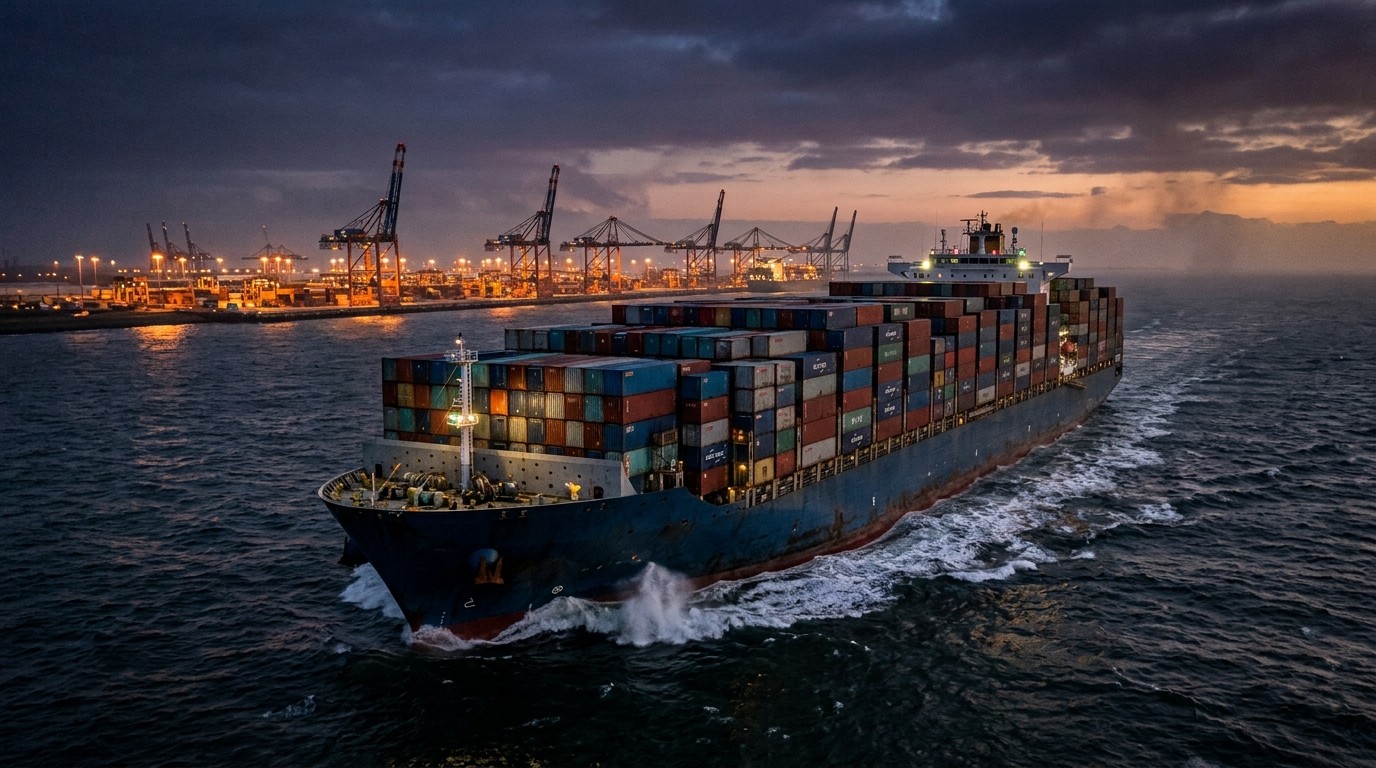

Have you noticed how a crate that used to feel like background noise in the global economy suddenly matters again? I have. A few years ago, most of us treated ocean shipping as plumbing. Invisible. Boring. Then the pipes clogged, prices leapt, shelves went thin, and everyone learned the hard way that a box on a ship can move inflation as surely as a central-bank meeting. That lesson is back on the table.
Why Ocean Freight Costs Are Climbing So Fast Again
Container rates have jumped on the order of 201 percent, close enough to the roughly 250 percent spike that defined the 2021 box shortage that people who lived through that mess are sitting up. I do not like alarm for its own sake. Still, the shape of this move is familiar. Tight vessel supply. Demand lighting up in more than one basin at once. Fuel that refuses to behave. Put those together and you get what shipping desks keep calling a perfect storm.
Most annual contracts get locked in spring. That used to feel like a comfort. It is less comforting if you sit on the spot market, or if you are already planning 2027. A shock that lasts through fall and winter does not stay a quarterly nuisance. It walks into the next contracting round and sits down.
Most contracts are set in the spring, but this move is a live headwind for anyone on spot rates and a possible problem for 2027.
– Retail market note circulating among traders
The Container Shock Looks Too Much Like 2021
During the last big squeeze, ships were out of position, ports were jammed, and every retailer chased the same scarce boxes. Prices did what scarce things do. They exploded. The current jump is not a carbon copy. Capacity is not identically broken. Labor is not identically frozen. Yet the percentage move is close enough that finance teams are running the same sensitivity tables they swore they would never need again.
In my experience, the market always wants a single villain. A canal. A drought. A strike. Reality is messier. Vessel supply has tightened. Demand has firmed on more than one trade lane at the same time. When both basins heat up together, empty containers do not magically teleport. Ships burn days they do not have. Rates follow.
Perhaps the most interesting aspect is how quickly memory fades. After the last crisis, boards promised dual sourcing, extra inventory, and “resilience.” Some of that happened. A lot of it quietly unwound when freight got cheap again. Cheap freight is a narcotic. Companies go back to lean inventories because lean inventories look great on a quarterly slide. Then the ocean reminds them who actually sets the tempo.
Dry Bulk Is Joining The Party
This is not only a container story. The index that tracks several dry-bulk classes — including Capesize, Panamax, and Supramax tonnage — has pushed back toward late-2023 highs. That matters because dry bulk moves the unglamorous stuff: iron ore, coal, grain. When those rates jump, industrial costs move even if your online cart never shows a twenty-foot box.
Analysts describing the surge keep returning to the same phrase. Supply of ships is tight. Demand is firing in both basins at once. I have found that when dry bulk and containers rise together, the inflation conversation changes. One market can be dismissed as a niche. Two markets rising at once start to look like a system under strain.
Diesel Is The Quiet Amplifier
Ocean rates get the headlines. Diesel finishes the job. National average pump prices near $6.50 a gallon are brutal for truckers. Highway rates rise because they have to. A container that lands expensive still has to move inland. That last mile is not a rounding error. It is often the difference between a thin margin and a loss.
I keep coming back to a simple picture. A retailer can hedge some ocean exposure. Hedging every diesel mile on every highway is another matter. Elevated diesel plus elevated ocean freight is a stack, not a coincidence. If that stack holds through winter, the pass-through argument gets louder in every pricing meeting.
- Ocean container rates up on the order of two hundred percent from recent lows
- Dry-bulk benchmarks back near December 2023 levels
- Highway diesel near levels that crush independent trucking margins
- Spot users already feeling the pinch while annual contracts still look “fine” on paper
- 2027 contract talks now sitting in the background like a second deadline
How A Shipping Squeeze Turns Into Inflation
Freight is a cost. Costs look for a home. Sometimes they land in margins. Sometimes they land on the shelf. Sometimes they do both, in sequence. First the importer absorbs. Then the wholesaler absorbs a little less. Then the brand tests a smaller pack or a quieter price increase. Consumers feel it last and blame the nearest villain.
Does every freight spike become a consumer-price spike? No. Inventories, demand destruction, and currency moves can interrupt the chain. But a prolonged shock into the holiday build and the winter restock is a different animal. It arrives when warehouses are supposed to be filling, not emptying. That timing is what makes people nervous.
I’ve found that inflation debates get theological far too fast. One camp says shipping cannot matter because goods are only a slice of the consumer basket. Another camp says shipping is destiny. Both overplay the hand. Freight is not destiny. It is a lever. Pull it hard enough, long enough, and other prices start to lean.
A freight shock that lasts into the next contracting cycle forces businesses to choose between thinner profits and higher prices for customers.
Spot Rates Versus The Spring Contract Ritual
Here is the unsexy part that actually decides who gets hurt. Plenty of cargo still moves under annual deals struck when the water looked calmer. Those shippers can sound almost smug in September. Spot shippers cannot. They pay the market that exists today, not the market that existed in April.
That split creates a false sense of safety in some boardrooms. “Our contract is fine.” Fine until volume overflows the contracted allotment. Fine until a delayed sailing forces a last-minute booking. Fine until next spring, when the other side of the table remembers every painful week of the winter.
If the surge is still standing when calendars flip, 2027 rates will not be negotiated in a vacuum. They will be negotiated with this winter sitting on the table like an unpaid bill.
What “Both Basins At Once” Really Means
Shipping people talk in basins the way weather people talk in fronts. East and west. Atlantic and Pacific. When one side is hot and the other is quiet, fleets can rebalance. Ships ballast toward the money. Empties find a path home. When both sides heat together, that relief valve sticks.
Think of it as a two-lane highway where both directions suddenly fill with trucks. You cannot “borrow” capacity from the empty lane because there is no empty lane. That is the operational core of the current squeeze. Not a mystery. Just physics plus schedules plus fuel.
Is it permanent? Almost certainly not. Freight markets overshoot in both directions. They did after the pandemic peak. They will again. The question that actually pays the bills is duration. A six-week spike is a headache. A six-month spike is a planning problem. A spike that writes itself into the next annual round is a strategy problem.
Corporate Margins Are The First Shock Absorber
Before consumers see a new sticker, finance teams eat the difference. That works until it does not. Companies that rebuilt pricing power after the last inflation wave may try again. Companies that already stretched customers may swallow more pain and cut elsewhere. Headcount. Promotions. Capex. Freight has a way of showing up in rooms that have nothing to do with ports.
Retail is the obvious pressure point. Apparel, home goods, electronics, toys ahead of the holidays. But the dry-bulk move widens the circle. Construction inputs. Energy commodities. Agricultural bulk. The map is larger than a shopping cart.
| Channel | What Is Moving | Who Feels It First |
| Container ocean | Finished goods and parts | Importers and retailers on spot |
| Dry bulk | Ore, coal, grain, bulk inputs | Heavy industry and commodity traders |
| Highway diesel | Inland delivery after the port | Truckers, then shippers, then shelves |
| Annual contracts | Next-year locked rates | Anyone negotiating 2027 coverage |
Growth Risk If The Squeeze Sticks
Higher transport costs do not automatically kill growth. They can, though, if they arrive alongside weak demand. That combination is the ugly one. Firms raise prices into a tired consumer and volumes slip. Or they refuse to raise prices and margins slip. Either path can slow hiring and investment. That is how a shipping story becomes a macro story.
I am not in the business of predicting recessions from a freight index. That game has humbled smarter people than me. I am in the business of noticing when several stress lines point the same way. Ocean rates. Dry bulk. Diesel. Contract timing. That cluster deserves attention even if the landing is soft.
Lessons Companies Thought They Already Learned
After the last crisis, the language of supply-chain presentations changed overnight. Resilience. Nearshoring. Safety stock. Multi-port strategies. Some of it was real. Some of it was theater. When rates collapsed, theater won a lot of budget fights. Inventory is expensive. Extra suppliers are messy. A cheap sailing is seductive.
Now the pendulum is swinging again, and the firms that kept a little slack look less foolish. Dual booking windows. Mix of contract and spot. Earlier holiday inbound. Those are not glamorous tactics. They are the difference between a controllable cost and a scramble.
- Map how much volume still sits on spot rather than locked contracts.
- Stress-test landed cost if ocean rates stay elevated through winter.
- Add diesel as a separate line, not a footnote under “freight.”
- Decide now whether 2027 talks should start from a defensive posture.
- Watch dry bulk even if you never charter a Capesize in your life.
Why Winter Timing Makes This Different
Summer spikes can fade with the season. Fall and winter spikes collide with inventory builds, weather delays, and holiday calendars. A ship that misses a window in November does not get a gentle do-over. It gets air freight fantasies and unhappy merchants.
Weather is the uninvited guest. Storms, port closures, canal drafts, icing in places people forget about until a schedule blows up. A tight vessel market has no spare days for weather. That is how a rate story becomes a reliability story, and reliability stories are what empty a shelf.
In my view, the market is underpricing that calendar risk. Not because people are foolish. Because the last cheap-freight years trained everyone to treat delays as exceptions. Exceptions are easier to ignore until they stop being exceptions.
Consumers Will Not See The Ship. They Will See The Ticket.
Nobody walks into a store thinking about TEUs. They see a toaster that costs more, a sweater that shrank in the wash of “shrinkflation,” a delivery fee that appeared out of nowhere. The transmission is delayed and messy. That delay is why debates get loud. By the time the shelf moves, the freight spike may already be old news on a trading screen.
That lag is politically useful and economically dangerous. Useful because officials can say goods inflation is contained while the pipeline is still filling. Dangerous because the pipeline does fill. If this shock persists, the argument will not stay inside logistics Slack channels.
A Note On Comparisons People Love To Overuse
Is this “another pandemic”? No. Ports are not in the same kind of paralysis. Consumer demand is not the same sugar-high of stimulus checks and locked-down spending. Comparing every spike to 2021 is lazy. Comparing the percentage move is not lazy. It is a warning light. Warning lights are allowed to flash without meaning the engine has already seized.
The Red Sea rerouting chapter taught a similar lesson. Distances grew. Ton-miles grew. Capacity that looked adequate on a map looked tight on a clock. When ships take the long way, the world has fewer effective ships. You do not need a new crisis label for that arithmetic to bite.
What I Watch From Here
Three things, mostly. Whether container rates keep pressing after the first wave of panic bookings. Whether dry bulk holds those late-2023-style levels instead of fading. Whether diesel stays ugly enough to keep inland rates firm. If two of those three stay hot into the deep fall, the 2027 conversation changes tone.
I also watch behavior. Are importers pulling cargo forward? Are they accepting blank sailings as normal? Are retailers talking inventory again in earnings language, or only in private? Behavior is the tell. Indexes are the scoreboard.
Simple landed-cost sketch:
  Product cost
+ Ocean freight (contract or spot)
+ Inland diesel miles
+ Delay buffers and rolled bookings
= Price pressure that has to live somewhere
The Human Side Of An Abstract Market
It is easy to talk in indexes and forget the people. Truckers running thinner after a fuel fill. Warehouse crews facing bunched arrivals after a delayed string of vessels. Small importers who cannot average costs across a global network because they do not have a global network. Those stories do not show up in a Baltic print. They show up in missed payrolls and quiet shutdowns.
That is why I get impatient with the idea that freight is “just logistics.” Logistics is how real life arrives. Food, parts, medicine, clothes, the unremarkable objects that make a week work. When the ocean gets expensive, ordinary life gets a little more expensive, a little more brittle, a little more delayed.
Could This Fade As Fast As It Arrived?
Yes. Freight markets are famous for whiplash. New deliveries of ships. A sudden dip in retail restocking. A reroute that unwinds. Any of those can knock the pins out. Betting the ranch on a permanent high-rate regime is how people get caught the other way.
The smarter posture is unfashionable. Assume the spike can persist long enough to matter, and assume it can vanish fast enough to punish the people who only planned for persistence. Two-sided risk. Adults can hold both thoughts.
The current surge looks like a perfect storm: vessel supply tightening while demand fires in more than one basin at the same time.
– Shipping market analysts
Practical Takeaways Without The Theater
If you buy goods that cross an ocean, stop treating freight as a fixed line in last year’s budget. Revisit the mix of contract and spot. Ask how much of peak season is still uncovered. Put diesel next to ocean on the same page. And if you set prices once a year, ask whether that calendar still matches a market that can jump two hundred percent between meetings.
If you invest, look past the shipping names alone. Retail margins. Industrial input costs. Anyone who promised “stable logistics” on a slide. Freight is a tell for the real economy when it stops being quiet.
If you just live here, you do not need a new hobby in container indices. You might want a little more patience with restocks and a little more skepticism when every increase gets blamed on a single convenient story. The ocean is back in the plot. It usually is, right before people remember it exists.
The Uncomfortable Bottom Line
A worsening ocean freight shock is not automatically a replay of the last crisis. It is close enough in scale, and messy enough in timing, to revive the same fears: supply-chain friction, margin compression, and another push on consumer prices if diesel stays elevated. The people on spot already know. The people on spring contracts will know later. The 2027 round will remember either way.
I keep a simple rule for stories like this. When shipping is cheap, nobody wants to talk about shipping. When shipping is expensive, everybody wants a simple explanation. There is no simple explanation. There is a tight fleet, busy basins, costly fuel, and a calendar that does not care about anyone’s forecast. That combination has wrecked tidy plans before. It can do it again. Not as fate. As arithmetic.
Watch the next few months. Not because panic is a strategy. Because winter will tell us whether this was a loud squall or the opening of a longer, more expensive season. And if you still think a box on a ship is boring, fair enough. Boring things have a habit of setting the price of everything else.