
Have you ever watched a market drop on “good news” and still felt uneasy? That is the mood around oil prices right now. After hours of talks between U.S. officials and an Iranian delegation on the sidelines of a United Nations gathering, crude slipped. Traders treated the meeting as a sign that the worst supply scare might ease. I keep coming back to a simpler thought. Diplomacy can cool a headline in a single evening. It rarely removes the geography underneath the headline.
Why Oil Prices Moved After The Un Meeting
Futures for the international benchmark, Brent crude for November delivery, were last indicated near $98.51 a barrel, down about three quarters of a percent. U.S. West Texas Intermediate for the same month sat near $89.59, off a little more than one percent. Those are not collapse numbers. They are relief numbers. Markets had already given back a large chunk of the recent spike. Over five sessions, the complex had dropped close to twelve percent after testing the psychologically loud zone above $100.
That zone matters more than the decimal points. When crude lives above one hundred dollars, politicians notice, drivers notice, and central bankers start doing quiet math. Peace-building language tends to appear right there. I have found that energy markets treat $100 less like a fair value and more like a fire alarm. Once the alarm rings, every rumor of talks gets a bid in bonds and a haircut in oil.
Over the past five consecutive sessions, the price has fallen by almost 12%, retreating once again from the intervention zone above $100.
– Market commentary circulating among energy desks
President Donald Trump described the session as a “very good meeting” that lasted about three hours. Earlier, in remarks to the world body, he framed a stark choice: reach a deal with Tehran or “annihilate” the country. That pairing of words is not subtle. Markets heard both the threat and the meeting. The meeting won the tape, at least for a day.
What Traders Actually Heard In The Room
They did not hear a signed accord. They heard duration. Three hours is long enough to suggest the two sides sat through more than a photo line. In oil, process can be priced before paper. If officials keep talking, the chance of an immediate closure of a key waterway looks smaller. That is the trade.
Pakistan’s reported mediation with Tehran added another soft layer. When a regional actor tries to keep channels open, desks mark down the probability of a sudden regional chain reaction. Nobody should confuse that with a settlement. It is a change in the odds, not a change in the map.
Perhaps the most interesting aspect is how quickly the market used the meeting as permission to sell strength. That tells you positioning was already crowded on the bullish side of geopolitics. When a crowd is long “fear,” even a polite communique can trigger covering.
The Strait Still Sits In The Story
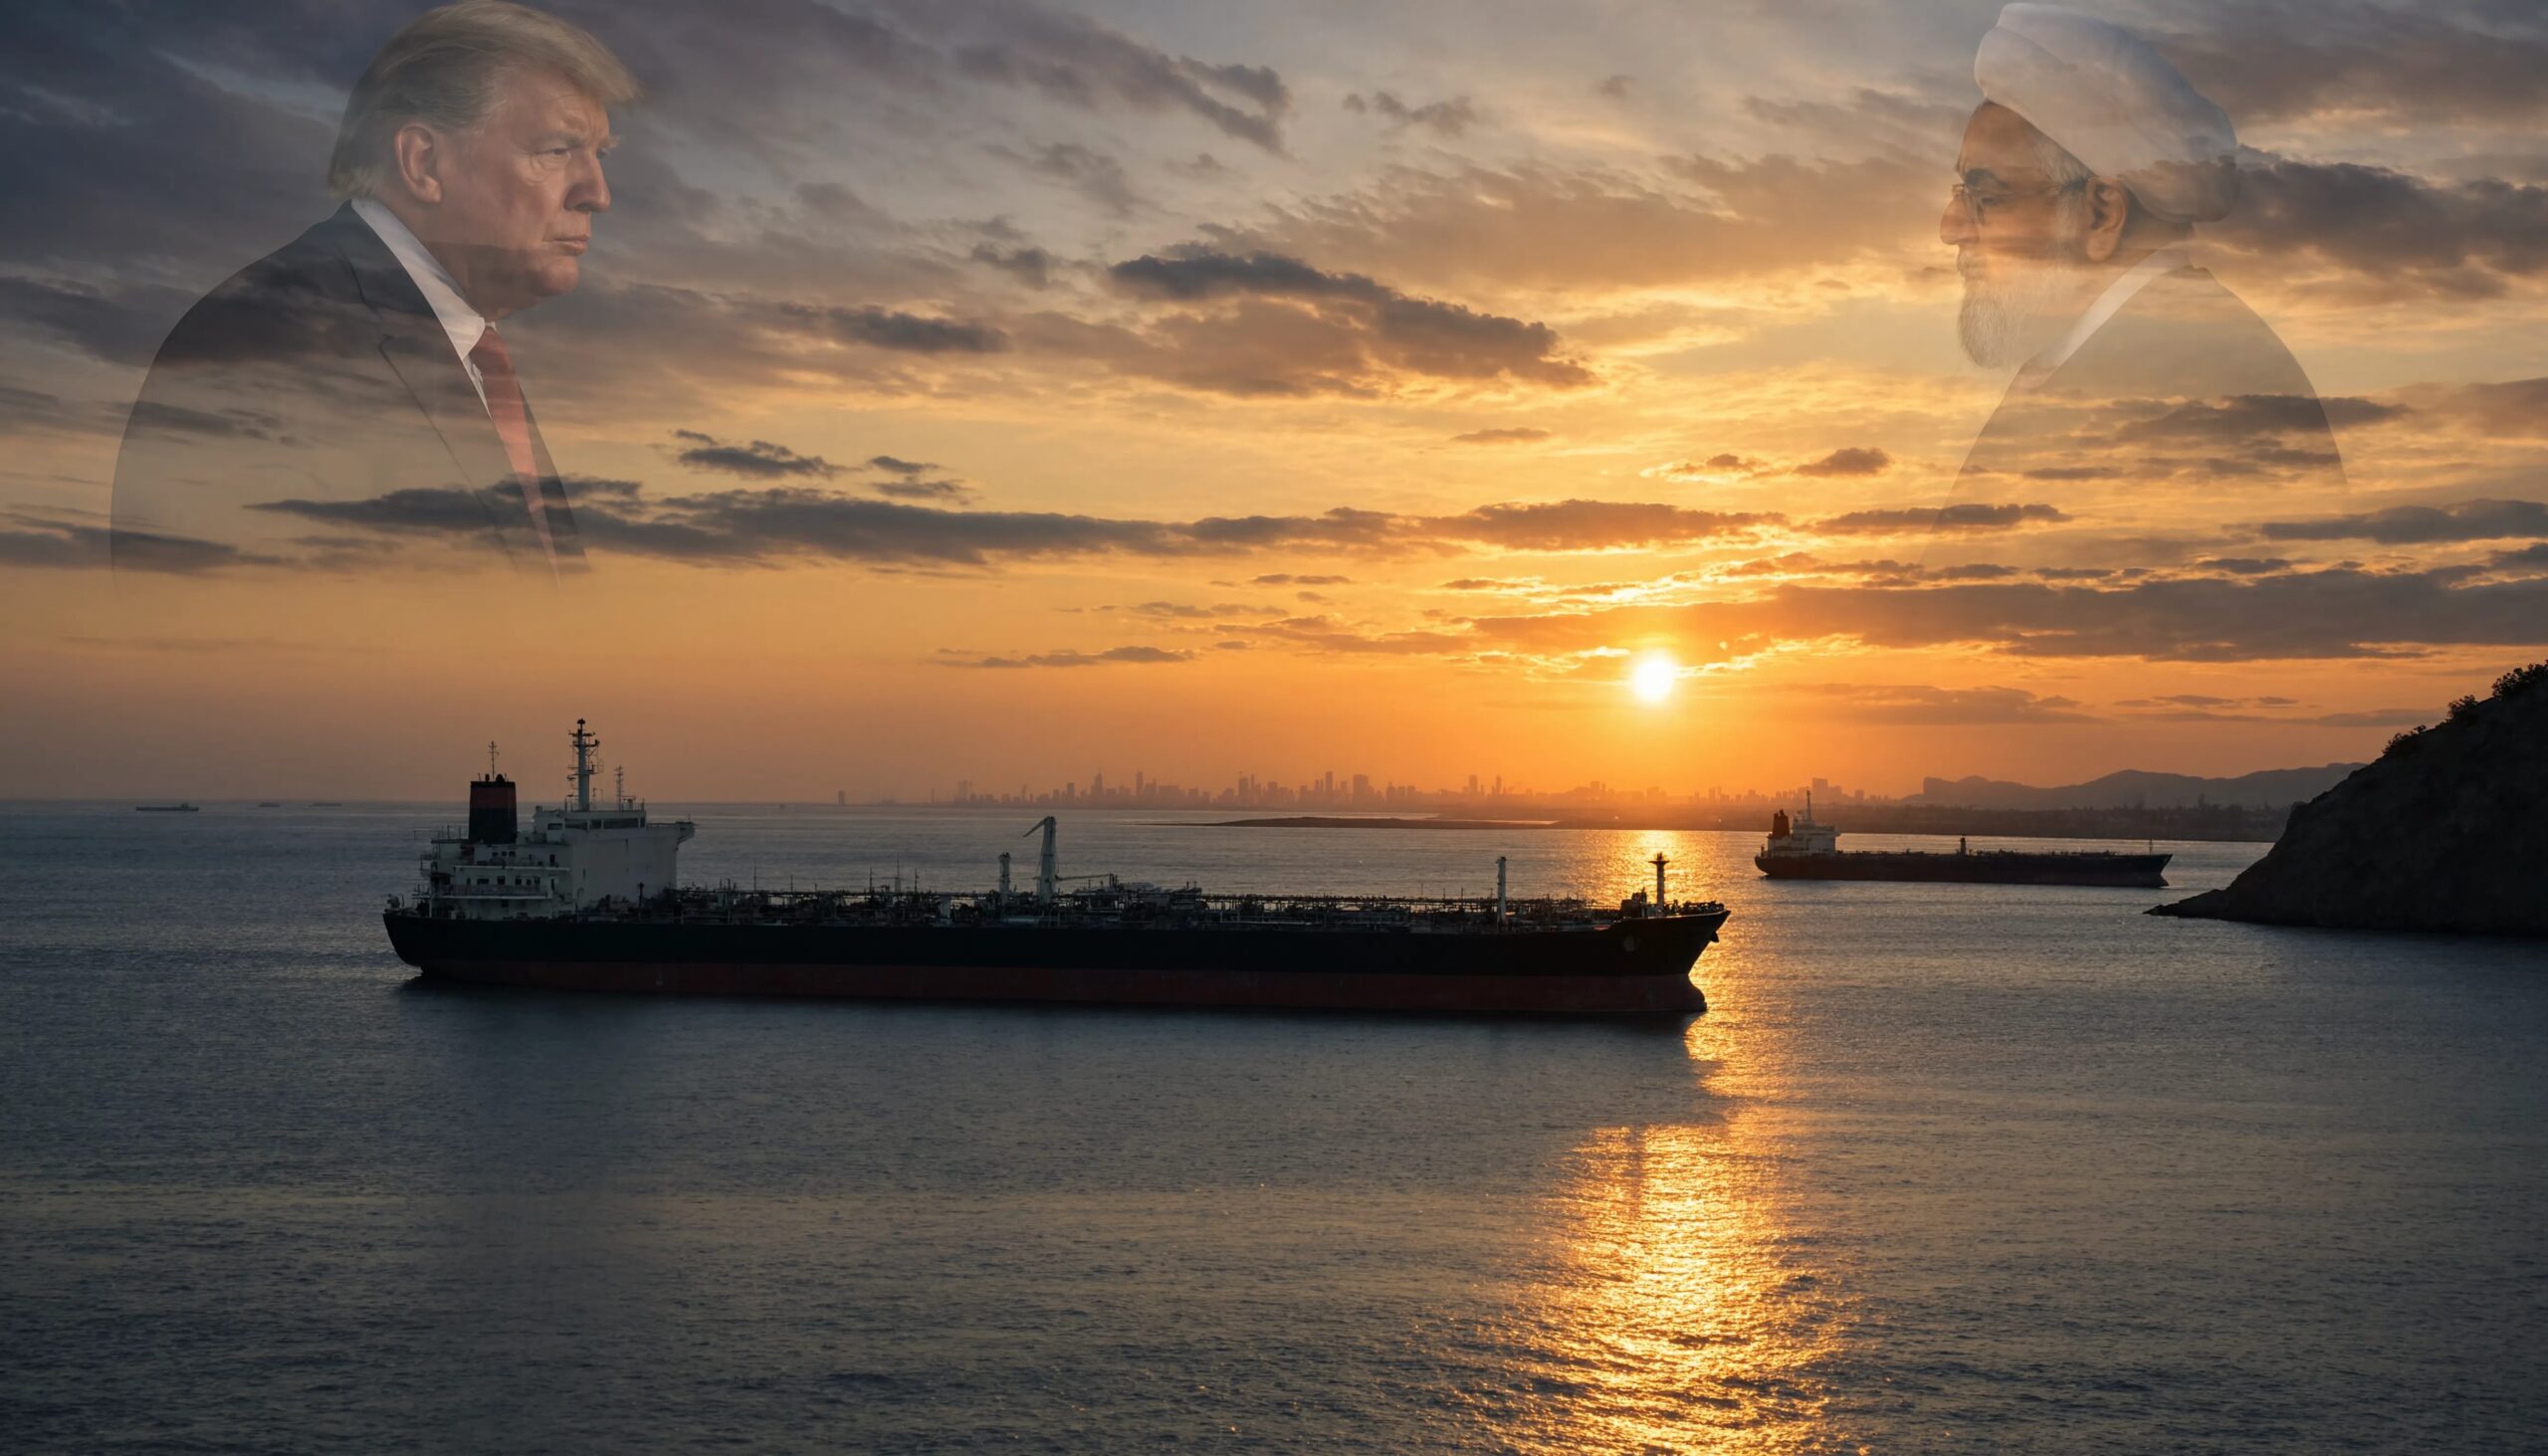
Look at the pictures out of the Strait of Hormuz. Merchant ships linked to Iran and to other flags have been sitting at anchor near Bandar Abbas. That image is not a metaphor. It is inventory in waiting, insurance in waiting, and a reminder that a narrow stretch of water still carries a shocking share of seaborne crude.
I keep a simple rule on my desk. If tankers linger, the market is not done with risk. Anchored ships can mean caution, congestion, or both. Either way, physical barrels are telling a slower story than the futures screen.
- Paper crude can drop on a diplomatic headline within minutes.
- Physical differentials often lag because ships, crews, and insurers move slower than tweets.
- Freight and war-risk premia can stay elevated even when the front month slumps.
- A calm session in New York does not automatically reopen every lane in the Gulf.
That gap between paper and wet barrels is where a lot of people get hurt. They see WTI down a dollar and assume the crisis is over. Then a single vessel delay resets the whole conversation.
Why One Hundred Dollars Became The Line In The Sand
Round numbers are lazy and powerful. One hundred dollars a barrel is easy to put on television. It is also the point where inflation narratives get louder in importing countries. When that happens, governments look for a valve. Talks are a valve. So are releases from strategic stocks, jawboning of producers, and sudden optimism about spare capacity.
In my experience, the first retreat from $100 is rarely the last word. It is often a pause while both camps test whether the other side blinked. If diplomacy stalls, the same traders who sold this week will buy the dip with less shame than they admit.
Does that sound cynical? Maybe. Energy is a cynical business dressed up as a macro theme. People need fuel. States need revenue. Navies need sea lanes. Those three facts do not vanish because a meeting ran long.
Brent Versus Wti: Same Scare, Different Personality
Brent still carries more of the seaborne, internationally traded story. WTI is a U.S. inland grade with a different logistics spine. When the fear is about the Gulf, Brent usually does more of the talking. When the fear is about U.S. demand or domestic inventories, WTI can lead.
| Benchmark | Recent print | Session move | What it usually prices |
| Brent November | $98.51 | -0.75% | Seaborne supply and global risk |
| WTI November | $89.59 | -1.03% | U.S. balances plus imported fear |
The spread between them is a mood ring. If Brent stays stubborn while WTI sags, the market is still paying for waterborne risk. If both sink together, the story is broader: less panic, softer demand talk, or simple position washout.
Right now the washout explanation looks tidy. Five sessions of declines after a run at $100 is the classic shape of a crowded geopolitical long getting uncomfortable.
How A Three Hour Meeting Changes Probability, Not Physics
Physics in this market is barrels, tankers, and chokepoints. Probability is whether someone is willing to interrupt those barrels. A long meeting lowers the implied chance of interruption. It does not add a single extra cargo.
That distinction is easy to lose when the screen is green or red. I have sat through enough of these cycles to know the pattern. First comes the shock premium. Then comes the “talks are happening” discount. Then comes the wait, which is the hardest part, because the wait looks like boredom until it does not.
Oil prices are also unlikely to see a huge jump for now if mediation keeps the temperature down.
Unlikely is not the same as impossible. One stray incident in a narrow channel can reprice months of calm. That is why I prefer to talk about the distribution of outcomes rather than a single target. The middle of the distribution just got cheaper. The tail did not disappear.
The Human Side Of A Geopolitical Oil Tape
It is tempting to treat all of this as ticks on a chart. Somewhere, though, ship captains are deciding whether to wait or steam. Insurers are repricing risk. Refinery buyers are asking whether November barrels will actually show up on time. Those are human decisions with diesel and jet fuel at the other end.
I’ve found that the public conversation jumps too fast from “talks” to “cheap gasoline.” Retail fuel is a lagging, sticky thing. Wholesale crude can fall for a week and pump prices barely blink. Anyone promising instant relief at the station is selling a story, not a barrel.
There is also the political theater. A leader who talks about a “big decision” is keeping optionality. Markets hate optionality when it belongs to someone else. They like it when it belongs to them. That asymmetry is why a single phrase can move more oil than a decent inventory report.
What “Annihilate” Language Does To Risk Premia
Harsh language raises the ceiling of imagined outcomes. A subsequent meeting lowers the floor of immediate outcomes. Put those together and you get a wide range with a softer near-term tone. Traders call that a two-way market. Civilians call it confusion.
Confusion is tradable. It is also exhausting. One day the complex is pricing catastrophe. The next day it is pricing a communique. The day after that, someone remembers the tankers still sitting in the strait.
If you only remember one thing from this week, remember that sequence. Threat, meeting, dip. The sequence can repeat. It has before.
Demand Is Not Innocent In This Pullback
Geopolitics gets the camera. Demand does a lot of the quiet work. When crude has already jumped, consumers ration a little. Airlines hedge. Trucking firms delay discretionary miles. Emerging-market importers get careful with dollars. Those small cuts add up just as talks hit the tape.
So part of the twelve percent retreat is probably not diplomacy at all. It is the market admitting that $100-plus oil is a demand destruction machine. Mix that with a three-hour meeting and you get a tidy selloff that looks cleaner than it is.
- Price spikes ration use at the margin.
- Talks reduce the urgency to hoard.
- Funds that bought the scare start booking profits.
- The screen prints lower even if the strait is unchanged.
That four-step loop is old. It still works because humans still overpay for certainty and then sell it the moment certainty looks slightly less expensive.
Positioning, Funds, And The Ugly Middle
When speculative length builds into a geopolitical story, the first credible de-escalation headline becomes a crowding-out event. Nobody wants to be the last long in a peace scare. The phrase is almost funny until you are the last long.
The ugly middle is the period after the first dip and before anyone knows if talks are real. Prices can drift. Volatility can shrink. Then a single remark resets implied vol. If you trade options, that middle is where premium goes to nap and then wakes up angry.
I would not pretend to know the next print. I would watch whether each dip is bought by physical players. If refiners and traders keep lifting cargoes on weakness, the floor is firmer than the headlines. If physical stays sleepy, the paper market can keep leaking.
Mediation, Third Parties, And The Temptation To Overread
Third-party mediation is useful and overread in equal measure. It can keep phones ringing. It can also become a headline that outruns the substance. Markets love a mediator because a mediator is a character in the story. Characters are easier to price than logistics.
Still, extra channels are better than zero channels. If Islamabad or any other capital can lower the temperature, spare capacity elsewhere in the world gets a little more time to matter. Time is underrated in oil. Spare barrels need weeks. Diplomacy needs hours. The mismatch is the whole game.
What This Means For Everyday Energy Costs
Households do not buy Brent. They buy liters and gallons with taxes stuck on top. A one percent drop in futures is not a night out. It is a hint. If the hint survives a few weeks, retailers start to follow. If it dies in forty-eight hours, nobody at the pump notices.
Airlines and shipping firms notice faster. Their fuel desks live in the wholesale market. A calmer strip of prices can delay fare hikes or surcharge chatter. That is the real-world transmission that matters before voters feel anything.
For investors outside energy, the message is broader. A softer oil print takes a little heat out of the inflation scare and a little heat out of the “risk-off” impulse in equities. It is not a regime change. It is a weather change.
A Practical Framework If You Follow The Complex
You do not need a secret model. You need a short checklist that survives both headlines and silence.
- Is the diplomatic calendar still active, or did the room go dark?
- Are ships moving through the strait at a normal pace?
- Is the $100 area acting as a magnet or as a ceiling?
- Are physical differentials confirming the futures move?
- Is the bid coming from consumers or only from short-term funds?
If talks continue and ships move, dips can extend. If talks stall and ships wait, the premium returns with less warning than people expect. That is not forecast bravado. It is just how this market has behaved whenever a chokepoint sat in the first paragraph of the news.
A working sketch, not a prophecy:
  40% diplomacy path with grinding lower volatility
  35% rangebound chop between relief and doubt
  25% sudden re-pricing if a physical disruption hits
Treat those weights as a mood board. Update them when facts change. Do not marry them.
The Quiet Lesson Under The Noise
Markets are not moral. They do not reward the better speech. They reward a lower chance of missing barrels next month. Tuesday’s meeting, as described, lowered that chance enough to knock a bit off Brent and a bit more off WTI. Wednesday’s tape then did what tapes do. It marked the new odds.
I still glance at those anchored ships when I think the story is over. The water does not care about a three-hour meeting. The water only cares whether hulls can pass. Until that question is boring again, oil prices will keep one foot in diplomacy and one foot in the strait.
And that, frankly, is the part I trust more than any single quote from a podium. Quotes fade. Chokepoints do not. If the next session is another long conversation, the complex can stay heavy. If the next session is a slammed door, you already know which way the first tick will lean.
Where The Story Goes From Here
Watch the calendar, not just the close. Follow whether language from both capitals stays transactional or turns theatrical again. Keep an eye on freight, because freight is often honest when futures are performing. And give the $100 handle respect. It is not magic. It is simply where politics and petroleum keep bumping into each other.
If you came here hoping for a neat ending, I do not have one. That is the point. A meeting can change the weather. It cannot, by itself, redraw the map of energy. The barrels still have to move. The ships still have to pass. Until they do it without anyone holding their breath, this market will keep offering rallies that look like fear and selloffs that look like hope.
Hope is cheaper this week. Fear is not gone. That is the whole article, dressed in dollars and cents.