
Have you ever watched a market shrug at news that should have sent prices flying? That is the strange feeling hanging over crude this week. Missiles and drones hit Saudi infrastructure over the weekend, political language turned sharper, and yet oil still drifted lower. I keep coming back to one stubborn fact: barrels are still moving. Not perfectly. Not without risk. But moving enough that traders are unwilling to pay up just because the headlines sound ugly.
Why Oil Fell While The Region Looked More Dangerous
Futures for the international benchmark slipped about one and two thirds percent, landing near one hundred two dollars a barrel for November. The U.S. grade used in domestic pricing dropped a bit more, close to ninety eight and a half. Those are not crash numbers. They are the kind of modest retreat you get when fear is real but physical supply refuses to vanish on cue.
In my experience, crude is less romantic than geopolitics. It cares about tankers leaving ports, pipelines that can be rerouted, and inventories that either tighten or do not. Right now the tape is saying the physical system is bruised, not broken. That distinction matters more than any fiery interview clip.
The Pipeline Hit That Did Not Empty The Market
Saudi Arabia’s East-West line is one of those pieces of kit you only notice when someone tries to knock it out. It exists so crude can travel west when the usual Gulf route looks messy. Weekend attacks by Iran-backed Houthis used missiles and drones. That sounds like an automatic squeeze. It was not, at least not yet.
Bank research circulating among desks noted that Middle East oil flows remain surprisingly strong even after that disruption. Average flows over a recent ten-day window still sat around seventeen point one million barrels a day. That is roughly six point one million below last year’s typical pace. Painful, sure. Catastrophic? Not from those figures alone.
Middle East oil flows remain surprisingly strong despite the disruption to Saudi Arabia’s East-West pipeline.
I’ve found that markets hate a vacuum more than they hate bad news. As long as some barrels keep leaving the region, shorts stay comfortable and longs stay patient. The moment loadings collapse for several consecutive days, that patience evaporates. We are not there yet.
What Those Flow Numbers Actually Tell You
Seventeen million barrels a day still sounds enormous until you remember how much the world drinks. A six million barrel shortfall versus a calmer year is not a rounding error. It is the kind of gap that usually lifts prices. So why the dip?
Because traders are betting on normalization speed, not on the last attack. They are watching whether Saudi shipments recover through alternative routes, floating storage, and other terminals. They are also watching whether buyers who paused last week quietly return this week. Price follows that second wave of behavior more than the first explosion.
- Flows can look “strong” even while sitting well below last year’s average.
- A pipeline outage matters less if tankers can load elsewhere within days.
- Paper markets often fade a geopolitical spike if physical cargoes keep clearing.
- The real squeeze starts when freight, insurance, and waiting time all jump together.
That last point is the one I would not ignore. Insurance premia and war-risk clauses can tax a barrel without a single extra well going offline. If owners start refusing certain waters, the official flow number can stay decent while the delivered barrel becomes scarce and expensive.
Politics Is Now A Price Variable, Not Background Noise
U.S. leadership comments over the weekend pushed the story beyond pipelines. The president said he was in a “deciding mode” and that “very big things” could happen soon in the wider confrontation with Iran. He framed the choice in stark terms. Markets heard the tone even if they did not immediately bid crude higher.
Perhaps the most interesting aspect is the lag. Equity traders sometimes sell first and ask later. Oil traders often wait for a confirmed loss of barrels. That habit can look reckless in hindsight. It can also save you from buying every rumor at the top.
Any setback or renewed deterioration in shipping conditions would tighten the physical market and restore upward pressure on prices.
– Market strategist commenting on export normalization
I agree with the spirit of that warning. Diplomacy and export recovery are now twins. If talks stall and ships start hugging safer coasts, the same flow table that comforted people on Monday will look outdated by Friday.
Brent Versus WTI: Same Story, Different Accent
Brent is the waterborne grade. It feels every extra day a very large crude carrier spends waiting. WTI is more inland, more pipeline, more U.S. inventory. When both fall together, the message is broad: the market does not yet believe a structural shortage is here.
When they diverge, pay attention. A rising Brent-WTI spread usually means seaborne risk is doing the heavy lifting. A falling spread can mean U.S. supply or demand is the louder voice. Right now they moved in the same direction. That is a consensus shrug, not a regional panic isolated to the Gulf.
| Contract | Recent Move | What It Signals |
| Brent November | Down about 1.66% near $102.15 | Waterborne risk priced, not panicked |
| WTI October | Down about 1.83% near $98.46 | Domestic complex not chasing a spike |
| Ten-day Mideast flows | About 17.1 million bpd | Disrupted but still functioning |
| Gap vs 2025 average | About 6.1 million bpd lower | Tightness exists beneath the calm |
Look at that gap versus last year again. The market can fall on a Monday and still be structurally tighter than it was twelve months ago. People forget that. A down day is not the same thing as a well-supplied world.
How Traders Are Really Thinking About The Next Two Weeks
Desks I talk with are not arguing about whether risk is elevated. Of course it is. They are arguing about path. Does Saudi export recovery beat the political clock, or does the political clock beat the tankers?
- Confirm whether East-West volumes can be offset from other terminals within a few loadings.
- Watch war-risk insurance quotes on key Gulf and Red Sea routes.
- Track how many very large crude carriers actually sail versus how many wait.
- Listen for official language that either freezes escalation or widens it.
- Only then decide if the dip is a gift or a trap.
That sequence sounds boring. Good. Boring process beats heroic guessing when a region is this tense. I would rather look slow for a week than look brilliant for one hour and wrong for a month.
The Physical Market Still Has The Casting Vote
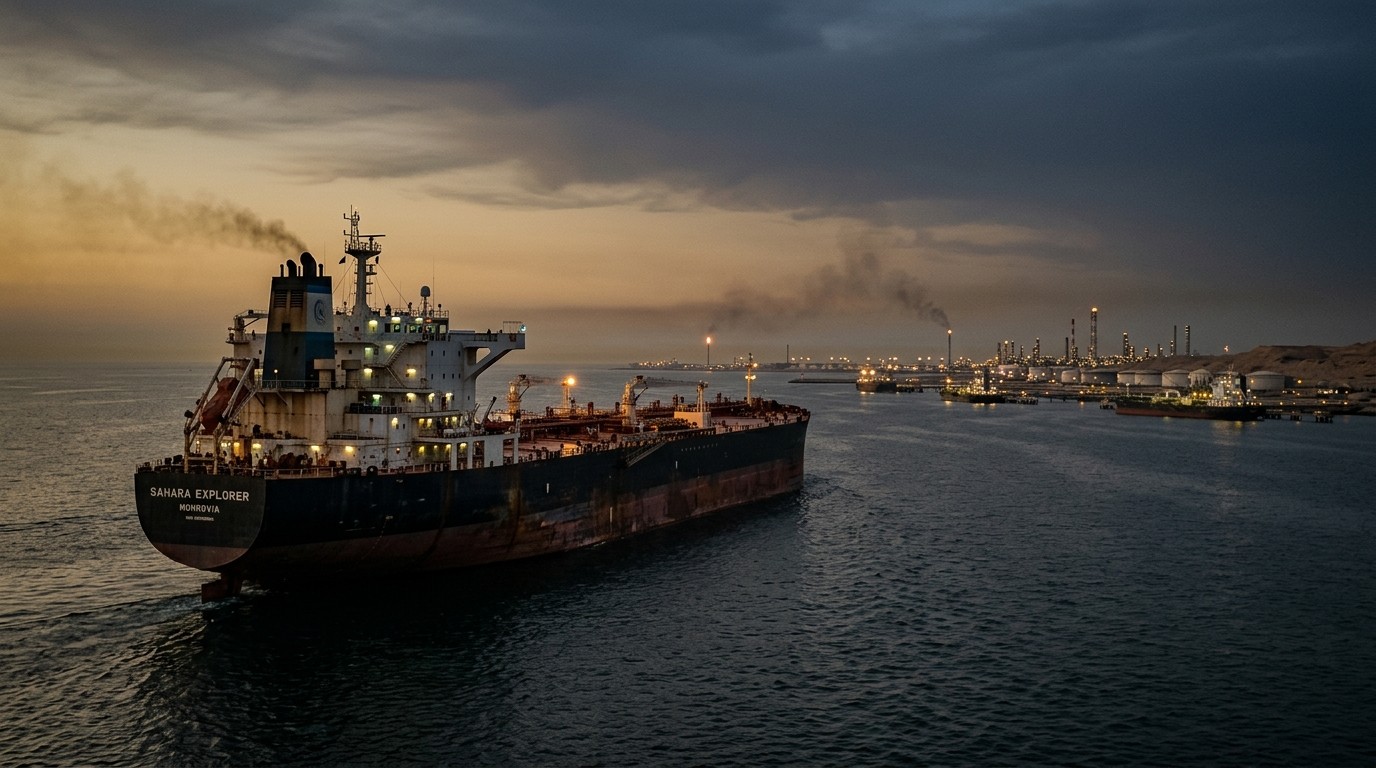
Paper oil can spin on comments. Physical oil spins on berths, pumps, and captains willing to sail. Photos of tankers arriving at coastal storage in the eastern Mediterranean are a reminder that crude is a logistics business wearing a political costume.
Iraqi barrels moving toward Syrian storage do not settle the Saudi question. They do show that the region keeps improvising. Improvisation is how shortages get delayed. It is also how they sneak up on you, because everyone assumes the workaround will last forever.
I’ve sat through enough of these episodes to know the pattern. First comes the attack. Then comes the statement that flows are fine. Then comes a quiet week where freight firms and prompt differentials lift even while the front-month future looks sleepy. Then, if luck runs out, the future wakes up all at once.
Where Upward Pressure Could Return Fast
If shipping conditions deteriorate again, the physical market tightens and prices get a second wind. That is not a brave forecast. It is almost mechanical. Fewer effective sailing days equal fewer timely barrels. Buyers who delayed purchases then compete for the same remaining cargoes.
Renewed attacks on pumping stations, a wider insurance freeze, or a political decision that raises the chance of broader military action would all do the job. Any one of those is enough. Two at once would be loud.
Would I call a new high from here just because the region is angry? No. Anger is already in the price to some degree. What is not fully in the price is a multi-week loss of a large slice of seaborne supply. That remains the tail, and tails pay when people stop believing they exist.
A Plain-Language Read On Demand, Not Just Supply
Everyone is staring at the Gulf. Fine. Also stare at the buyer. If refiners already ran hard through summer and product stocks look comfortable in a few key regions, they can wait out a scare. If diesel cracks are firm and winter stocking is late, they cannot wait. Demand optionality is the silent partner in every geopolitical oil story.
That is why a one-day drop after an attack is not automatically bullish or bearish for the month. It is a vote on whether refiners feel urgent. Urgency is a feeling you can measure in prompt differentials and freight, not in television volume.
What I Would Watch If I Had To Trade This, Not Narrate It
I would keep position size modest until flows print a clear second week of recovery or a clear second week of decay. I would treat sharp down days after attacks as information, not as a moral judgment about who is right in the conflict. Markets do not award points for outrage.
I would also refuse to pretend precision. Nobody knows the timing of a political decision described as imminent. Pricing “very big things” in advance is how accounts get chopped. Pricing confirmed barrels lost is how accounts survive.
Working checklist:
  Flows first
  Freight second
  Official language third
  Front-month heroics last
Is that too simple? Maybe. Simple frameworks survive messy weeks. Fancy ones look clever until a drone changes the map overnight.
The Human Habit Of Overfitting One Weekend
We love a clean story. Attack happens, oil must soar. Oil falls, therefore the attack did not matter. Both versions are lazy. The attack mattered. The market also decided the current loss of capacity is something the system can limp through for now.
Those two facts can live in the same paragraph. Adults in this market have to hold both. If you need the world to be only terrifying or only fine, you will misread every print from here to year-end.
And yes, I have been guilty of that myself on faster days. You see a flash, you want a thesis that fits on one line. Crude rarely offers that courtesy.
Why “Surprisingly Strong” Is A Phrase That Ages Badly
Analysts used that phrase for a reason. Relative to the drama, loadings held up. Relative to a peaceful baseline, they did not. Keep both rulers on the desk.
Phrases like that also become magnets for complacency. If enough people repeat that flows are fine, fewer people hedge the next outage. That is how a second incident produces a bigger jump than the first. Positioning gets one-sided under the comfort blanket.
So use the phrase as a snapshot, not as a personality test for the market. Snapshots expire.
A Longer View Without The Crystal Ball Act
Even if this particular scare fades, the year has already taught buyers that spare capacity is a political object as much as an engineering one. That lesson does not unlearn itself because Monday’s settlement was red.
Strategic stocks, slower project approvals, and higher risk premia in freight are the slow variables. Weekend drones are the fast ones. The fast variables make television. The slow ones make the five-year average price.
If you only trade the fast ones, you will feel brilliant in bursts and tired in stretches. If you only watch the slow ones, you will miss the week that pays the year. The unglamorous job is doing both without confusing them.
Practical Takeaways Without The Hype
- A modest price drop after an attack often means physical barrels are still clearing, not that risk disappeared.
- The six million barrel gap versus last year’s flow rate is the quiet bullish fact under a bearish session.
- Export normalization and diplomacy now move together; a slip in either can reprice prompt crude quickly.
- Watch insurance and waiting time if you want the truth earlier than the headline future.
- Keep the political tail on the map without letting it dictate every tick.
None of that tells you where settlement prints on Friday. It tells you how to read the next print without fooling yourself. That is the only edge most of us get in a week like this.
The Question The Market Has Not Answered
Can the region keep moving enough oil while political temperature stays this high? Monday voted yes, for now. That vote can be reversed by a single night of successful strikes or a single morning of harsher policy language.
Until then, the tape is doing what it often does in the early innings of a scare. It asks for evidence. It discounts speeches. It still prices fear, just not at the maximum setting. Whether that is wisdom or stubbornness will be obvious only after the next flow report, not before it.
I will keep watching the water, not the podium. Ships do not bluff as well as people do. When they linger, prices eventually stop lingering with them. When they sail, even angry weeks can end in quieter closes. That is the unpretty truth sitting under this latest drop, and it is the one worth carrying into the sessions ahead.