
Have you ever watched a market calm down in public while everyone in the room still keeps one eye on the door? That is how oil prices today feel. WTI and Brent both eased after reports that extra Saudi barrels could reach Asia through ship-to-ship transfers, yet the Middle East story is not finished. I keep coming back to the same thought: a few extra cargoes can soothe a headline, but they cannot erase geography.
Why Oil Prices Today Still Matter More Than The Daily Tick
Crude is not just another ticker. When Brent crude and WTI futures stay near triple digits, the cost of moving goods, heating homes, and running factories starts to leak into almost every other conversation. Grocery receipts. Airline fares. Bond yields. Even the mood around interest-rate cuts. That is why a pipeline scare and a workaround in the same week can look confusing if you only glance at the last print.
In my experience, energy markets punish people who treat a one-day dip as a verdict. The tape can fall because a shipment route reopened. It can also fall because traders simply needed a breather after a violent run. Distinguishing those two things is the whole job.
What Changed After The East-West Pipeline Shock
Attacks on Saudi Arabia’s East-West pipeline interrupted a route that had become unusually important. Once tanker traffic through the Strait of Hormuz grew more constrained, the Red Sea export path via Yanbu stopped being a backup and started acting like a main street. Loadings there paused. Some European-bound cargoes were canceled. Markets did what markets do. They priced scarcity first and asked questions later.
Then the tone shifted. Officials described the outage as brief. Industry sources pointed to extra crude being offered to Asian refiners through ship-to-ship transfers near Oman’s Sohar port. That is not a pretty solution. It is a practical one. And practical solutions are often enough to knock a few dollars off the front-month contract.
Alternative export routes can restore some lost barrels, but the outlook still depends on whether the region stays contained.
– Market note from an energy trading desk
I find that last clause more important than the first. Restoring “some” supply is not the same as restoring confidence. Confidence needs a route that looks durable next month, not just next Tuesday.
WTI And Brent: Two Benchmarks, One Nervous Complex
Brent, the international marker, hovered a little under the mid-$100s in the latest session. U.S. crude slipped as well, trading just above $102. Those numbers will look dated by the time you refresh a quote screen. The relationship between them will not. When Middle East barrels look trapped, Brent usually carries more of the scare. When U.S. inventories or Gulf Coast logistics dominate, WTI tells a more local story.
Right now the two contracts are moving like cousins at the same funeral. Polite. Close. Still watching the same family drama. That family drama is oil supply from a region that still sets the marginal barrel for much of the world.
| Benchmark | Latest Snapshot | What It Reflects |
| Brent | Near $105.81 | Seaborne crude and global risk premium |
| WTI | Near $102.14 | U.S. barrels plus imported shock effects |
| Middle East crude | Tight logistics | Pipeline and strait constraints |
Do not worship the decimals. Worship the spread logic. If Brent stays rich to WTI for long enough, refiners and traders rearrange flows. If the spread collapses, it often means the geopolitical premium is fading or U.S. tightness is catching up. Either way, the spread is a sentence. The last price is just punctuation.
Ship-To-Ship Transfers Are A Patch, Not A New Map
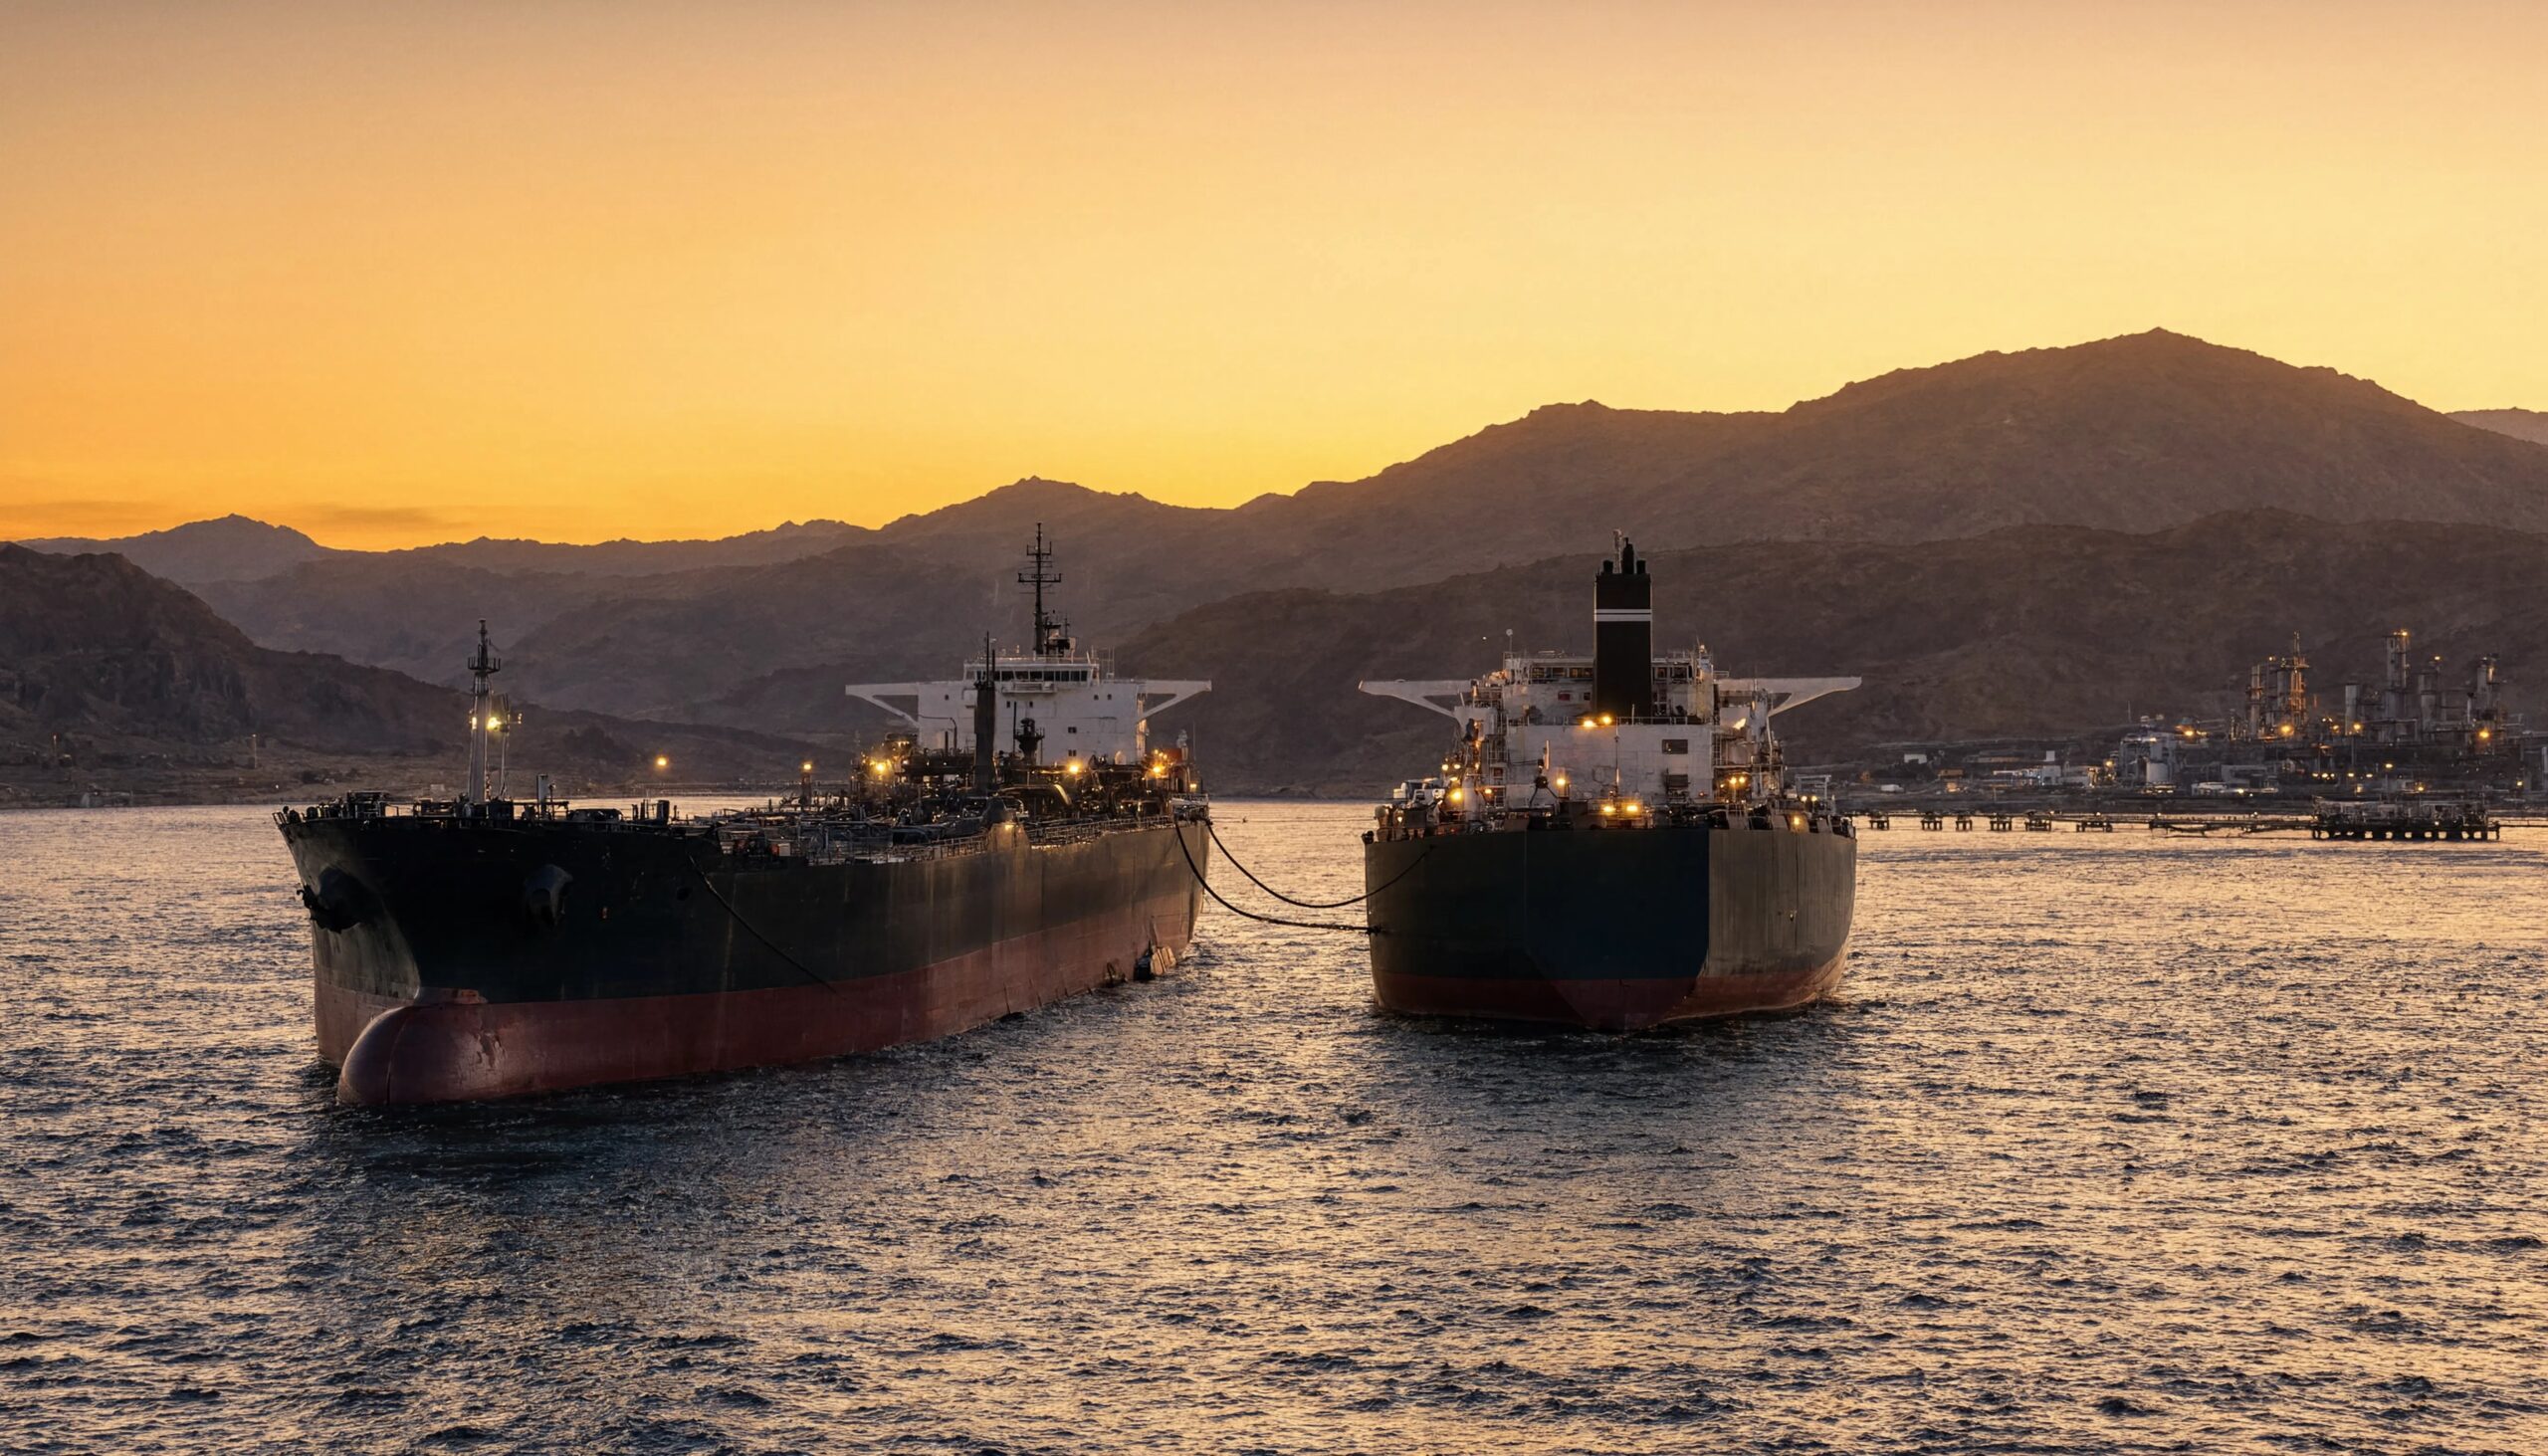
Ship-to-ship crude transfers sound exotic until you remember that tankers have been doing messy workarounds for decades. Two vessels meet. Hoses go over. Barrels move. Paperwork gets creative. The physical oil still exists. The delay, the weather risk, the insurance premium, and the extra days of floating storage are the real cost.
Offering extra cargoes near Sohar helps Asian refiners who cannot wait for Yanbu to look normal again. It also signals something markets like: a producer with inventory and a will to keep customers. That combination can cap a panic. It rarely removes the risk premium entirely, because everyone knows a patch can be blocked by the next incident.
- Transfers can place barrels closer to hungry Asian plants.
- They add cost, time, and operational friction.
- They do not rebuild a damaged pipeline overnight.
- They leave European supply questions only partly answered.
Perhaps the most interesting aspect is psychological. Once traders see steel moving, they stop assuming every canceled loading is a permanent hole. That is useful. It is also how markets get lulled right before the next map change.
Yanbu, Hormuz, And The Awkward New Geography Of Exports
For years, classroom maps treated the Strait of Hormuz as the choke point and everything else as commentary. That was lazy even then. It is reckless now. When tanker traffic through the strait becomes politically expensive, the East-West line and Red Sea terminals stop being trivia. They become the story.
Yanbu turning into a primary outlet was never the original design of the global oil system. It was an adaptation. Adaptations work until someone hits the adaptation. Then you get the scramble we just watched: canceled European stems, hurried talk of brief outages, and a sudden interest in Omani anchorage points that most casual investors could not find on a map last month.
I’ve found that energy commentary often talks as if barrels are interchangeable stamps. They are not. A light cargo aimed at a Mediterranean refinery is not the same molecule, timing, or freight bill as a heavy-ish grade floated toward East Asia. When one door slams, another door may open, but the kitchen layout changes. Product yields change. Freight changes. Timing risk changes.
Why Asian Refiners Sit At The Center Of This Relief Rally
Asia is where a huge share of seaborne crude still wants to go. If those plants can secure barrels, the loudest shortage narrative loses volume. That is why extra Saudi availability aimed at Asian buyers matters more than a generic promise that “supply will be fine.” Fine for whom? In which month? On which vessel?
Refiners do not buy vibes. They buy arrival windows. A ship-to-ship option near a workable port can protect crude runs for a few weeks. It cannot guarantee that diesel and gasoline cracks will behave. Product markets have their own tempers. When crude is expensive and logistics are messy, the downstream complex can stay tight even while the headline crude contract takes a nap.
High crude, gasoline, and diesel prices at the same time keep inflation nerves awake, even if the front-month oil contract slips for a session or two.
That is the unglamorous truth. Consumers do not fill a tank with Brent. They buy finished fuel. Policymakers do not campaign on a futures curve. They campaign on pump prices and grocery inflation. So a modest drop in crude can coexist with a still-ugly bill at the station.
The Inflation And Rates Shadow Behind Every Barrel
Here is where oil stops being an energy story and becomes a macro story. Persistent strength in crude and refined products feeds pessimism about how quickly a central bank can ease. Bond yields notice. Equity multiples notice. Household budgets notice first, which is the part analysts sometimes skip because it does not fit neatly on a chart.
A renewed escalation that hits production or export infrastructure harder would not just lift oil. It would keep the inflation debate sticky. Sticky inflation is a gift to nobody sitting in a rate-sensitive asset. That is why a “temporary” pipeline interruption still matters after officials use the word temporary. Markets have heard that word before.
- Watch whether refined product prices ease with crude or ignore it.
- Watch whether freight and insurance premia stay elevated.
- Watch whether canceled European cargoes get replaced or merely postponed.
- Watch whether official language stays calm after the next security incident.
If those four stay ugly while WTI dips, the dip is a pause. If they improve together, then maybe the market is allowed a longer exhale. I am not in the business of selling certainty on a region this tense. Anyone who is should be asked who is underwriting the next accident.
What “Brief And Temporary” Usually Means In Oil
Energy officials like short words when infrastructure is damaged. Brief. Temporary. Contained. Those words can be honest. They can also be aspirational. Pipelines get repaired. Pumping resumes. Tankers line up again. All of that can happen in days. Markets still remember the times it did not.
The useful question is not whether a minister wants the outage to be short. Of course he does. The useful question is whether the physical system has slack. Slack in storage. Slack in unused pipeline capacity. Slack in idle tankers that are willing to work awkward transfers. Saudi Arabia has more slack than most producers. That is why the latest workaround landed as reassurance rather than theater.
Still, slack is not infinity. If more than one artery is hit, or if insurance markets step back from a lane, the math changes fast. I have watched oil rally on rumors that later proved smaller than advertised. I have also watched oil shrug at headlines that later proved larger. The common thread was not the first statement. It was the second and third confirmation from actual loadings data.
How Traders Translate A Pipeline Headline Into A Position
There is a craft to this, and it is less mystical than people pretend. First comes the scarcity impulse. Then comes the search for substitution. Then comes the argument about how long substitution can last. Then someone looks at the calendar spread and asks whether the back months believe the scare.
If the front month panics while later contracts barely budge, the market is treating the event as a bruise. If the whole curve lifts, the market is pricing a regime. Right now the public conversation is still about bruises: a hit pipeline, a few canceled stems, a clever transfer plan. Regime talk stays in the footnotes. That can change in an afternoon.
A simple field checklist:
  1. Confirm loadings, not just statements.
  2. Separate crude tightness from product tightness.
  3. Track freight and war-risk premia.
  4. Ask which customer set lost barrels first.
  5. Revisit the curve after the second data print, not the first rumor.
None of that requires a crystal ball. It requires patience, which is the rarest commodity on an energy desk during a war-risk week.
Europe’s Quiet Problem While Asia Gets The Workaround
Canceled shipments to European customers do not vanish from the balance. They show up as a hunt for replacement grades, longer voyages, or lower runs. Europe has spent years rearranging its crude slate. Another scramble is not fatal. It is expensive. Expense becomes inflation. Inflation becomes politics. Politics becomes the reason a “commodity story” ends up on a general-news homepage.
This is where I get a little stubborn as a writer. People want one number to stand in for the whole world. WTI down 0.22 percent. Fine. That number does not tell you whether a European independent refiner just lost a preferred cargo and now has to buy something heavier, later, and farther away. The national average pump price will notice that kind of detail before the average social feed does.
Middle East Escalation Paths Markets Actually Price
Not every flare-up is equal. Markets draw crude little diagrams in their heads, even if they never admit it. A single pipeline strike with a credible repair timeline is one box. A wider campaign against export terminals is another. A sustained squeeze on a strait is a third. Production damage at the field level is a fourth, and that one is the ugliest because you cannot ship what was never pumped.
The latest session belongs in the first box, with a nervous glance at the others. Additional cargoes and calm official language pulled prices off their most anxious perch. That is rational. It would be less rational to pretend the other boxes were painted over.
Why dwell on this? Because energy risk is path dependent. The same barrel can be cheap in one political weather system and priceless in another. Investors who only memorize yesterday’s close are always late to that weather change.
What Households And Businesses Should Actually Watch
If you do not trade futures, you can still read this market like a weather report. Look at diesel more than you look at the cocktail-party Brent number. Diesel is the quiet bully of freight, farming, and construction. Look at gasoline if your question is consumer mood. Look at jet fuel if your question is travel demand and airline margins.
- Drivers: pump prices lag crude, sometimes by weeks.
- Manufacturers: energy surcharges show up in input costs before retail tags.
- Investors: rate-cut odds can wobble when fuel stays high.
- Exporters and importers: freight plus insurance can dominate the headline crude move.
I’ve sat through enough dinner conversations where someone declared oil “down” because a futures contract had a red day, while their own delivery invoices said otherwise. The invoice is the adult in the room.
A Realistic Base Case, And The Uncomfortable Tail
The calm base case is straightforward. Repairs progress. Transfers continue. Some European volumes get rerouted rather than lost. Prices stay high by the standards of the last decade, but they stop behaving like a vertical emergency. That case is already partly in the market. You can see it in the modest daily declines after the first shock.
The uncomfortable tail is also straightforward. Another piece of infrastructure gets hit. Insurance markets widen further. A larger share of regional gas and oil output goes offline. Then the conversation jumps from “days” to “quarters,” and inflation risk stops being a footnote in a rates preview. I do not enjoy writing that paragraph. Leaving it out would be dishonest.
Uncertainty about escalation paths can matter as much as the barrels that actually fail to sail.
Uncertainty has a price. That price lives inside the risk premium. When the premium shrinks on a workaround, celebrate the logistics team. When it shrinks only because people are tired of being scared, keep your helmet nearby.
How To Read The Next Few Sessions Without Getting Fooled
Short sessions lie. A Wednesday night bounce or a Thursday morning fade can be nothing more than positioning. Ask whether open interest is building with the move. Ask whether products confirm crude. Ask whether physical differentials in Asia and Europe agree with the paper market. If paper is soft and physical is still screaming, believe physical.
Also give yourself permission to hold two ideas at once. Idea one: extra Saudi availability is real and helpful. Idea two: the strategic map of Middle East exports is more fragile than it was before the latest attacks. Those ideas do not cancel. They describe the same week from two altitudes.
If that sounds unsatisfying, good. Oil is unsatisfying when it is honest. The satisfying version is a slogan. Slogans are how people buy the top or sell the repair.
The Human Texture Behind A Cold Commodity
It is easy to talk about cargoes as if they were chess pieces. Somebody still has to connect those hoses at sea. Somebody still has to decide whether a crew sails into a more expensive insurance zone. Somebody in a refinery control room still has to choose a crude diet that will not wreck a unit. Those are not abstract choices. They are why workarounds have limits.
I keep a small private rule when writing about this stuff. If I cannot picture the person doing the job, I am probably drifting into jargon. Ship-to-ship transfers are not a metaphor. They are night shifts, weather windows, and a lot of steel moving in slow motion. That slowness is why a market can look relieved on a screen and still feel tight in the real world.
Putting Today’s Tape In A Longer Frame
Zoom out and the picture is less about one pipeline and more about a world that keeps discovering how many of its comforts travel by tanker. High prices are a messenger. Sometimes they say demand is firm. Sometimes they say politics just taxed the route. This week they are saying both, with politics doing most of the shouting.
Will WTI and Brent drift lower if no new shock arrives? Possibly. Spare capacity, demand caution, and visible workarounds can do that. Will they look cheap if another artery fails? Not a chance. That fork is the only forecast I trust, because it does not pretend to know the next headline.
So where does that leave a reader who just wanted “oil prices today” and got a longer walk than expected? Hopefully with a better question. Not “is crude up or down?” but “did the supply map get simpler or more complicated?” Today it got a little simpler at the margin and stayed complicated underneath. That is usually the moment when casual commentary declares the crisis over. I would wait for the next set of loadings before joining that chorus.
A Closing Read On Risk, Relief, And What Comes Next
Relief rallies in oil have a habit of feeling earned right up until they are not. The latest dip after alternative Saudi export arrangements is understandable. Extra barrels aimed at Asia reduce the chance of an immediate physical vacuum. Official language about a short interruption reduces the chance of a pure panic premium. Both of those are facts worth respecting.
Respect is not the same as amnesia. The East-West line was hit because it mattered. Yanbu mattered because other waterways became harder. Transfers near Oman matter because someone needed a third option after the first two looked bruised. That sequence should stay in your head longer than a single downtick in WTI.
If you remember only one thing, remember this. Oil prices today are a compromise between visible workarounds and invisible next risks. The compromise can look calm on a quote board. The underlying trade-off is still sharp. Watch the barrels that actually move. Watch the fuels people actually buy. And keep a little skepticism for any story that tries to end a regional energy shock with a single clever transfer at dusk.