
Have you ever watched a project look inevitable on a slide deck and then stall the moment it hits dirt, water, and local politics? That is the feeling hanging over Oracle’s huge New Mexico campus known as Project Jupiter. I have covered enough infrastructure cycles to know this pattern. The renderings stay glossy. The loan documents stay thick. Then one permit, one pipeline, or one community hearing changes the calendar.
Why Project Jupiter Suddenly Matters To Every AI Investor
This is not a side story about one warehouse in the desert. Project Jupiter sits at the awkward intersection of AI infrastructure, project finance, and public consent. The campus is planned across a vast site in Doña Ana County. Four data halls. On-site power measured in gigawatts. A tenant that needs capacity for demanding AI workloads. A financing stack large enough that traders actually notice when the paper wobbles.
Reports in recent days say the tenant sent a force majeure notice to the developer side. That phrase sounds dramatic. In practice it is a legal shock absorber. It does not automatically kill a project. It does not, by itself, prove the buildings will never open. What it does is preserve rights if events outside a party’s control push the schedule. And schedules, in this market, are the whole game.
Force-majeure notices are commonplace in developments of this scale and are often used to preserve contractual rights among project partners. They do not, by themselves, establish a project delay or change delivery expectations.
That is the official line from the tenant’s camp, and it is worth taking seriously. Big projects send paper like this all the time. Still, markets do not trade on press language. They trade on time, permits, and cash. When loans backing a campus of this size slip into the high-80s or low-90s on the dollar, people pay attention. Healthy project paper usually sits near par. A discount is a signal, not a verdict.
The Campus In Plain English
Strip away the branding and you get a simple machine. Land. Concrete. Power. Cooling. Fiber. People. Project Jupiter is designed as a multi-building campus on roughly 1,400 acres near Santa Teresa. The power target often cited is about 2.45 gigawatts of on-site capacity. That is industrial-scale electricity, not a rooftop array and a few generators.
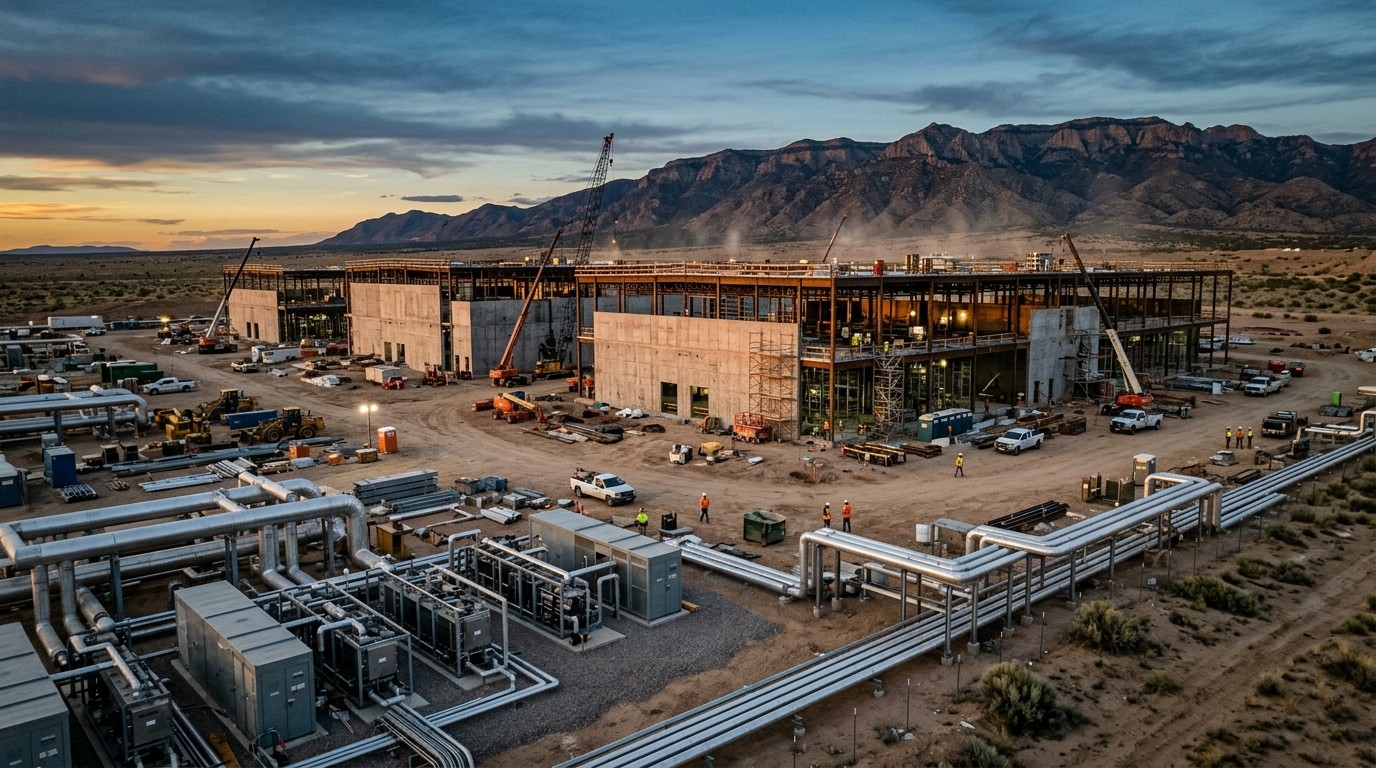
The investment figure attached to the industrial revenue bond authorization is enormous: up to $165 billion over a long operating window. That number is not the same thing as cash already spent. It is a legal and tax architecture that lets a county support a project of unusual size. Construction started in late 2025. By early autumn 2026, reports put physical completion somewhere around a quarter of the way there. Crews have logged millions of hours. Tax receipts have already shown up in state tallies. So this is not vapor. It is a job site with real steel in the ground and real arguments around it.
In my experience, that mix is exactly when projects get hardest. Early enough that redesigns are still possible. Late enough that lenders, vendors, and local officials all have skin in the game.
What Force Majeure Actually Does Here
People hear the Latin and imagine a walk-away clause. That is usually wrong. A force majeure notice is a way to say: something outside our control is interfering with the timetable we signed. Weather. Courts. Regulators. A pipeline that cannot get a route. An air permit that sits in review. The notice can let a tenant delay certain payments if the facility misses a target date. It does not have to mean the tenant wants out.
Current reporting describes the notice as aimed at protecting the tenant if the campus misses a 2028 online target, not as an attempt to abandon the lease. The developer-side funds have said financial commitments to the multi-year project are unchanged. Both statements can be true at once. Contracts can stay alive while calendars slip.
Why does that matter for the wider US AI rollout? Because so many capacity promises assume buildings arrive on a date that was written when the power plan still looked simpler. If one flagship site needs extra quarters, other sites feel the squeeze. Model training does not wait politely. Neither do customers who signed for clusters.
Loans Below Ninety Cents Are A Mood Ring
The financing story is almost as large as the concrete. A syndicated loan package on the order of $18 billion has been quoted in stressed territory, around 89 to 91 cents on the dollar. That is not a default. It is a price. Traders are saying completion risk, sponsor credit, or both, deserve a haircut.
Layer on the tenant’s own balance sheet. Capital expenditure for AI infrastructure has been heavy across the sector. Corporate ratings for the tenant sit only a notch above high yield after a mid-year downgrade. That does not make the campus unfinanceable. It does make new buyers of the loan package more cautious. Efforts to distribute the debt more widely reportedly met resistance. When paper sticks with the original banks, those banks have less room for the next campus.
I find this part more revealing than the legal notice. Force majeure is language. A bid at 90 cents is a number. Numbers tend to travel faster through credit desks than through planning commissions.
| Piece of the stack | Role | Pressure point |
| Tenant | Operates AI compute | Schedule and payment timing |
| Developer / equity funds | Owns and builds campus | Permits and cost overruns |
| Bank syndicate | Provides project loans | Secondary pricing and hold period |
| Power vendor | On-site fuel cells | Gas supply and air permits |
| County and state | Land, tax, water process | Public consent and hearings |
Water Is The Argument Everyone Can Understand
In a dry county, you do not need a finance degree to care about wells. Local opposition has focused on water and air. That is rational. Deserts remember every gallon.
The project team says the campus will not drink from the public potable system for cooling or fuel-cell operations. The plan uses non-potable industrial well water from an existing rights holder. Cooling is described as closed-loop and non-evaporative. Fuel cells need a one-time fill and then very little makeup water. Company fact sheets put initial fills in the millions of gallons across buildings and cells, then annual maintenance near 168,000 gallons. Averaged over fifteen years, they compare that to a handful of households.
Residents and advocacy groups hear a different story. They see a new industrial load in a region that already argues over agriculture, municipal supply, and brackish groundwater. A state high court temporarily paused an emergency well authorization tied to construction water. That order landed on a small commercial farm as well as the project timeline. Ugly, human, and very local.
There is also a $50 million water-infrastructure commitment tied to the tax arrangement. Some of that money is meant for pipes, tanks, treatment, and possible desalination work. Accruals have started. Timing of actual projects is still a municipal puzzle. Promises of future pipes do not cool a hearing room when people are worried about wells this year.
Claims that the campus will drain the public drinking system sit on one side. Claims that industrial water is almost a rounding error sit on the other. The truth, as usual, lives in the permits and the monitoring.
Power Redesigns Are Not Free
The original energy concept leaned on gas turbines and diesel backup. That plan ran into state land issues and pipeline trouble. Officials denied key right-of-way pieces. Federal staff also flagged incomplete filings. So the team flipped the design toward solid-oxide fuel cells from Bloom Energy, with installed capacity up to about 2.45 gigawatts and a behind-the-meter microgrid.
On paper that shift cuts local combustion emissions sharply and slashes operating water versus evaporative cooling plus turbines. It also creates a new dependency: fuel cells still need gas feedstock, air permits, and a pipeline path. Reports say an Energy Transfer line meant to serve the site slipped by nearly six months after repeated permit denials and a route change. An air-quality permit for the fuel-cell system has been sitting in the state process with a late-November decision window after earlier legal pauses.
This is the part outsiders miss. Swapping turbines for cells is not a software update. It is a new stack of equipment, contracts, warrants, and regulatory files. Equity-style warrants between the tenant and the power vendor add another layer of complexity that filings have not fully unbundled by site. None of that is scandal by itself. It is just more moving parts on a clock that already looks tight.
How Local Pushback Became A Credit Variable
Investors used to treat community opposition as a footnote. Not anymore. Pipeline denials, well stays, and air-permit lawsuits now show up in loan chatter the same week they show up in county meetings. That is new. Or at least newly priced.
Doña Ana County approved a landmark industrial revenue bond ordinance in September 2025. That political yes was real. It did not freeze later no’s from land offices, courts, or environmental groups. A project can have a tax deal and still lack a pipe. It can have crews on site and still wait on an air file. Those gaps are where force majeure language grows.
- Water authorizations can be stayed even after emergency approvals.
- Pipeline routes can be rejected more than once and then redrawn.
- Air permits can continue in process while lawsuits pause pieces of the file.
- Closed-loop cooling reduces ongoing use but does not erase the first fill or the politics of wells.
- Behind-the-meter power protects local rates and still needs fuel and permits.
Perhaps the most interesting aspect is how quickly these items jumped from local newsletters into secondary loan quotes. That transmission belt is now short. A Sunday night court order can be a Monday morning price.
Does This Jeopardize The Broader US AI Build?
Short answer: it stresses the timeline. It does not, by itself, cancel the national buildout. There are other campuses, other states, other power designs. But Project Jupiter was sold as a flagship inside a much larger compute initiative tied to frontier model training. When a flagship slips, buyers look at every other desert and cornfield site with colder eyes.
Think about the bottleneck chain. Chips can arrive faster than substations. Models can be ready faster than cooling loops. Customers can sign faster than counties can process wells. The industry spent two years talking about GPU scarcity. The next two years may be about interconnection, water, and consent.
I have found that markets overreact in both directions. First they treat every campus as a sure 2027 start. Then one stressed loan tape makes them treat every campus as doomed. Neither is right. The adult reading is narrower. This site has a real schedule risk into 2028. The tenant says it still expects the plan to hold. The legal notice says the tenant wants protection if it does not. Lenders have already marked some of that doubt into the price.
What To Watch Next Without Getting Lost In Noise
- The state air-quality decision window for the fuel-cell system.
- Any further court action on well authorizations and construction water.
- The revised in-service date for the gas line that would feed the cells.
- Secondary quotes on the project loan package.
- Whether the tenant restates or quietly slides the 2028 target.
- How much of the water-infrastructure fund actually hits local pipes.
- Physical percent complete versus hours worked on site.
If those seven items stay messy, the force majeure file will look prophetic. If they clear, the notice will look like ordinary big-project hygiene. Either way, the episode already taught credit desks a lesson. AI campuses are not software releases. They are industrial plants sitting on someone else’s aquifer.
A Fair Reading Of The Tenant’s Position
It would be sloppy to treat the company as a cartoon villain draining a desert for chips. The public fact sheets are detailed. Closed-loop cooling. Non-potable source water. A redesigned power plant after the turbine path failed. Commitments measured in tens and hundreds of millions for schools, workforce, habitat, and local systems. Crews already paid. Taxes already collected. A statement that the campus remains on the planned schedule and that the firm is committed to New Mexico.
It would be equally sloppy to treat local critics as people who simply hate growth. Water law in the West is old, specific, and emotional for good reason. Emergency well authorizations that skip a full hearing invite legal challenge. Pipelines across state land invite another. Fuel cells are cleaner than a turbine farm and still not invisible.
The grown-up frame is conflict among legitimate claims. Compute demand is real. Arid hydrology is real. Contract rights are real. Credit marks are real. Force majeure is the paperwork that appears when those claims collide.
Why The 2028 Date Became The Whole Fight
Delivery years are not decorative. Lease economics, model-training calendars, vendor slots, and loan covenants all hang on a commercial operations date. Miss it and rent starts later, or starts with arguments. Miss it and a customer looks for clusters somewhere else. Miss it and an $18 billion package that was underwritten on one timeline has to live on another.
Some earlier chatter put an even tighter first-phase date on the table and then watched that date recede. Whether the slip is seven months or longer depends on which milestone you count: first hall energized, full 2.45 gigawatts, or something in between. The tenant now points to 2028 and says the plan holds. The notice is there in case the plan does not.
I keep coming back to a simple test. Can the gas arrive, the air permit land, and the well fight settle in a way that lets commissioning happen in an orderly queue? If yes, this becomes a footnote in a long construction log. If no, the US AI map loses a large block of planned capacity right when models are getting more expensive to train.
Lessons For Other Campuses Already In Motion
Other developers should steal the unglamorous lessons, not the renderings.
First, publish water math early and in household units people can check. Vague promises about efficiency do not survive a county microphone. Second, do not assume a gas route is a commodity. In some states it is a political event. Third, build schedule slack into loan models before the first protest, not after the first court stay. Fourth, treat force majeure as maintenance, not as a surprise press cycle. Fifth, remember that secondary loan prices will now watch planning boards.
Campus risk stack in one glance:
  Permits  - water, air, land, pipeline
  Power    - technology swap plus fuel path
  Credit   - sponsor rating and loan distribution
  Consent  - hearings, lawsuits, local funds
  Time     - 2028 is the date that prices everything
None of this means the country should freeze AI building. It means the country should price the dirt. Silicon gets the poetry. Concrete gets the delays.
The Human Scale Under The Gigawatts
It is easy to talk in billions and forget the fourteen jobs at a sod farm mentioned when a well order hit. Or the construction hours already worked. Or the school and workforce checks that have been promised and, in some cases, started. Big infrastructure always has a face. Ignoring that face is how projects lose rooms they needed to win.
I’ve found that the projects that finish are usually the ones that keep talking after the first denial. They redraw the pipe. They change the turbines. They put numbers on the well. They fund the municipal tank. They still might miss a year. They are less likely to miss the decade.
Project Jupiter is in that messy middle. Not mothballed in any official sense. Not smooth. Not cheap to finance at par. Not simple to love if you live next to the wells. Not simple to abandon if you need the compute.
A Closing Read, Without The Panic Or The Gloss
So where does that leave a reader who just wants a straight take? The campus is real. The opposition is real. The force majeure notice is real and, according to the tenant, routine. The loan discount is real and less routine. The power redesign was a serious course correction after the turbine path failed. The water plan is more conservative than the loudest rumors and still politically radioactive in a dry county. The 2028 date is the load-bearing wall.
Does this jeopardize the entire US AI rollout? That headline is hotter than the evidence. A single delayed flagship can slow a customer’s cluster plan. It can reprice project debt for the next three sites. It can force model builders to hunt spare capacity in places with easier permits. That is material. It is not the same as the national build stopping cold.
Watch the permits. Watch the pipe. Watch the loan tape. And remember that every AI boom eventually meets a county agenda packet. That meeting, not the keynote, is where the calendar gets written.
If the next sixty days clear air and water files, this story shrinks. If they do not, force majeure will look less like boilerplate and more like the first honest schedule. Either outcome will teach the same thing. Intelligence may be artificial. Foundations are not.