
Have you ever looked at your paycheck and wondered why it feels like you are running in place no matter how many hours you put in? I have. More than once. The numbers on the bank statement climb, yet the real cost of living seems to sprint ahead even faster. That quiet frustration sits at the center of something much larger than personal budgeting mistakes. It points to a structural shift that has been unfolding for decades and shows little sign of slowing.
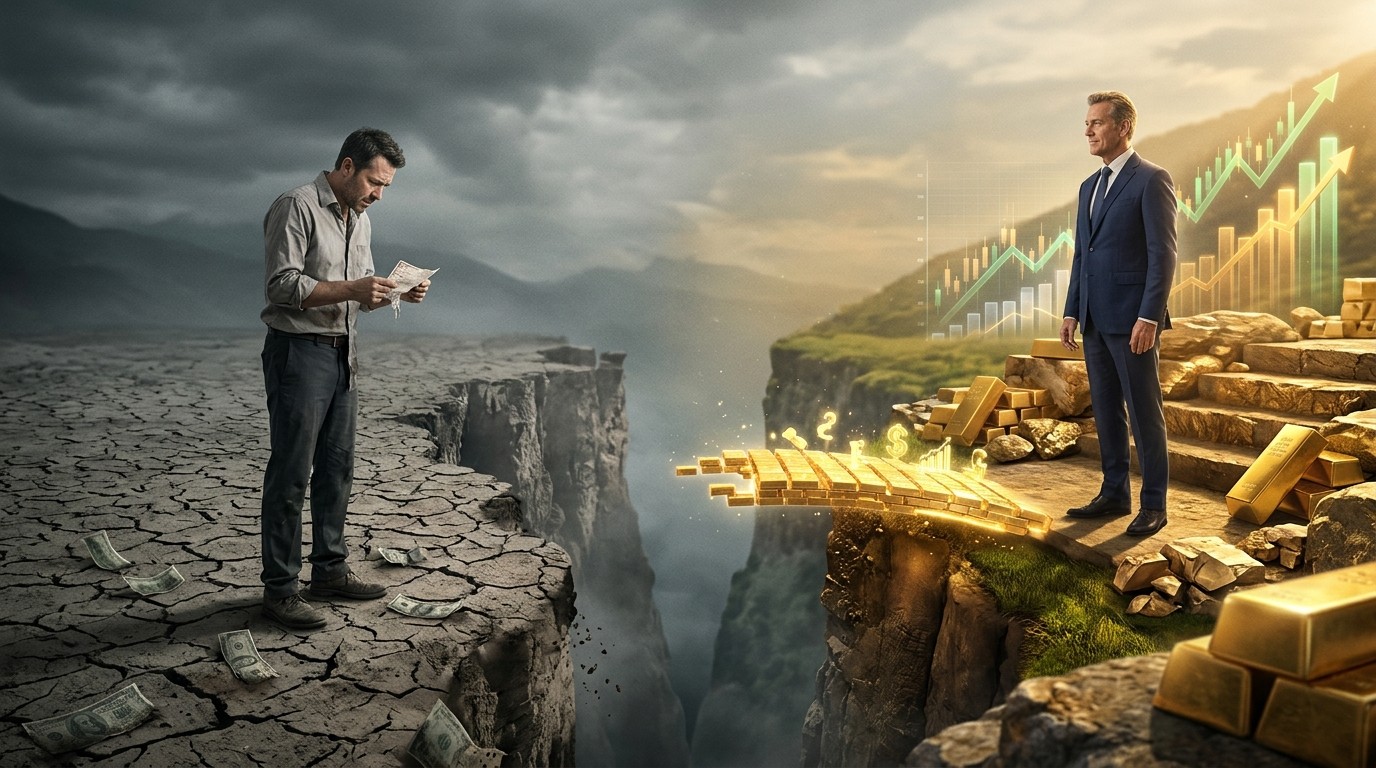
Three observations feel almost impossible to argue with at this point. Government spending keeps expanding. Financing that spending requires ongoing currency creation. And wages, for the vast majority of people, simply cannot keep pace. Put those together and one conclusion becomes unavoidable: working harder will not let you outrun the money printer. You either own assets that rise with the expanding money supply or you gradually fall behind.
The Expanding Gap Between Wages And Asset Prices
Look at the long-term picture and the pattern is hard to miss. Over more than six decades, official consumer prices rose nearly tenfold according to the standard measure. Wages rose a bit more than that on paper. Housing climbed further still. Yet the money supply itself multiplied many times over. When you measure purchasing power against the actual expansion of currency rather than the carefully adjusted official index, wages retained only a fraction of their earlier relative value.
Gold and broad stock indexes, by contrast, more than kept up. In some periods they surged far ahead. Housing sat somewhere in the middle, outperforming paychecks but lagging the growth in money itself. The same story repeats when you zoom in on the last quarter century. Prices roughly doubled by the official gauge. Wages rose a little more. Housing advanced modestly further. The money supply, however, expanded more than fivefold. Stocks kept pace with that expansion. Gold left everything else in the dust.
I find this comparison more revealing than most official statistics. The official price index can be massaged through changes in methodology, substitution assumptions, and quality adjustments. The raw growth in the quantity of money is harder to disguise. If your net worth does not at least match that expansion, your relative position in the economy is slipping. Over time that slippage compounds.
Why Official Inflation Numbers Feel Misleading
Most of us sense the gap between reported inflation and lived experience. Grocery bills, rent, insurance, and education costs often rise faster than the headline figure suggests. Part of the reason is that the official measure tries to capture a changing basket of goods and services. Another part is that asset prices sit outside that basket almost entirely. Yet for anyone trying to buy a home, build retirement savings, or simply maintain living standards, asset prices matter enormously.
Currency creation does not land evenly across the economy. New money tends to reach financial markets and real assets first. By the time it filters into wages and everyday prices, the early recipients have already captured much of the gain. That process has repeated through successive cycles of policy response. Each major intervention seems to leave the money supply permanently higher than before.
You cannot outrun the money printer by working harder. You need to own the right assets or fall behind.
That single idea captures the core dynamic better than most lengthy reports. Labor income remains important, of course. Yet in an environment of persistent currency expansion, the returns to ownership compound faster than the returns to effort alone.
Gold As The Clearest Mirror Of Debasement
Among major asset classes, gold stands out for a simple reason. It is money itself, not a claim on future cash flows or a productive enterprise. It carries no balance sheet risk, no management risk, and no earnings risk. Its long-term price path has reflected the cumulative effects of currency expansion more cleanly than almost anything else.
From the late 1990s onward, gold’s percentage gain dwarfed the rise in the money supply, the stock market, housing, and wages. Over the longer multi-decade span the outperformance is still clear, though stocks closed much of the gap. What remains striking is the relative calm with which gold achieved those results. Volatility exists, sometimes sharply, yet the absence of company-specific or sector-specific risks gives it a different character from equities.
In my view, that combination of historical performance and lower idiosyncratic risk makes gold a natural anchor for anyone serious about preserving purchasing power across decades. It does not mean gold should be the only holding. It does mean it deserves a central place in any plan that aims to stay ahead of ongoing currency expansion.
Stocks And The Power Of Ownership
Broad equity indexes have also delivered gains that roughly matched or exceeded money supply growth over long periods. Much of that advance stems from the same monetary backdrop that lifts gold. Companies can raise prices, refinance debt on favorable terms when rates are low, and benefit from the general expansion of nominal activity. Shareholders capture those effects through higher earnings and valuations.
Not every stock participates equally. Quality, competitive position, and capital allocation still matter. Yet the overall market has served as a vehicle for keeping pace with currency creation in a way that pure wage income has not. The compounding effect becomes especially powerful when dividends are reinvested and when holdings span multiple cycles.
Housing occupies a more complicated middle ground. Home prices have risen faster than wages in most long-term windows, providing meaningful wealth gains for owners. At the same time they have lagged the expansion of money itself. Leverage through mortgages can amplify returns, but it also introduces risk and ongoing costs. For many households the primary residence functions more as shelter than pure investment. Treating it as the sole inflation hedge has left some owners less protected than they expected.
How The Divide Compounds Over Time
The difference between asset owners and wage-dependent households does not stay constant. It widens. Each year that asset prices and capital gains outpace wage growth, the relative gap grows. Over a working lifetime the cumulative effect becomes substantial. Two people who start with similar incomes can end up in very different financial positions simply because one consistently directed savings into ownership of productive or monetary assets while the other relied primarily on labor income and cash savings.
Policy choices reinforce the pattern. When fiscal deficits expand and monetary authorities accommodate them, the resulting currency creation supports asset prices more reliably than it supports real wage growth. Recessions may interrupt the process, yet the long-term trajectory has pointed higher after each major intervention. The years surrounding 1933, 1971, 2008, and 2020 stand out as visible steps in that progression. Each left the monetary base larger than before.
I do not see persuasive evidence that this underlying dynamic is about to reverse. Demographic pressures, entitlement commitments, and the political difficulty of sustained austerity all point toward continued growth in government outlays. Financing those outlays through pure taxation faces practical limits. Currency expansion remains the path of least resistance.
Practical Implications For Building Resilience
Recognizing the pattern is one thing. Acting on it is another. The first priority becomes joining the asset-owning side of the divide in a deliberate way. That does not require exotic strategies or perfect timing. It does require consistent allocation of savings toward holdings that have historically kept pace with or exceeded money supply growth.
- Prioritize ownership of monetary assets such as gold that serve as long-term stores of value
- Build exposure to productive businesses through broad equity ownership
- Treat excess cash as temporary rather than permanent
- View wage income as the engine that funds asset accumulation rather than the end goal
- Accept that short-term volatility is the price of long-term protection
None of these steps eliminate risk. Markets can and do decline, sometimes sharply. Gold can go through multi-year periods of sideways movement or even losses in nominal terms. The advantage appears most clearly across full cycles and multi-decade horizons. Patience and consistency matter more than brilliant individual decisions.
Diversification across asset types still has value. Concentrating everything in a single category invites unnecessary fragility. At the same time, diversification that keeps large portions of wealth in pure cash or pure wage dependence leaves the owner fully exposed to the erosion process. The balance point differs for each person according to age, obligations, and risk tolerance. The common thread is intentional ownership.
The Psychological Side Of Staying Ahead
Watching asset prices rise while wages lag can feel discouraging if you are still building your position. It can also create a sense of urgency that leads to poorly timed decisions. I have seen both reactions. The more useful mindset treats the process as a multi-decade project rather than a race that must be won this year or next.
Small, regular contributions compound. Early ownership of even modest amounts of gold or equity funds begins the process of capturing currency expansion rather than merely enduring it. Over time those holdings grow in both nominal and relative terms. The psychological shift from pure earner to partial owner changes how future policy decisions feel. What once registered only as higher prices starts to register also as higher asset values.
That shift does not require abandoning ordinary work. Most people will continue to rely on labor income for daily expenses and for the savings that fund asset purchases. The change lies in directing a growing share of those savings into ownership and in viewing that ownership as the primary long-term defense against debasement.
Looking At The Longer Arc
Currency expansion on a sustained basis is not a new phenomenon. It has characterized the modern financial system for more than a century. The scale has grown, and the visibility has increased, yet the direction has remained consistent. Moments of restraint occur. They have not altered the multi-decade trajectory.
Within that environment, assets that function as stores of value or claims on productive capacity have delivered superior results to pure labor income. Gold has done so with relatively clean exposure to the monetary effects. Equities have done so while also capturing real economic growth and innovation. Housing has provided partial protection alongside the practical benefit of shelter. Cash and pure wage dependence have lagged.
The practical takeaway is straightforward even if the implementation takes discipline. Make ownership a priority. Let gold serve as a core holding that reflects the cumulative damage of currency creation. Use equities to participate in the broader expansion of nominal activity and real enterprise. Treat housing as both a place to live and a partial inflation buffer rather than a complete solution. Keep cash for near-term needs and opportunities, not as a multi-year store of value.
None of this guarantees smooth progress. Markets will fluctuate. Policy will surprise. Personal circumstances will change. What remains relatively constant is the underlying pressure of expanding currency against finite real resources. Those who own claims on those resources or on monetary metals that have historically preserved value stand in a stronger position than those who rely solely on the next paycheck.
The wealth divide between asset owners and wage earners is not primarily a story about individual virtue or failure. It is a story about how money is created and how that creation flows through the economy. Recognizing the pattern early and aligning personal finances with it offers a realistic path to greater resilience. Ignoring it leaves a lifetime of work exposed to gradual erosion that official statistics often understate.
In the end the choice is practical rather than ideological. Own assets that historically outpace currency expansion, or accept that the purchasing power of labor alone will likely continue to lag. The numbers across decades make that choice clearer than most daily headlines. The gap is already wide. There is little reason to expect it to narrow on its own.
Building a position takes time. Starting earlier rather than later improves the odds. Consistency beats perfection. And the quiet confidence that comes from holding real claims on value, rather than only claims on future wages, changes how the entire process feels. That shift, more than any single trade or prediction, is what separates those who keep pace from those who gradually fall behind.