
Five weeks ago the announcement landed like a thunderclap. Diesel from Russia would flow again into the American and global marketplace. Prices would ease. Drivers would feel relief at the pump. That was the promise. Today the numbers are in, and the picture looks very different from the original pitch.
Russian diesel shipments roughly doubled in October. That part is real. Yet not a single cargo generated by the special waiver has docked at a United States port. Two tankers that once aimed for American waters quietly changed course. A third still sits idle somewhere off the East Coast, waiting for a buyer who has not appeared. The global market absorbed the extra barrels. America received none of them.
What Actually Happened to the Extra Diesel
Market tracking data show Russian diesel exports climbed from about 135,000 barrels a day in September to roughly 271,000 barrels a day in October. Independent energy analysts put the jump in a similar range, from around 120,000 to 260,000 barrels daily. On paper the increase looks impressive. In historical context it is far more modest.
A normal October used to see Russian diesel exports closer to 700,000 barrels a day. Even after doubling, current volumes sit at barely one-third of that old average. Measured in tonnes the story stays the same. October loadings reached about 985,000 metric tons. Typical monthly figures in stronger years ran near 2.7 million tons. Moscow has talked about pushing 2.15 million tons in the current month, yet officials themselves have already warned that renewed attacks on refineries could slice that target.
In my view the gap between the headline doubling and the still-depressed absolute numbers is the first place any serious observer should look. Doubling a low base still leaves the market short of what it once considered normal.
Where the Barrels Actually Went
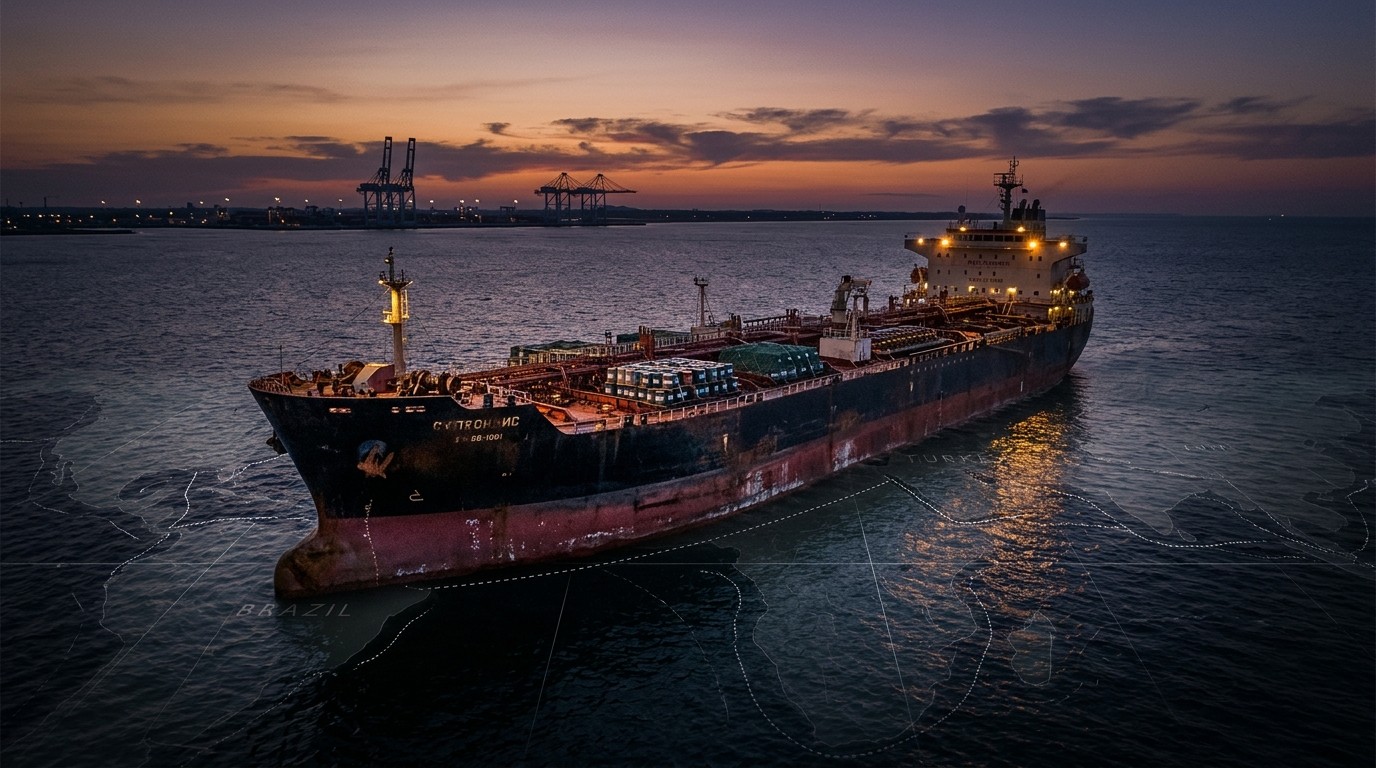
Brazil quickly became the leading destination for the extra Russian diesel in early November. Turkey remained a steady buyer. Other destinations absorbed the rest. The pattern is clear: the barrels found homes, just not American ones.
A White House official described the outcome as consistent with the original intent. More diesel on the world market should ease prices everywhere, including for American consumers. Diesel is after all a globally traded commodity. A cargo that arrives in Santos is one less cargo that has to leave the United States Gulf Coast bound for Brazil. That logic is not entirely wrong. It is simply a quieter claim than the original announcement that listed the American marketplace first.
This deal was made to add diesel supply to the global market, lowering prices for Americans and the world.
Fair enough. Yet the arithmetic of who actually received the physical barrels still matters to people watching port schedules and tanker positions.
The Tankers That Never Arrived
Three vessels originally signaled United States destinations. The first loaded roughly 40,000 tonnes of ultra-low-sulfur diesel and pointed toward New York. Two more followed with a combined volume near 140,000 tonnes. Then legal and political pushback arrived.
Lawmakers from both parties contacted banks and port authorities in New York, New Jersey, Houston, Beaumont and Corpus Christi. They warned that handling the cargoes could breach the existing statutory ban on Russian energy imports. One senator wrote directly to the Greek owner of the lead tanker. The governor of New Jersey told operators in her state to turn the ships away or face penalties, arguing that an administrative license cannot override a law passed by Congress.
The practical result was swift. One tanker redirected to Brazil. Another turned into the Mediterranean. The third altered its destination to “for orders,” later reversed course hundreds of nautical miles from New York, and eventually stopped offshore. Negotiations with the owner continue, which is another way of saying a buyer has not yet stepped forward.
Forty thousand tonnes equals roughly 300,000 barrels. The United States burns about four million barrels of distillate every day. That single cargo would have covered less than two hours of national demand. Industry executives have already called Russian volumes a drop in the bucket relative to the amount of refining capacity currently offline worldwide.
Why Exports Rose in the First Place
The temporary jump in Russian diesel shipments had less to do with the waiver itself and more to do with a short pause in attacks on Russian refineries. During that window plants were able to increase runs. Analysts who track the sector have been frank: the increase should be attributed mainly to that operational breathing room rather than to any sudden policy miracle.
The pause ended. Strikes resumed near the end of October. Moscow extended its own domestic diesel export restrictions through the end of January, carving out limited exceptions to keep the special arrangement technically alive. Most observers now expect Russian export volumes in the coming months to look lackluster again. Domestic needs, especially for gasoline, are taking priority as local shortages appear.
Russian refining capacity remains under real pressure. Near-term throughput is expected to stay constrained around four million barrels a day, with limited prospects for meaningful recovery while attacks continue. That is the binding constraint. A six-month administrative waiver does not repair a crude unit damaged last week.
The Bigger Refinery Problem
Global product markets were already tight before any of these headlines. Singapore middle-distillate stocks have been running about 44 percent below year-earlier levels. Stocks of jet fuel in the Amsterdam-Rotterdam-Antwerp region have been down more than 50 percent. Refiners everywhere have been prioritizing diesel output at the expense of other products.
Outages tell an even starker story. Russian refining outages have been running roughly 4.2 million barrels a day above seasonal norms. Middle East outages have added another 1.6 million barrels a day above normal. Planned maintenance worldwide was cut by about 27 percent year-on-year as refiners postponed work to keep units running. That deferred maintenance is now scheduled to hit harder in the second quarter of next year.
Even under an aggressive scenario in which every Middle East and Russian outage somehow disappears by January, major banks still model highly profitable refining margins for 2027. The historical mid-cycle average sits near ten dollars a barrel. The optimistic case lands near nineteen dollars. The base case climbs much higher. Product inventories have simply not rebuilt the way crude inventories sometimes do.
United States diesel inventories recently slipped below 100 million barrels for the first time in more than two decades. That is the kind of number that keeps market participants awake at night.
What the Numbers Mean for Prices
Retail diesel prices have eased somewhat from the peaks seen in September. National averages moved from above $6.50 a gallon down toward the low $6 range by early November. Most of that relief tracked broader geopolitical headlines rather than the modest extra volumes leaving Russian ports.
Could the additional global supply still shave a few cents off the price Americans pay? At the margin, yes. Global diesel is fungible. Extra barrels anywhere reduce the need for barrels from somewhere else. Yet the scale remains small compared with the multi-million-barrel daily shortfall created by damaged and offline refining capacity.
I have watched energy markets long enough to know that headline announcements often travel farther than physical barrels. The difference between those two speeds is where the real story usually lives.
The Timing Problem Almost Nobody Mentions
Refiners postponed a large share of autumn maintenance so they could keep running hard. That decision helped near-term supply. It also guarantees a heavier maintenance slate next spring. Analysts already flag the second quarter of 2027 as a period when planned downtime will sit well above normal, especially in Asia outside China, while Russian and Middle East plants may finally be running closer to seasonal rates.
In other words, the next diesel squeeze is already visible on the calendar. It does not require a single additional drone strike to materialize. Deferred maintenance alone can tighten the market again.
Putting the Deal in Perspective
Russia received a sanctions waiver running into next spring and a political talking point. Brazil and Turkey received the physical barrels. American consumers received the indirect, diluted benefit of a few hundred thousand extra barrels circulating in a market that remains short by several million barrels a day.
That is not nothing. It is also not the dramatic reopening of supply that some early commentary suggested. The structural problems sit inside damaged refining capacity, postponed maintenance schedules, and persistently low product inventories. Those issues will not disappear because one temporary waiver was granted.
Perhaps the most interesting aspect is how quickly the physical trade adjusted. Cargoes that could not land in the United States found other homes without much delay. The global market proved more flexible than the legal and political obstacles surrounding American ports.
Looking Ahead
Most energy analysts now expect Russian diesel exports to fade back toward subdued levels. Domestic rationing pressures, continued risk to refining assets, and the simple arithmetic of damaged capacity all point in that direction. Any lasting relief in diesel markets is more likely to come from the eventual normalization of Middle East operations and the eventual completion of deferred maintenance than from any single bilateral arrangement.
The tanker still sitting off the East Coast carries less than two hours of American demand. It has become a floating symbol of the gap between announcement and delivery. Whether it eventually finds a buyer or sails away remains an open question. The broader market, however, has already moved on.
Diesel remains a global commodity. Prices will continue to respond to the large forces of refining capacity, inventory levels, and geopolitical risk. The modest volume increase that followed the waiver is real. The absence of any of those barrels from American docks is equally real. Both facts can be true at the same time.
In the end the episode offers a useful reminder. Energy markets are messy. Announcements travel at the speed of social media. Tankers move at the speed of weather, insurance, law, and willing buyers. When those speeds diverge, the difference is usually measured in idle ships, redirected cargoes, and prices that refuse to fall as far or as fast as hoped.
The world received a bit more diesel. America received the theory of lower prices. The gap between those two outcomes is where the real story sits, and it is likely to remain relevant long after the current waiver expires.
Market participants will keep watching the weekly inventory numbers, the pace of refinery repairs, and the maintenance calendars that already look heavy for next spring. Those data points, more than any single announcement, will decide how tight the diesel market stays into 2027. For now the evidence points to continued pressure rather than rapid relief.
That is the unvarnished picture five weeks after the deal was first described as immediate help for the American and global marketplace. The global side collected the barrels. The American side is still waiting.