
Have you ever watched a market look calm on the surface and still feel the floor starting to tilt? That is the mood around European refining right now. A few days ago there was still talk that a key Saudi export route might bounce back fast enough to keep scheduled crude moving toward the continent. By the end of the week that hope had thinned out. Buyers were told, in plain commercial language, that next month’s barrels may simply not show up.
Why This Disruption Hits Europe At The Worst Possible Time
Winter does not negotiate. Households still need heat. Trucks still need diesel. Airlines still need jet fuel. When a large, contracted stream of crude disappears from the slate of European refiners, the problem is not abstract. It shows up in feedstock costs, product balances, and the kind of last-minute tender activity that usually means someone is already late.
I’ve found that energy shocks rarely arrive as one clean headline. They arrive as a stack of smaller problems that refuse to stay separate. A pipeline outage here. A shipping chokepoint there. A refining system that was already running with thin inventories. Then someone says, almost casually, that a whole region will miss its next cargoes.
The Route That Was Supposed To Bypass The Problem
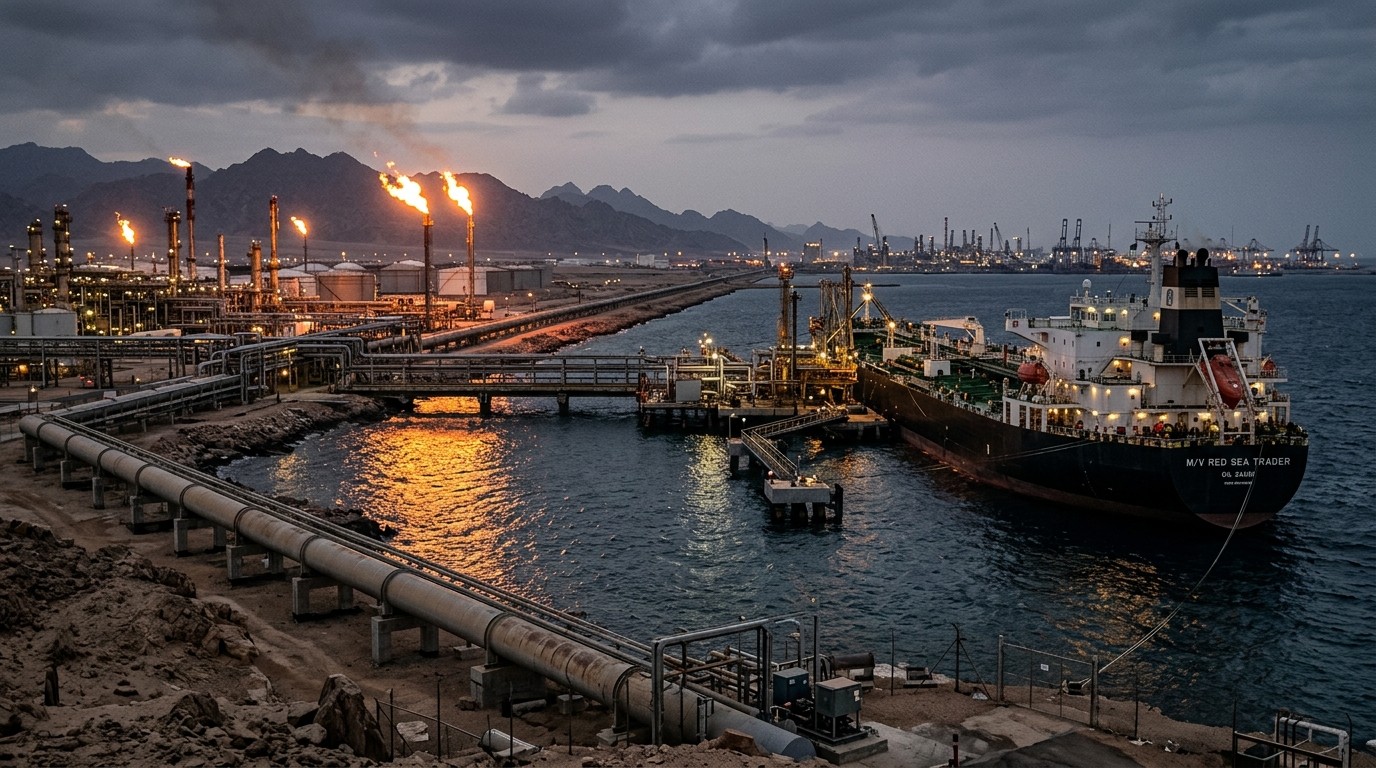
The East-West pipeline matters because it is not just another pipe in the desert. It moves crude away from the Strait of Hormuz and toward a Red Sea export terminal. In a normal year, that option is useful. In a year when tanker traffic through the Strait has been repeatedly threatened, that option becomes the difference between delayed barrels and missing barrels.
Saudi operators had been running that corridor hard. Full capacity talk was not marketing fluff. It was an attempt to keep oil moving while maritime risk stayed elevated. A drone strike earlier this month changed the arithmetic. Repair hopes flared midweek, then faded. That sequence is important. Markets can absorb bad news. They hate good news that evaporates.
When a backup route fails at the same time the main sea lane looks unsafe, buyers stop debating price and start debating availability.
That is where European refiners sit today. At least two of them were told there would be no Saudi crude next month. The same message appears to cover a much wider group of European customers. If that holds, contracted supply becomes a hole that has to be filled in the spot market, and the spot market is not feeling generous.
How Large Is The Missing Volume?
OECD Europe imported about 577,000 barrels a day of Saudi crude in June, according to the latest widely cited energy agency figures. That number is not the entire European crude diet. It is still large enough to matter when diesel and heating oil balances are already tight heading into the cold months.
Think about what refiners actually do with those barrels. They do not store diplomacy. They run units. They produce middle distillates. They meet contracts with distributors. If the crude slate changes suddenly, yields change. If yields change, product markets twitch. If product markets twitch in October, winter pricing gets a head start.
| Pressure Point | Why It Matters Now | Market Effect |
| Missed Saudi cargoes | Contracted feedstock disappears | Spot bidding rises |
| East-West outage | Red Sea route is constrained | Fewer alternative liftings |
| Hormuz risk | Shipping remains unreliable | Freight and insurance climb |
| Winter demand | Heating and trucking rise together | Diesel stays tight |
Poland’s Orlen has already gone hunting. More than ten tenders in a single week is not routine window dressing. That is a company trying to replace barrels before the calendar turns against it. Other buyers will do the same, some quietly, some in a hurry. Either way, the bid for replacement crude does not stay local.
Brent Above One Hundred Changes The Psychology
Brent has been trading around $103 a barrel. West Texas Intermediate has been near $101. Those are not panic prints by themselves. They are high enough to change how refiners, airlines, trucking firms, and governments talk about the next ninety days.
In my experience, the first $100 print is a headline. The second week above $100 is a planning problem. Companies stop asking whether prices are “too high” and start asking whether they can secure molecules at all. That shift is already visible in product markets. The U.S. diesel crack has been quoted near $112, a reminder that refining margins can scream even when crude itself looks merely expensive.
Some commodity strategists have started comparing the setup to earlier gasoline shocks. I would not stretch the comparison too far. Every cycle has its own plumbing. Still, the warning is fair. When refining capacity is strained and a major crude stream stumbles, product prices can overshoot crude prices. Consumers feel that first. Politicians feel it second.
A Market Without A Baseline View
Perhaps the most interesting aspect is how quickly professional forecasts have gone soft. One major bank’s commodities desk put it bluntly this week: for the first time since the regional conflict widened, they no longer have a clean baseline. They do not know how to model the endgame.
Uncertainty is not the same as volatility. Volatility is movement. Uncertainty is not knowing which variables still belong in the model.
That distinction matters for anyone watching inventories, freight, or refined product cracks. You can hedge a known shortage. You cannot hedge a map that keeps changing. Iranian pressure on shipping has not faded. Pipeline repairs are not a press-release event. European winter stocks are not infinite. Put those three facts on one desk and the “base case” starts looking like a wish.
What European Refiners Can Actually Do Next
Replacement barrels exist. They just do not sit in a neat pile labeled “same quality, same timing, same price.” North Sea grades, West African cargoes, U.S. exports, and various medium sours will all get a look. Each option comes with a catch. Freight. Timing. Sulfur. Distillation yield. Credit terms. Politics.
- Buy prompt cargoes and accept a richer premium.
- Adjust crude slates and live with a weaker middle-distillate yield.
- Draw product stocks earlier than planned and hope winter stays mild.
- Run harder on whatever crude is already in tanks, then face a steeper refill later.
None of those choices is free. That is the part casual commentary misses. A missed Saudi cargo is not only a volume problem. It is a quality and logistics problem. European plants are configured around certain slates. Swap in a different barrel and the diesel make can slip just when diesel is the product everyone wants.
Diesel Is The Quiet Villain In This Story
Crude gets the headlines. Diesel pays the bills and heats a large share of Europe. Natural gas tightness already limits easy substitution. If refiners lose a reliable sour or medium stream and cannot replace the distillate yield, the diesel balance gets mean. Trucking costs rise. Agricultural supply chains feel it. Heating oil buyers feel it later, then all at once.
I’ve watched winters where the crude market looked merely firm and the distillate market looked unwell. Those winters are the ones that surprise people. A $3 move in crude can hide a much larger move in the crack. Households do not buy Brent. They buy warmth and mobility.
Winter stress stack:
  Constrained Saudi loadings
  Fragile maritime routes
  Thin diesel flexibility
  Rising seasonal demand
Is every one of those items guaranteed to worsen together? No. Weather can break lucky. Diplomacy can blink. A pipeline can return faster than expected. I would not build a household budget or a trading book on luck.
Why The Red Sea Terminal Still Matters Even If Hormuz Reopens
People sometimes treat export routes as interchangeable. They are not. A barrel at Ras Tanura is not the same commercial object as a barrel already positioned for the Red Sea. Time, insurance, naval risk, and customer location all sit inside the price. Europe is west of the problem. That geography is why the East-West system became so valuable the moment Strait traffic looked ugly.
If the pipeline stays impaired, Saudi barrels bound for Europe have to travel a longer, riskier path or they do not travel at all. If they travel, freight and war-risk premia eat the margin. If they do not travel, European plants bid against Asia and the Americas for whatever is left. That contest does not stay polite.
The Knock-On Path From Cargo Notices To Pump Prices
Commercial notices go out first. Traders reprice second. Refiners rewrite run plans third. Distributors lift wholesale prices fourth. Drivers and households meet the bill last. The lag can be two weeks or two months depending on inventories and contracts. The direction is rarely a mystery.
- Supplier tells the refiner the November lifting is off.
- The refiner tenders for alternative crude and pays up.
- The new slate produces a different mix of gasoline, jet, and diesel.
- Wholesale diesel firms first because stocks were already tight.
- Retail heating and transport fuels follow once hedges roll off.
That chain is why a seemingly technical pipeline story belongs in a broader market conversation. It is also why “just buy somewhere else” is not a strategy. Somewhere else is already talking to three other refiners with the same problem.
What Investors Should Watch Without Getting Cute
I am not in the business of turning every outage into a victory lap for a trade. Still, the tape is leaving clues. Watch prompt crude spreads. Watch diesel cracks on both sides of the Atlantic. Watch freight on routes that suddenly look like the only open doors. Watch official inventory prints, but do not worship them. A draw can be seasonal. A draw plus failed cargoes is something else.
Equity investors will look at integrated majors, independent refiners, and shipping names. Fair enough. Just remember that a refiner with poor crude access can look busy and still lose money on the wrong slate. A tanker owner can look busy and still face ports that do not want the risk. Complexity is not a reason to freeze. It is a reason to stay specific.
The market does not need a perfect forecast. It needs an honest list of things that can no longer be assumed.
Assumptions That No Longer Look Safe
- That Saudi contractual volumes into Europe are effectively guaranteed month to month.
- That a desert pipeline can offset maritime risk for as long as needed.
- That European diesel can stay balanced on luck and mild weather.
- That $100 crude is only a headline for traders and not a planning price for industry.
- That product cracks will behave if crude supply merely “finds a way.”
Drop those assumptions and the picture gets clearer, if less comfortable. Europe is heading into the heating season with less certainty about a traditional supplier. The supplier is dealing with damaged infrastructure and a region that has not calmed down. The refining system has limited slack. That is the whole story, even if the next week brings a repair update that sounds friendlier.
A Note On Panic Versus Preparation
Panic is a poor allocator. Preparation is boring and usually correct. Refiners issuing extra tenders are not panicking so much as doing the job. Households topping up heating oil a little earlier than last year are not being dramatic. Companies reviewing fuel surcharges are not inventing a crisis. They are reading the same cargo notices.
Could this fade? Yes. A restored pipeline section, a quieter shipping week, and a mild October would take the edge off. I would still treat the current signal as real. When a producer tells a region it will miss a month, the market should listen the first time.
The Human Texture Behind The Barrel Count
It is easy to talk in thousands of barrels a day and forget the texture. A dispatcher in Gdansk waiting on a substitute cargo. A German distributor wondering whether November heating oil offers still make sense. A trucking firm staring at a diesel invoice that no longer matches last quarter’s budget. Those people do not need a lecture on geopolitics. They need molecules on a calendar.
That is why the phrase “winter is coming” is more than a slogan here. Europe has lived through tight gas winters and learned how fast a technical shortage becomes a social argument. Diesel and heating oil can travel the same path if crude slates keep slipping.
Where This Leaves The Next Thirty Days
The next month is about confirmation. Either replacement barrels appear at a price Europe can live with, or the bid spills into November and December. Either the East-West system shows a credible recovery path, or traders treat Red Sea liftings as optional at best. Either distillate cracks ease on incoming supply, or they stay elevated and start dictating the conversation.
I keep coming back to a simple question. If a major supplier can pause a region for a month after one infrastructure hit, what does the second hit look like? Nobody wants that question. Markets still have to price it.
So here is the practical read. European refiners are short a familiar barrel at a familiar time of year. The workaround route is damaged. The sea lane that route was meant to avoid is still a problem. Crude is already north of $100. Diesel is already tight. That combination does not require drama. It requires attention.
If the repair news improves, the bid can unwind. If it does not, winter will not wait for a better model. The cargoes that do not load next month will be missed in the only way energy markets ever miss things: in the price, in the queue, and in the temperature of the argument that follows.