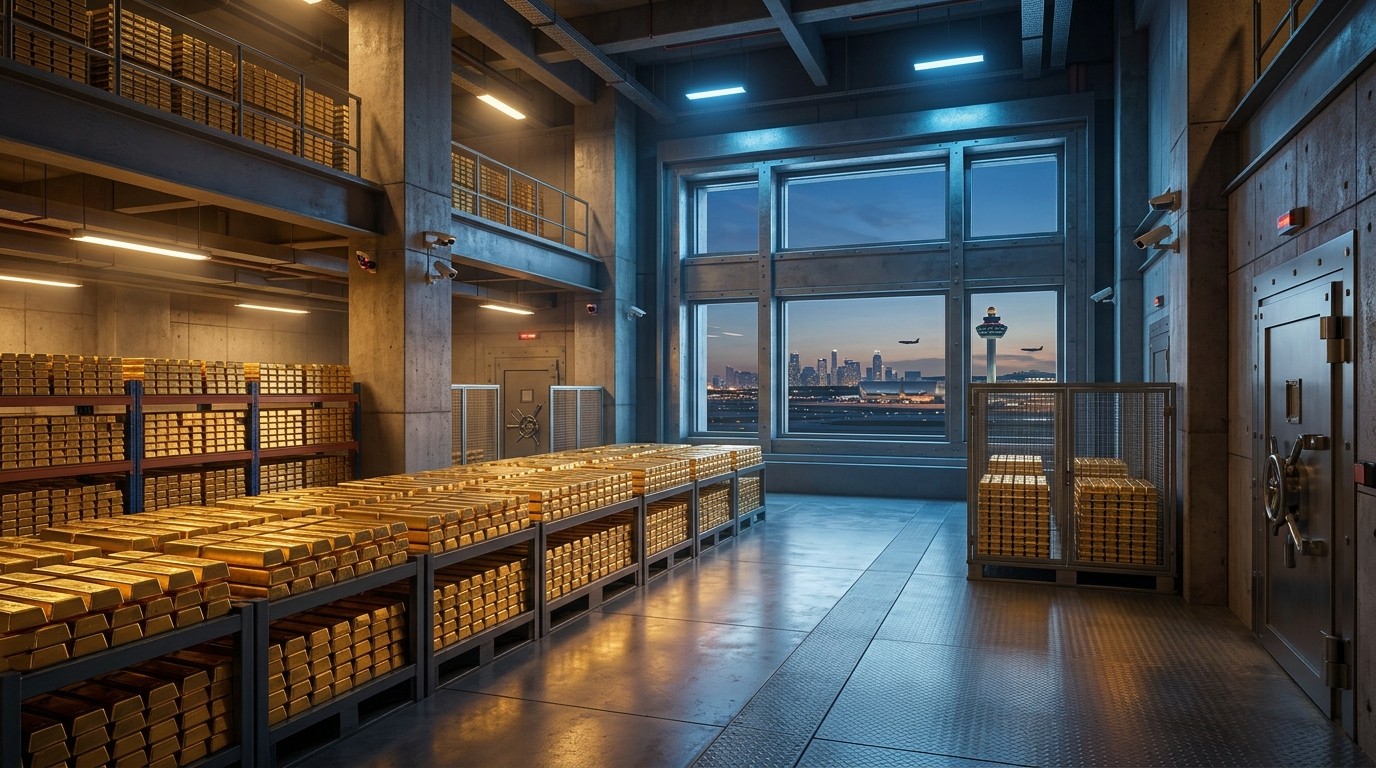

What if the safest place for your gold right now is not London or New York but a windowless building next to one of Asia’s busiest airports? That question stopped being theoretical this week. The Monetary Authority of Singapore opened its national currency vault to foreign central banks and sovereign entities, complete with space for roughly 500 tons of bullion and a package of tax relief designed to pull more wholesale gold business into the city-state. The move arrives just weeks after reports showed private investors from the United States, Europe and the Middle East already shipping bars east at a pace that has grown private holdings in Singapore more than sixteen-fold since 2014.
For three years the gold narrative centered on who was buying. In 2026 the conversation has shifted to where the metal actually sleeps at night. I’ve watched this migration for years, and the speed of the latest phase still surprises me. What started as a quiet preference among high-net-worth families has now reached official reserve managers. Singapore is no longer just a convenient stopover. It is becoming a serious contender for long-term custody.
Why Gold Is Quietly Moving East
The pattern is clear once you step back. Large volumes of gold have left the New York Federal Reserve over the past year and headed first to the Bank of England, then onward to other destinations. Some of that metal is now traveling farther east than London. Private vault operators in Singapore report that client gold under their programs has tripled since early 2020. One major facility near Changi Airport still has room for hundreds of tons, yet demand keeps climbing.
Wealthy individuals got there first. Estimates from bullion dealers put privately held gold in Singapore above 800 tons last year, with most of the recent increase coming from Europe. Web inquiries from Western clients have tripled in twelve months. The United States leads the list of origin countries, followed by Canada, the United Kingdom and Australia. Political uncertainty and fiscal deficits rank among the top reasons cited. European and American high-net-worth demand at certain platforms has risen about 25 percent. Roughly 40 percent of some European clients have either moved part of their Swiss holdings to Singapore or chosen the city-state for new purchases.
One private banker told me clients increasingly prefer dealing with Singapore entities rather than U.S.-based companies they used before. Another firm now offers physical custody in Singapore after repeated requests from Middle Eastern clients. The message is consistent: long-term holders want a jurisdiction that feels distant from the headlines that worry them.
What Long-Term Holders Actually Look For
People planning to leave gold untouched for thirty or forty years tend to apply a simple checklist. They look for a wealthy country without an obvious pension-system crisis and one that maintains credible defense capabilities. Singapore checks those boxes for many. The two largest private vaults in the city can hold at least 2,200 tons between them. One facility still had significant capacity earlier this year; another basement vault was nearly full by May.
Of course capacity figures can mislead. One operator’s storage program held only about 8.6 tons of client gold at last count, roughly 90 percent foreign-owned, against a 500-ton design capacity. The owner built for decades, not quarters. That long view may prove correct. Trust, once lost, is hard to rebuild. A jurisdiction that has not frozen anyone’s reserves lately holds an obvious advantage.
The New Sovereign Vault Changes The Equation
Private storage is one thing. A vault run by the central bank itself is another. The new facility will hold reserves for foreign central banks, international financial institutions and sovereign entities. The Monetary Authority will also open gold custody accounts for selected Singapore-based bullion banks so the metal can be put to work rather than simply locked away. Some central banks have already expressed interest, though officials decline to name them while talks remain confidential.
From April 2027 tax relief on gold expands to wholesale services between institutions: vaulting, refining, recasting, assaying and broking. An over-the-counter clearing system on the local exchange is scheduled by year-end, with several major banks as clearing members. Live trading is expected by March 2027 and deliverable kilobar futures in the second quarter. Officials frame the effort as an extension of Singapore’s role as a trusted financial centre rather than an attempt to replace existing hubs. That is the polite way of saying the infrastructure is being built to compete.
Asia already accounts for roughly 70 percent of annual consumer gold demand. The Monetary Authority itself participated in the heavy central-bank buying wave earlier in the decade, so it understands the customer base. A 500-ton vault represents meaningful capacity. At recent prices near four thousand dollars an ounce it holds tens of billions of dollars in metal, equivalent to several months of global official-sector purchases at current estimated rates.
Storage Dilemma Becomes Official Policy Debate
Market strategists flagged the storage problem months ago. Gold held at the Bank of England or the New York Fed sits inside the main settlement networks, offering immediate market access, dollar liquidity through swaps, and the ability to generate income through leasing. The drawback is political risk, including the possibility of freezing or restricted access. That risk once seemed theoretical for most reserve managers. It no longer does.
Surveys still show the Bank of England as the preferred custodian for a majority of reserve managers, yet the same managers are spreading bars more widely. Foreign central-bank gold at the New York Fed declined by tens of tons in a single recent month while holdings at the Bank of England rose by a similar amount. Faith in one traditional location appears to be eroding even as another gains. Meanwhile official buying continues at elevated levels. Monthly purchases remain well above the pre-2022 average, with a concentrated group of countries accounting for the bulk of activity year after year.
Every one of those buyers must store the metal somewhere. China is expanding its own vault network. Hong Kong is pushing hard to become a storage and trading center. Producers across Asia have begun keeping more metal at home. For a reserve manager who wants Asian exposure without placing assets inside China’s legal system, the new Singapore facility offers an obvious third option.
The official-sector debate has shifted from whether to own gold to where to store it.
That single sentence captures the change better than any chart. Emerging-market central banks led the diversification years ago. Concern about reserve security and cross-country trust is now visible among developed-market managers as well.
A Vault Alone Does Not Create A Market
Skeptics ask whether Singapore arrived late. On pure volume numbers the question is fair. Singapore imported more than 170 tons of gold through August, a solid year-on-year increase, yet London still holds many times that amount in storage and major futures warehouses hold hundreds of tons more. Storage capacity by itself does not make a bullion market. Liquidity does. Gold that can be lent, swapped and traded where it sits creates the network effects that keep London dominant.
That is why the custody accounts for bullion banks and the new clearing system matter more than the vault door. Without the ability to put metal to work, a sovereign vault remains a high-security warehouse. With those tools it becomes part of a functioning market. Officials understand the distinction. The timeline for clearing and futures shows they are trying to close the gap.
The launch also lands during a soft patch for the gold price. After a dramatic run earlier in the year the metal has pulled back sharply. Speculators reduced large futures positions in a short period. Some banks trimmed near-term targets while still expecting higher levels further out, based on continued official buying of roughly sixty tons a month. One interesting theory circulating among commodity desks links the recent weakness to energy prices: higher oil bills forced some emerging-market reserve holders to pause purchases or even sell. As energy costs ease, the funding pressure lifts and gold demand returns.
Whether that explanation holds, the broader custody theme remains intact. Central banks that were forced sellers or paused buyers under oil stress become natural buyers again once pressure eases. Trend-following models have been heavily short. The pain trade, if history is any guide, often points higher when positioning reaches extremes.
Private Demand Keeps Accelerating
While official institutions debate storage locations, private clients continue voting with their bars. Demand from Western high-net-worth individuals remains strong. Some platforms report that clients who previously favored Swiss storage are rethinking neutrality after watching sanctioned assets frozen elsewhere. Others simply want geographic diversification after years of concentrating holdings in one or two traditional centers.
The practical advantages are straightforward. Singapore offers political stability, strong rule of law, and a financial system that already handles large cross-border flows. The tax relief package for wholesale services lowers the friction of moving metal in and out. Custody accounts at bullion banks open the possibility of generating returns rather than pure storage costs. For families planning multi-decade holding periods, those details matter.
- Political distance from recent reserve freezes
- Expanding tax incentives for institutional gold activity
- Growing network of local custody and clearing services
- Proximity to the largest consumer gold markets in the world
- Reputation for long-term policy consistency
None of these factors guarantees success. Markets are path-dependent and London’s centuries of history create powerful inertia. Yet the direction of travel is hard to ignore. Private gold in Singapore has already scaled dramatically. Central banks are now being invited into the same ecosystem with sovereign-level custody.
How Large Is The Opportunity
A 500-ton sovereign vault is not enormous relative to total global stocks, yet it is large relative to monthly official buying. Six months of central-bank purchases at recent estimated rates would fill it. The New York Fed still holds many times that amount in foreign-owned gold, but the stock is shrinking. Even a modest share of metal leaving traditional Western locations would fill Singapore’s new capacity several times over.
Private vaults already demonstrate the appetite. One operator designed a facility with room for roughly 10 percent of annual world gold supply and 30 percent of silver supply. Another large freeport-style complex has operated near capacity. The private sector has proven the demand exists. The sovereign facility simply adds an official stamp and the possibility of deeper market integration.
I’ve found that gold tends to flow toward the jurisdictions that treat it best at any given moment. Right now that treatment includes tax relief, sovereign custody, and a location far from the political storms that worry many holders. Whether Singapore eventually rivals London on trading volume is almost beside the point. Capturing a slice of the metal currently leaving Manhattan, plus nervous European holdings that no longer feel fully secure in Switzerland, would be more than enough to fill the available vaults.
Timing And Price Context
The current price environment adds an interesting layer. Gold trades well below its earlier peak after a period of heavy speculative selling. Some analysts view the weakness as temporary, driven by positioning and by the temporary funding pressure from higher energy costs. Others note that most institutional clients still rank gold near the top of assets they want to own, even if they are not adding today.
For long-term storage decisions the day-to-day price is secondary. A family or central bank deciding where metal will sit for decades cares more about jurisdiction risk than about the next hundred dollars of movement. That is why the custody migration continues even while the price consolidates. The metal is being re-domiciled in real time: out of New York, around traditional Swiss locations, toward places that have not recently restricted access to reserves.
Perhaps the most interesting aspect is how quickly preferences can shift once a credible alternative appears. For years the default answer was London or New York. The defaults are now being questioned. Singapore’s combination of private infrastructure already in place and a new sovereign vault with accompanying market tools arrives at a moment when those questions are loudest.
What Reserve Managers And Private Clients Share
At first glance central banks and private wealth appear to operate in different worlds. One manages national reserves; the other protects family capital. Yet the concerns overlap more than many realize. Both groups want the metal to remain accessible when needed. Both prefer jurisdictions that demonstrate long-term reliability. Both notice when other countries’ assets are frozen. And both are willing to pay for geographic diversification once the cost of concentration becomes visible.
Singapore is pitching to both audiences at once. The sovereign vault and custody accounts target official institutions. The existing private vaults and tax incentives already serve high-net-worth clients. The clearing system and futures contracts aim to create the liquidity that keeps metal useful rather than merely stored. It is a coherent package.
Success is not guaranteed. Building market depth takes time. Clearing systems need volume to become self-reinforcing. Trust is earned slowly and lost quickly. Still, the starting conditions look favorable. Private demand is already present. Official interest has been expressed. Asia remains the largest end-user market. And the broader trend of gold leaving traditional Western custody locations shows no sign of reversing.
Looking Ahead
The next few years will reveal whether Singapore’s bet pays off. The clearing system is due soon. Tax relief arrives in 2027. Futures contracts follow. Central banks that have expressed interest will either open accounts or stay with existing arrangements. Private inflows will either continue their recent pace or moderate.
What seems unlikely is a return to the old status quo in which nearly all allocated gold sat in a handful of Western vaults. The re-domiciling process is already underway. A 500-ton facility near Changi Airport is only one piece of a larger shift. Gold, as it always has, moves toward the places that currently treat it best. For a growing number of holders that place looks like Singapore.
In my view the story is less about any single vault and more about the quiet recalculation of political risk. When wealthy families and central banks begin asking the same questions about storage at the same time, the answers tend to reshape markets. Singapore has positioned itself to capture part of that recalculation. The metal is already arriving. The infrastructure is being finished. The rest will depend on execution and on how long the current preference for geographic diversification lasts.
For now the direction is clear. First the world’s rich, then its central banks, are sending gold to Singapore. The new sovereign vault simply makes the second half of that journey official.