

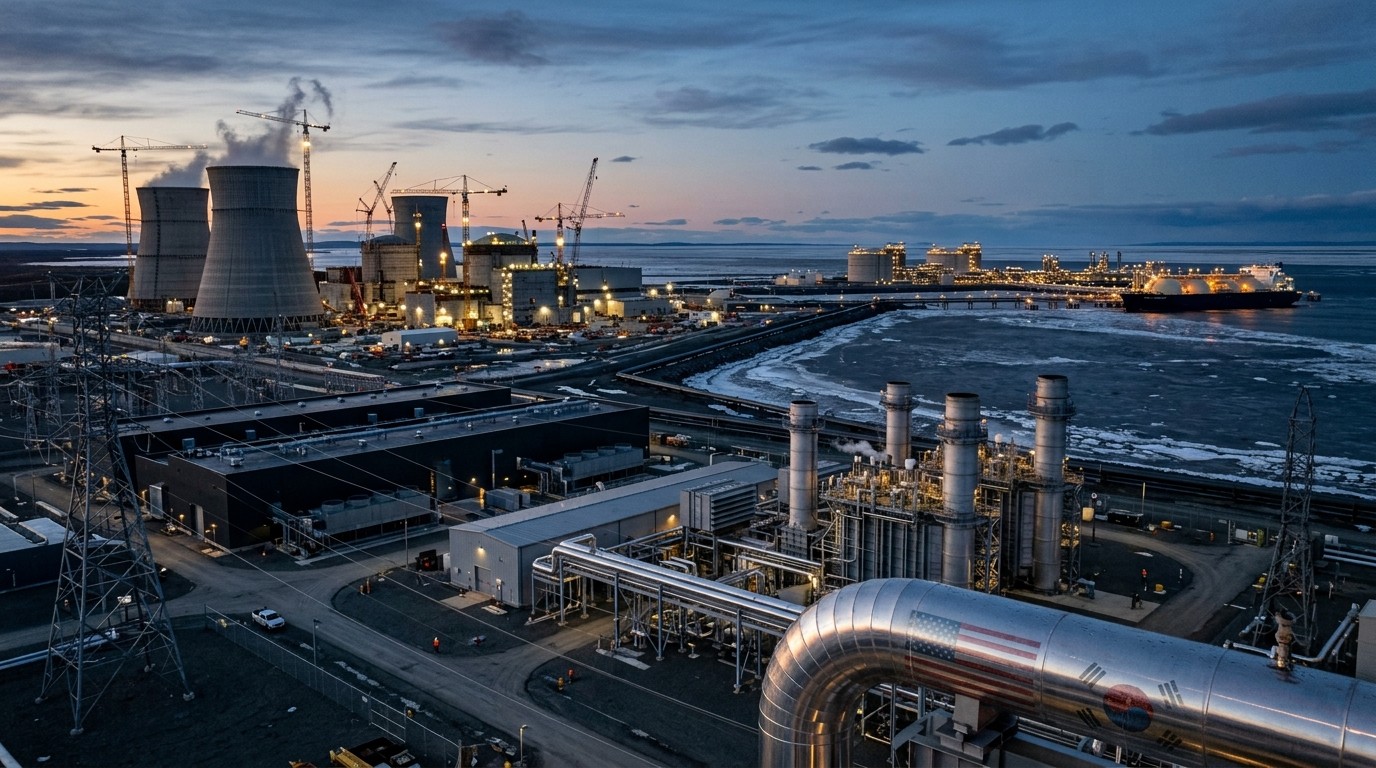
South Korea $200 Billion U.S. Energy Investment Plan

Washington just framed a $200 billion Korean package as historic U.S. energy spending. Nuclear money is mapped. Texas gas is named. Alaska LNG is still hanging. The fine print is where the story gets interesting.
Financial market analysis from 01/10/2026. Market conditions may have changed since publication.
Have you ever watched a political announcement land with a round number so large it almost feels abstract? Two hundred billion dollars is that kind of figure. It is big enough to sound historic, and vague enough that you still have to ask what, exactly, is being bought. That is the tension sitting under the latest U.S.–South Korea energy package. The White House framed it as one of the largest energy infrastructure pushes in American memory. Seoul, meanwhile, has been more careful about which pieces it will actually underwrite.
What The $200 Billion Pledge Really Covers
The headline is simple. South Korea is prepared to invest up to $200 billion across U.S. energy projects. The tone from Washington was triumphant. New plants. New manufacturing. Tens of thousands of jobs. Power for a country that suddenly cannot build generation fast enough. I have found that these ceremonies always sound cleaner than the contracts that follow.
Look closer and the package splits into three buckets that do not carry the same degree of certainty. One is a giant gas-fired plant in Texas tied to data centers. Another is a nuclear construction program with a published cost split. The third is the long-debated Alaska LNG corridor, which still sits in the “maybe, if the numbers work” pile. That last point matters. A pledge is not the same thing as a final investment decision.
In my experience, investors should treat the $200 billion figure as an envelope, not a wire transfer. Some of it is construction capital. Some is contingency. Some is still contingent on commercial reasonableness, legal review, and whether the cash flow story holds up once engineers and lenders get a longer look.
The Texas Gas Plant And The Data Center Rush
The most concrete near-term project is a 6,472-megawatt natural gas facility in Encinal, Texas. The published price tag is about $22.3 billion. Related Companies and NextEra Energy are slated to lead development. First power is targeted for 2029, with the rest coming online in stages through 2032.
Why Texas? Because the state’s grid is already straining under industrial load, and data centers do not wait politely for the next decade of transmission planning. Co-located generation is the current workaround. Put the plant next to the compute campus. Keep the electrons close. Reduce the chance that a congested line becomes the bottleneck.
These are massive energy projects, adding power capacity in the United States. This is new construction, new manufacturing, and great jobs for American workers.
That is the political framing. The industrial framing is a little less poetic. Turbines, heat recovery steam generators, switchyards, water, gas supply, and a construction schedule that has to survive permitting, labor availability, and equipment queues. Korean firms want a larger slice of that supply chain: equipment, engineering, construction, then long-term operations and maintenance. Washington says it intends to open similar opportunities on other U.S. projects, including turbine supply.
Is that a gift to Seoul or a necessity for the United States? A bit of both, if we are being honest. American developers need capital and execution partners. Korean industrials want export work and a foothold in a market that is suddenly hungry for firm power. I do not buy the idea that this is charity. It is a trade.
Eight Reactors And A $120 Billion Nuclear Envelope
The nuclear piece is larger and more ambitious. Roughly $120 billion is mapped to plans for eight large-scale reactors in the United States. Of that, $100 billion is described as construction cost and $20 billion as contingency. Contingency is not decoration. Nuclear projects eat contingency for breakfast.
The arrangement was signed by both governments along with Westinghouse Electric, Korea Electric Power Corp., and Korea Hydro & Nuclear Power. There is also language about a potential significant minority investment in Westinghouse by Korean companies, with terms left to commercial negotiation. That last clause is doing a lot of work. Minority stakes live or die on valuation, governance, technology rights, and export-control comfort.
Perhaps the most interesting aspect is the attempt to stitch Korean execution culture onto an American licensing and labor environment. South Korea has a reputation for building reactors with tighter schedules than many Western peers. The United States has a reputation for turning first-of-a-kind nuclear into a calendar that never ends. Combining those two instincts is the whole bet.
- Eight large reactors as the headline build-out
- $100 billion tagged to construction
- $20 billion held as contingency reserves
- Possible Korean minority stake in Westinghouse
- Vendor access for Korean suppliers on U.S. sites
Will eight plants actually get built? That is the question nobody can answer from a ceremony. Sites still need to be chosen, communities still need to be persuaded, and regulators still need to bless designs that can be repeated rather than reinvented. Repeatability is the secret sauce. One custom reactor is a science project. Eight similar units can become an industrial program.
Alaska LNG Is The Unfinished Chapter
Then there is Alaska. The project would move gas about 1,300 kilometers from the North Slope to a southern liquefaction site for export, including to Asian buyers. On paper it is elegant. Stranded northern gas. Hungry Asian markets. A long steel line tying them together.
In practice it has been a high-cost dream for years. The upfront bill is huge. The commercial case depends on long-term offtake, construction discipline, and prices that do not collapse after the pipe is in the ground. South Korea has not closed the door, but it has not signed a blank check either. Officials have previously called the venture high-risk unless cash flow looks durable.
Washington’s public comments have been warmer than Seoul’s. One late-night post from the U.S. side even attached a $50 billion value to cooperation on the project. The joint language was cooler: participation would depend on commercial reasonableness, with no clean allocation published. That gap is not a rounding error. It is the story.
A pipeline-and-terminal complex only becomes an investment after lenders believe the gas will keep moving at a price that pays for steel, interest, and risk.
The United States says it will help Korean vendors and suppliers get favorable involvement if the project proceeds. That is useful. It is not the same as making the project economic. Geography is stubborn. Arctic construction is expensive. Distance is expensive. And Asian buyers have other supply options, from existing Pacific cargoes to new projects elsewhere.
Why Seoul Would Write A Check This Large
South Korea is an energy importer with sophisticated builders and a crowded domestic market. Exporting engineering talent is not a side hobby. It is a growth strategy. Nuclear, gas turbines, construction management, and long-term plant services are all businesses Seoul already understands.
There is also the alliance layer. A large U.S. investment package is a political signal as much as a spreadsheet. It says the relationship is not only about security guarantees and trade friction. It is about capital landing on American soil. I’ve found that governments like visible projects they can point to when talks get tense. A reactor site and a Texas power yard are visible.
Does that mean every dollar is strategic rather than commercial? No. Korean firms still have to earn a return. Boards still have to defend capex. Lenders still ask ugly questions about schedule slippage. The romance of a summit does not survive a delayed turbine delivery.
What Washington Wants In Return
The U.S. pitch is straightforward. The country needs megawatts, and it needs them faster than the current domestic pipeline is delivering. Data centers, factories, electrified transport, and a grid that has retired older plants all pull in the same direction. Gas peakers and combined-cycle units can be built quicker than nuclear. Nuclear, if it finally scales, offers long-duration firm power without the same fuel-price swings.
Jobs are the political glue. Construction payrolls are local. So are many operations roles once a plant is running. “Tens of thousands” is a phrase that travels well in a press event. The real number will depend on how many projects clear financing and how much work stays onshore versus being imported as prefabricated modules.
There is also a vendor story. If Korean companies supply turbines, nuclear components, and construction services, American sites get extra execution capacity. That can be a feature. It can also become a political flashpoint if domestic manufacturers feel crowded out. Trade policy and industrial policy are sharing the same room here, whether anyone admits it or not.
How The Money Appears To Break Down
Public figures are not a full capital stack, but they are enough to sketch the shape of the package. Think of it as a map with a few bold roads and several dotted lines.
| Workstream | Published Scale | Status |
| Texas gas plant | $22.3 billion, 6,472 MW | Named developers, staged 2029–2032 |
| U.S. nuclear program | $120 billion for eight large reactors | Government-industry agreement, sites still open |
| Alaska LNG | Discussed around $50 billion by U.S. side | Not finalized, commercial tests pending |
| Broader envelope | Up to $200 billion | Headline commitment, mixed certainty |
Notice what is missing. There is no public year-by-year cash schedule. No published offtake book for Alaska. No reactor-by-reactor site list. Those absences do not make the announcement fake. They make it early.
Commercial Reasonableness Is Doing Heavy Lifting
That phrase, commercial reasonableness, is the adult in the room. It lets both governments celebrate while leaving financiers an exit. If a project cannot generate enough cash, Seoul can step back without ripping up the whole relationship. If a project can, Washington can claim the ribbon-cutting later.
I like that honesty, even if it is wrapped in diplomatic cotton. Energy infrastructure is not a souvenir. It is a multi-decade claim on fuel, water, land, and ratepayers or offtakers. Pretending otherwise is how countries collect stranded assets.
So the right question is not “Did they announce $200 billion?” The right question is “Which pieces can clear a credit committee?” Texas gas serving contracted data-center load has a cleaner path than an Arctic export line with a long construction tail. Nuclear sits in the middle: politically beloved, technically proven in other markets, still schedule-sensitive in this one.
Power Demand Is The Quiet Character In This Drama
None of this would be happening at this volume if U.S. electricity demand were sleepy. It is not. Compute clusters are landing in places that already have cheap land and friendly local rules. Those clusters drink power all day. They want firm supply, not a motivational speech about future transmission.
That is why a Texas plant co-located with data centers is more than a local story. It is a template. Build generation next to load. Sign long contracts. Keep the politics of interstate lines at arm’s length. Other states will copy the model if it works, and fight it if communities decide the tradeoffs are ugly.
Nuclear enters the same conversation from the other side of the clock. Reactors are slow to start and long to run. If the United States is serious about adding carbon-free baseload at scale, it needs more than one demonstration unit and a pile of speeches. Eight plants would be a program. A program can create a workforce. A one-off cannot.
The Job Claim, Without The Gloss
Job estimates in energy politics are a genre of their own. Construction employment spikes, then fades. Permanent plant jobs are fewer, better paid, and more specialized. Supply-chain jobs depend on whether components are poured, welded, and assembled in the United States or shipped in.
- Count peak construction roles separately from long-run operations.
- Ask how much fabrication stays onshore.
- Watch local housing and wage pressure near big sites.
- Separate temporary contractor work from lasting apprenticeships.
If Korean construction methods travel well, schedules could tighten and local hiring could still be large. If the work depends on imported modules, the employment story gets thinner. Neither outcome is automatically good or bad. It is just the thing to measure instead of applauding a round number.
Risks That Can Still Knock The Package Off Course
Let’s not pretend the path is smooth. Permitting can slip. Lawsuits can stall a corridor. Nuclear cost overruns are not ancient history. Gas plants face fuel-basis risk and future climate rules. Data-center offtakers can change expansion plans. Exchange rates can move against a foreign investor. Domestic politics can sour if a project looks more imported than advertised.
Alaska adds weather, distance, and a customer set that can buy elsewhere. A “high-risk” label from Korean officials last year was not theater. It was a warning that the project has to stand on cash, not on summit lighting.
There is also sequencing risk. If the Texas plant moves and the reactors linger, the $200 billion slogan starts to look lopsided. If Alaska never closes, the export narrative weakens. Markets notice which line items get steel in the ground.
What Investors Should Watch Next
Ceremony days are for flags. The next six to eighteen months are for paper. Site control. Interconnection. Engineering, procurement, and construction contracts. Offtake. Contingency draws. Any filing that turns a memorandum into a financed asset.
For the nuclear track, watch whether the Westinghouse minority-investment talk becomes a term sheet. Watch whether the eight-reactor plan collapses into two or three real sites. Watch labor agreements. Nuclear is a people business disguised as a concrete business.
For Texas, watch the data-center contracts. A plant of that size needs counterparties who will still be expanding in 2030. Nameplate megawatts are vanity until someone is obligated to pay for them.
For Alaska, watch whether Korean buyers or builders put a number on volume, price, and equity. Until that happens, treat $50 billion as a talking point with boots still in the closet.
Rough mental model:
  Texas gas  = fastest path to electrons
  Nuclear    = largest long-run capacity bet
  Alaska LNG = highest uncertainty, export optionality
A Few Personal Reads On The Politics
I keep coming back to the mismatch in tone. Washington wanted a monument. Seoul wanted optionality. Both can be true at once. That is how allied industrial policy often works. You announce a ceiling. You negotiate the floor later.
Is the package “one of the largest energy infrastructure investments in American history”? It could be, if the nuclear program is built and if Alaska somehow clears its own commercial fog. If only the Texas plant and a thinner nuclear start survive, it is still large, just not mythic. Precision beats adjectives.
Another quiet point: foreign capital in U.S. energy is not new, but the pairing of nuclear know-how with gas-for-compute is very 2020s. The last cycle obsessed over pipelines and export terminals. This cycle obsesses over who can keep the lights on for machines that never sleep. Different era. Same hunger for firm power.
What This Means For Households And Local Economies
People far from Encinal or a future reactor county may shrug. They should not, entirely. Big generation additions can ease wholesale tightness, which eventually shows up in bills, reliability, and industrial siting. They can also concentrate impacts: traffic, housing crunches, water use, and a skyline of cranes that locals did not vote on in a national press event.
Communities that host plants often live the trade first. Tax base up. Services strained. Night-shift traffic. A promise of permanent jobs that arrives after years of dust. If developers want consent, they will need more than a national jobs slogan. They will need local detail.
Export projects cut a different way. Alaska LNG, if it ever happens, is about royalties, construction camps, and a global gas market that most households never see. The benefit is fiscal and industrial. The risk is building a monument to a price deck that has already moved on.
The Supply Chain Quietly Becomes The Real Contest
Ignore the ribbon for a minute and look at who makes the parts. Turbines. Pumps. Nuclear-grade steel. Control systems. Welding procedures. Those are the scarce goods. A government can announce capacity. It cannot conjure a qualified welder from a press release.
That is why the language about Korean vendors matters. The United States is trying to import not only money but throughput. South Korea is trying to export a mature industrial machine into a market that has talked about reindustrialization for years and is now being forced into it by load growth.
If that marriage works, other countries will copy the template: capital plus contractors plus a political blessing. If it fails, the $200 billion line will live on as a cautionary slide in somebody’s conference deck.
Separating Signal From Ceremony
So where does that leave a reader who is not paid to clap? Start with the Texas plant. It has developers, a megawatt figure, a dollar figure, and a staged in-service window. That is signal. Move to nuclear. It has a cost envelope and named industrial partners, but not a public site list. Mixed signal. Then Alaska. Aspiration with a commercial lock still on the door.
Hold the $200 billion number in your head as a maximum ambition. Track the first dollars that are hard to reverse: land, long-lead equipment, labor-framework deals. Those are the tells. Everything else is atmosphere.
And yes, atmosphere has value. Markets move on confidence. Allies notice who gets invited into strategic industries. Workers notice which trades are hiring. Just do not confuse a well-lit room with a completed switchyard.
A Closing Read, Without The Fairy Dust
This package is best understood as a bet that American power scarcity is durable and that Korean industry can help fill it. On that narrow point, I think the diagnosis is right. The country needs electrons. Seoul has builders. Texas needs dispatchable supply near new load. Nuclear needs a production rhythm instead of another isolated struggle.
The rest is negotiation dressed as destiny. Alaska may join the family or stay a postcard. Contingency reserves may get spent twice. A minority stake in a nuclear vendor may close, stall, or shrink. That is normal. Big energy is messy even when the speeches are tidy.
If you remember one thing, remember this: the announcement created a map. The next two years will decide which roads get paved. Watch the Texas schedule, the first reactor sites, and whether Korean capital still likes Alaska when the consultants finish their homework. The headline was $200 billion. The story that matters is which slice becomes steel, concrete, and power you can actually meter.
Wealth is not about having a lot of money; it's about having a lot of options.


Apple Foldable Iphone Sales Forecast Faces A $2000 Test

Oil Prices Near $100 Keep Holiday Airfares Elevated
Related Articles
Key Market Movers: Stocks and Trends to Watch
Tuesday’s market is heating up with major earnings and inflation data. Which stocks will soar or stumble? Dive into the trends shaping your investments...

Monthly Performance Reviews For Senators Could End Gridlock
What if senators faced a quiet monthly verdict from their own voters? Not a real election, just a public score that could change everything about how Congress works. The idea sounds extreme until you see how little gets done between campaigns.

What’s Wrong With Palantir Stock? Investor Views Explained
Palantir was meant to thrive in the AI era, yet its stock has dropped sharply while the broader tech sector struggles. What are investors missing, and isGenerating the final XML output the fear over AI competition justified? The answers might surprise you...