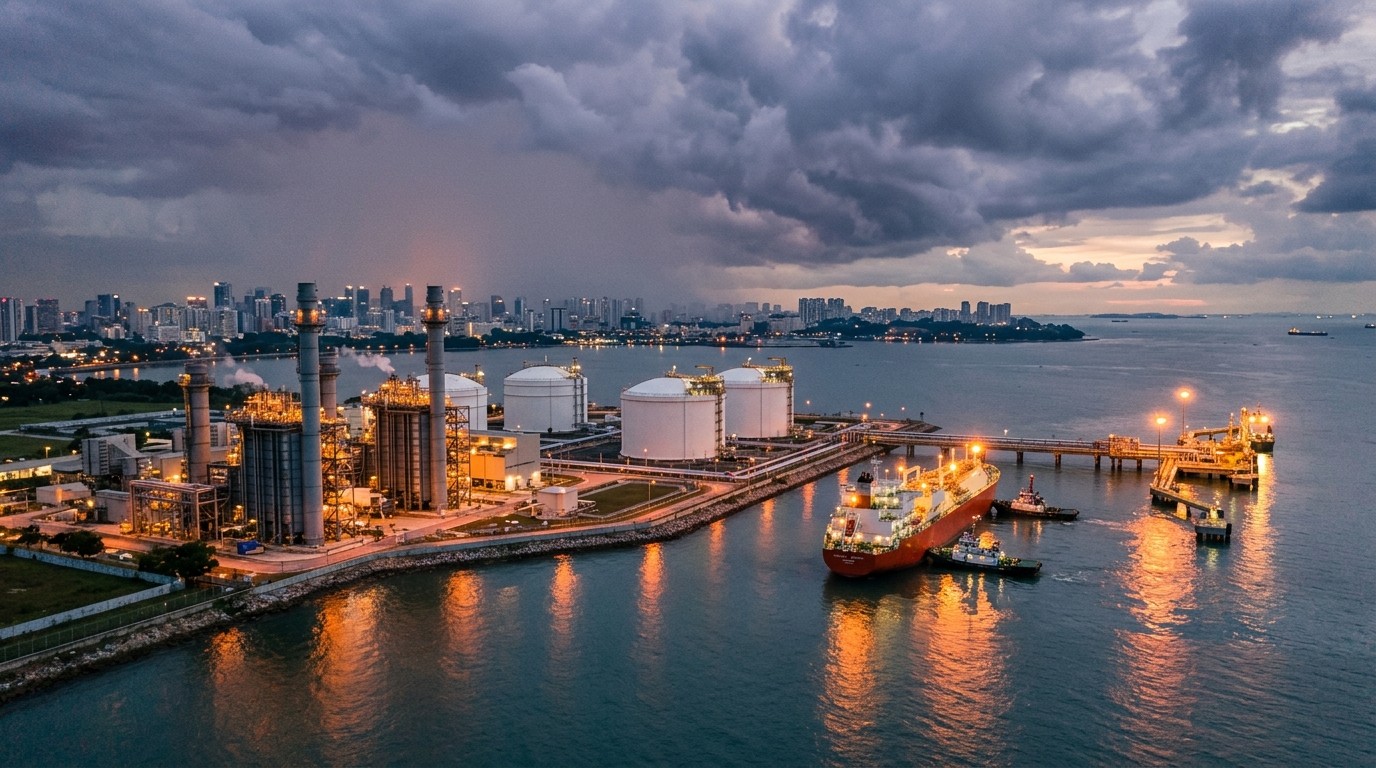

Have you noticed how some energy plans refuse to blink, even when the market slaps them in the face? That is the strange feeling hanging over Southeast Asia right now. A supply shock tied to the Strait of Hormuz has tightened liquefied natural gas availability, shoved prices higher, and forced more than a few buyers to think twice. And yet the region keeps pouring foundations for gas-fired power plants and new import terminals as if the last months were a passing squall rather than a warning.
Why The Region Still Bets On Gas After The Shock
I keep coming back to one simple tension. Electricity demand in much of Southeast Asia is still climbing. Factories want reliable power. Cities keep spreading. Air conditioning is no longer a luxury in a hotter climate. Coal is politically heavier than it used to be. Renewables are growing, but they do not yet cover evening peaks or the kind of industrial load that hates surprises. So gas looks like the grown-up compromise. Flexible. Cleaner than coal on paper. Easier to permit than a new nuclear plant. Familiar to utilities that already know how to run turbines.
That logic held when cargoes were plentiful and prices were calmer. It looks shakier now. The war in the Persian Gulf has stretched into its seventh month. Available liquefied gas has tightened. Prices have jumped. Some Asian buyers have lost their appetite, at least at the spot window. Still, construction has not paused in any dramatic way. Analysts tracking project pipelines put roughly 100 GW of new gas-fired generation under construction across the region, with about 70 GW of equivalent LNG import capacity also moving forward. Those are not napkin sketches. They are steel, concrete, and multi-year capital.
The continued expansion of LNG import infrastructure risks deepening exposure to the same supply disruptions and price volatility the crisis has brought to the fore.
That line from energy researchers is the heart of the debate. More terminals can mean more optionality. They can also mean a deeper habit. Once a grid is built around imported molecules, those molecules have to show up. If they do not, the bill arrives in two forms: higher electricity costs and awkward political explanations.
The Three Assumptions Holding The Whole Plan Together
Much of the remaining planned expansion rests on three beliefs. First, that LNG will stay reliably available. Second, that it will stay cheap enough to compete with other fuels. Third, that domestic gas can act as a backup when imports get tight. I am not sure any of those three is as sturdy as project sponsors would like. Availability is a geography problem as much as a geology problem. Affordability is a market problem. Domestic fallback is a timing problem. Put them together and you get a strategy that works in a friendly decade and strains in an ugly one.
Take availability. Asia is already the world’s largest LNG buyer. For years that demand pulled new export projects into existence. Fine, until a chokepoint gets messy. A large share of seaborne energy still moves through the Strait of Hormuz. Even a partial disruption changes the math for cargoes that were supposed to be “just there.” Shipping routes lengthen. Insurance climbs. Traders get picky. Cargoes that looked routine start looking like prizes.
Affordability is the quieter assumption, and maybe the more dangerous one. Plenty of plants were conceived when gas looked like a mid-priced, mid-risk fuel. After a shock, the same plant can become a high-priced, high-risk asset. Utilities can try to pass costs to consumers. Governments can try to subsidize the gap. Neither option is free. One hits households. The other hits budgets. In my experience watching these cycles, the political patience for both runs out faster than developers expect.
Then there is the domestic fallback. Researchers have identified at least twenty fields that could add around 62 billion cubic meters a year of production capacity by 2035. That sounds comforting until you remember how long a field takes to move from discovery talk to actual molecules in a pipeline. New supply takes years. Some of it may not even land in domestic power markets. Export contracts, fiscal terms, and pipeline politics have a way of steering gas toward the highest bidder, not the nearest turbine.
How Demand Growth Keeps The Cement Mixers Running
It would be easy to mock the region for ignoring a price spike. That would also be lazy. Power planners do not live in the spot market the way traders do. They live in load forecasts. Vietnam, Thailand, Indonesia, the Philippines, Malaysia, and several neighbors are not staring at flat demand curves. Data centers, manufacturing relocation, urban cooling, and electrified transport all pull in the same direction. You can dislike gas and still admit that a grid with rising peak load needs something dispatchable.
Renewables help on sunny or windy hours. Batteries help on short gaps. Hydropower helps where the rain cooperates. None of that fully replaces a turbine that can ramp when a factory line cannot wait. So the construction boom is not only inertia. It is also a bet that growth will outrun volatility. Maybe it will. Perhaps the most interesting aspect is how rarely that bet is stress-tested against a multi-quarter price regime rather than a one-month scare.
- Rising industrial load that needs stable baseload and mid-merit power
- Urban cooling demand that spikes on the hottest afternoons
- Policy pressure to reduce coal’s share without accepting blackouts
- A preference for technologies utilities already know how to operate
- Long lead times that make yesterday’s plan tomorrow’s construction site
Those five drivers explain a lot. They do not excuse weak risk planning. A region can need more power and still choose poorly among the ways to get it. That is the uncomfortable middle ground this story occupies.
Import Terminals Look Like Insurance Until They Do Not
LNG terminals are sold as flexibility. In a calm market, that sales pitch is honest. A terminal lets a country tap global supply, diversify away from a single pipeline, and buy when the price looks decent. In a shocked market, the same steel can become a magnet for expensive cargoes. You built the dock. The ship still has to want to stop there. Sellers know who is desperate. Buyers with thin storage and thin political room pay up.
I have found that people talk about import capacity as if it were a tap. It is more like a reservation at a crowded restaurant. Having a table does not mean the kitchen has food. Having a terminal does not mean the Atlantic or Pacific basin will spare you a cargo at last year’s price. When Europe, Northeast Asia, and emerging Asian buyers lean on the same flexible supply at the same time, the “optionality” story gets thinner.
There is also a lock-in effect that rarely makes the brochure. Once terminals and gas plants are financed, the incentive is to use them. Idle infrastructure looks like a mistake. So operators run the plants, sign more contracts, and tell the public that gas is the bridge fuel. Bridges are useful. Bridges that keep getting longer start to look like destinations.
Domestic Gas Is A Real Option, Just Not A Fast One
Could Southeast Asia produce more of its own gas and lean less on imported LNG? In principle, yes. The resource base is not empty. Offshore developments, associated gas from oil fields, and some onshore prospects still matter. The catch is calendar time. A field that “could” add volumes by 2035 does not help a utility facing a 2026 price spike. Investors want fiscal stability. Communities want a say. Pipelines need rights of way. Processing plants need water, power, and permits. None of that happens because a think tank wrote a hopeful sentence.
Even when molecules arrive, they may not stay home. Export projects can look more attractive than discounted domestic sales. Governments then face a familiar choice: earn hard currency abroad or keep cheaper fuel for local power. Both answers have constituencies. Neither is automatic. So the idea of domestic gas as a neat fallback is only half true. It is a possible future, not a switch on the wall.
| Risk Layer | What Planners Hope | What A Shock Reveals |
| Supply availability | Cargoes keep arriving on schedule | Chokepoints and shipping risk reprice every voyage |
| Price competitiveness | Gas stays cheaper than the next best option | Spot spikes make plants look expensive overnight |
| Domestic backup | Local fields fill any import gap | New fields take years and may chase export markets |
| Political cover | Voters accept gas as a clean bridge | Bills rise and the bridge story wears thin |
Look at that table long enough and the pattern is obvious. The plan is internally consistent if the world cooperates. The world has not been in a cooperating mood.
Price Memory Is Short, Concrete Memory Is Long
Markets forget pain with embarrassing speed. A few months of lower prices and the old slide decks come back out. Construction schedules do not forget. A plant that reaches financial close during a calm window still has to live through the next storm. That mismatch is how systems get overbuilt around a fuel that later feels dear.
I do not think every gas project in the region is a folly. Some replace dirtier plants. Some sit next to existing pipelines and make operational sense. Some serve industrial clusters that cannot wait for a perfect grid. The issue is the stack. One sensible project is not the same as 100 GW of simultaneous faith. Scale changes the risk. At that size, a region is not dipping a toe in LNG. It is wading in.
There is a human texture to this as well. Ministers get judged on blackouts, not on elegant energy-transition essays. A dark city is a career event. A slightly dirtier kilowatt-hour is a press release. So of course the default is a technology that starts when you press a button. Familiarity is a policy. It just does not show up in the slogan.
What “Affordable Enough” Really Means For Households
Affordable is a slippery word in energy. Affordable compared with what? Last year’s tariff? A coal plant that nobody wants to admit still runs? A renewable-plus-storage package that looks cheap in a model and late in real life? When LNG prices jump, the first victims are not always the utilities. They are families who see the bill and companies that run night shifts. If governments cap retail prices, the loss migrates into state budgets or delayed maintenance. Somebody pays. The only question is who holds the invoice.
That is why the second assumption, the one about prices staying competitive, deserves more suspicion than it gets. A fuel can be competitive on a five-year average and brutal on a twelve-month stretch. Power systems feel the stretch. Factories feel the stretch. Voters feel the stretch. If planners only model the average, they are planning for a climate that does not exist.
A power system can survive a high price. It struggles to survive a high price that nobody budgeted for.
That is not a proverb from a textbook. It is just how politics works when the meter keeps spinning.
The Quiet Contest Between Gas, Coal, And Faster Alternatives
Every extra gas plant is also a statement about what will not get built, or at least not soon. Money, grid connections, and political attention are finite. If a country commits to a wave of turbines, it may slow a wave of storage, transmission, or demand-response programs that would have reduced the need for imported molecules. I am not arguing that gas should vanish tomorrow. I am arguing that “bridge” language can hide a crowding-out effect.
Coal still lurks in the comparison. In a price spike, some operators will burn more of it if the rules allow. That is the awkward environmental footnote. A strategy sold as cleaner can, under stress, revive the fuel it was meant to displace. Not always. Often enough to matter. Energy security and climate policy share a spreadsheet more often than activists like to admit.
- Ask whether the plant is replacing coal or simply adding capacity on top of it.
- Check how much of the fuel plan depends on spot cargoes rather than long contracts.
- Test the project against a year of elevated prices, not a week.
- Map which domestic fields can actually reach the same grid in time.
- Put a political price on higher household bills before the first turbine spins.
Those steps sound obvious. They get skipped because they slow ribbon-cuttings. Ribbon-cuttings photograph well. Risk registers do not.
Contracts, Cargoes, And The Illusion Of Control
Long-term contracts are supposed to solve volatility. Sometimes they do. They can also lock a buyer into a price that looks clever in one year and painful in the next. Destination flexibility, oil-linked formulas, and hybrid indexes all sound sophisticated until a crisis rearranges the basis. Then everyone rediscovers that a contract is only as good as the counterparty’s ability and willingness to deliver under stress.
Spot buying is the opposite gamble. It keeps options open and exposes the treasury when the market tightens. Many systems mix both. That mix is rational. It is not a shield. During a Hormuz-style shock, both the contracted world and the spot world can get expensive at once, just through different doors. Freight, insurance, and delayed loadings do not care which box you ticked on the procurement form.
In my view, the region’s real vulnerability is concentration of timing. Too many terminals and plants arriving while the geopolitical weather is ugly. If those projects had been staggered through a calmer decade, the same megawatts might look prudent. Clustered together, they look like a chorus singing the same note.
What A More Honest Buildout Would Admit
An honest plan would say the quiet parts out loud. Gas can cut emissions versus coal in many operating profiles. It can also import someone else’s risk. Terminals create options and obligations. Domestic fields are promising and slow. Prices will not stay polite because a brochure needs them to. If those sentences appeared in more official documents, the public debate would be less surprised the next time a cargo costs more than last year’s budget.
It would also help to talk about demand with more humility. Efficiency, industrial self-generation, better transmission, and smarter peak pricing do not generate the same ceremony as a new plant. They still change the amount of imported fuel a country needs. A megawatt saved in the late afternoon is a cargo you may not have to beg for later. That is unglamorous. It is also cheaper than discovering flexibility after the fact.
Investors Should Watch Utilization, Not Just Capacity
From a markets angle, the story is not only about energy security. It is about capital that needs a return. A gas plant that runs hard in a high-price world can look profitable and still leave the host country poorer. A terminal that sits underused after a demand scare can strand equity. Capacity headlines are easy. Utilization is the adult metric. If imported fuel stays dear, some of those 100 GW will not dispatch as often as the models promised. That is how “strategic infrastructure” becomes a spreadsheet argument.
Lenders will ask sharper questions now than they did when prices were sleepy. Good. They should ask who eats the basis risk. They should ask what happens if a key transit route stays tense for another year. They should ask whether domestic production is a genuine hedge or a slide-deck hedge. Those questions will not stop every project. They might stop the weakest ones. That would be a feature, not a tragedy.
I keep thinking about the phrase energy analysts used: the war is putting the region’s gas expansion to the test. Tests are useful if you read the results. The early result is not that Southeast Asia has abandoned gas. It is that the region is trying to grow through a shock instead of around it. Brave, maybe. Also stubborn.
The Next Year Will Decide If This Looks Visionary Or Costly
If shipping calms, if new export projects land on time, if prices ease back into a range that factories can live with, today’s construction wave will be remembered as prudence. If the opposite happens, the same wave will be remembered as a doubling-down at the wrong moment. Both futures are still live. That is why the story is not a morality play. It is a timing play with national consequences.
Watch three signals. Watch whether new terminals sign flexible supply or simply hope. Watch whether domestic field developments actually get final investment decisions rather than encouraging speeches. Watch whether retail tariffs start absorbing more of the fuel swing. Those three will tell you if the assumptions are holding or cracking.
Southeast Asia is not wrong to want more electricity. Nobody serious argues for darkness as a development strategy. The argument is narrower and harder. Can a region already exposed to seaborne fuel risk keep adding exposure and still call the plan resilient? On present evidence, the answer is “only if the market stays kind.” Markets are not famous for kindness on request.
So the cement mixers keep turning. The tankers keep getting scheduled. The speeches keep calling gas a bridge. Fair enough. Just remember that a bridge needs solid ground on both banks. One bank is rising demand. The other is a fuel system that just showed the world how fast it can wobble. Standing in the middle of that span, it is reasonable to ask whether the next 100 gigawatts are a foundation or a dare.