

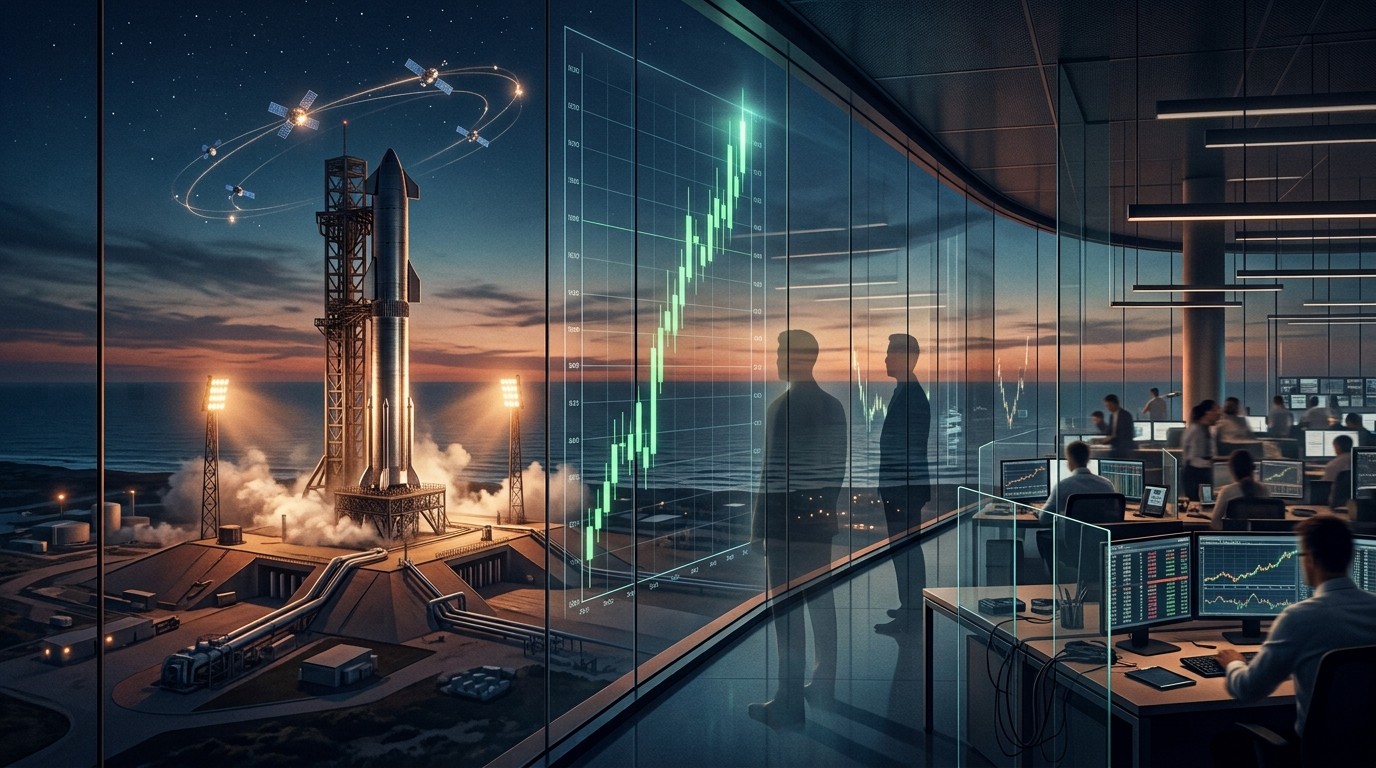
SpaceX Stock Hits June Highs, Musk Back As Trillionaire

SpaceX stock just reclaimed its highest level since June and pushed Elon Musk back over the trillion-dollar line. The note behind the move is bold. The next test flight could matter even more.
Financial market analysis from 05/10/2026. Market conditions may have changed since publication.
I kept refreshing the quote late Monday afternoon, half expecting the move to fade the way so many post-listing pops do. It did not. SpaceX stock finished the session up almost 8 percent, back at levels the market had not seen since the middle of June, and the wealth screens flipped again. Elon Musk, on the real-time tallies that stitch together his stakes in the rocket company and the car company, was once more above a trillion dollars. That is a strange sentence to type in an ordinary market week. It is also, if you have been watching this listing since day one, not entirely surprising.
The close that mattered was $171.09. A desk note out Sunday had already called the shares cheap and pinned a $300 target on them, roughly a 75 percent gap from that print. Buyers showed up. Short covering probably helped. So did a weekend full of hardware headlines that actually moved metal, not just slide decks. Crew went up for a station mission. A separate flight carried computing hardware tied to a major search company into orbit. For a stock that had spent the late summer digging out of an August hole, that combination was enough.
What follows is not a victory lap and it is not a warning label either. It is a walk through the tape, the note, the flights, the rocket that still has to prove it can be caught, and the quieter business of renting compute. I have found that listings this loud reward the reader who slows down. The headline is simple. The machinery under it is not.
Why Monday’s Print Felt Bigger Than an 8 Percent Day
An 8 percent move in a company this size is not a meme flicker. It is a re-rating, or at least the start of an argument about one. SpaceX went public on June 12. Four sessions later the shares closed at a record $201.80. Then the air came out. Early August marked the low. From that trough to Monday’s finish the recovery runs about 58 percent. Anyone who bought the IPO pop and held through the summer knows how long that walk back felt.
Highest since mid-June is a precise claim, and it matters for psychology more than for any chart pattern with a fancy name. A lot of early holders are still underwater versus that June 16 close. A lot of later buyers are not. When a stock retakes a level that used to be “the top after the listing,” two crowds start talking past each other. One says the easy money already happened. The other says the business has more proof now than it did in June, so the old high is a ceiling only if you ignore the calendar.
I lean toward the second reading, with a caveat I will come back to. Proof in this company is physical. A successful crew flight is not a metaphor. Chips in orbit are not a metaphor either. Neither one, by itself, justifies a 75 percent upside case. Together with a fresh analyst push, they explain why the bid was there on a Monday.
The Note That Set the Tone
Sell-side notes do not move every stock. They move stocks where the holder base is still learning the model and where the next catalyst is dated. That is this name. Analysts at a major bank told clients the shares looked inexpensive at current prices and pointed to three buckets: future AI product releases, progress on the giant next-generation rocket, and more contracts in the so-called neocloud business of renting out computing capacity. Their recommendation was to buy. Their number was $300.
A price target is a story with a date on it. The useful part is not the round number. It is which events the author thinks have to happen before the number stops looking silly.
Market strategist, paraphrased from a desk conversation
The timing advice inside the note was almost as interesting as the target. Buy before the next planned test of the heavy rocket, and before the third-quarter report expected late in October. That is a trader’s calendar dressed up as research. It also happens to be a reasonable one. If you believe the next flight attempt includes something the market has never priced as done, you do not wait for the highlight reel.
Perhaps the most interesting aspect is how openly the note treated the stock as a bundle. Not a pure launch utility. Not a pure satellite internet story. Not a pure AI landlord. A bundle. Investors who want a single clean multiple are going to stay frustrated. Investors who can hold three narratives in their head at once are the ones this listing was built for.
What the Tape Actually Did
Almost 8 percent in one session, highest close since mid-June, $171.09 on the tape. Those are the facts worth writing down before anyone starts inventing volume stories. The company did not rush out a comment. Silence after a green day is normal. Silence after a green day that also restores a founder’s trillionaire status is still normal, just louder on social feeds.
From the June 16 record of $201.80 down to the August low and back to $171 is a round trip that has not finished. A 58 percent climb off the bottom sounds heroic until you set it next to the old high. There is still a gap. Bulls call that gap unfinished business. Bears call it a reminder that the first buyers paid up for a story that then had to earn its keep in public.
Both can be a little right. I have watched enough fresh listings to know the second month is rarely the verdict. The verdict shows up when a dated catalyst either lands or slips, and when the first full quarter as a public company gets a number attached to it.
A Week of Hardware, Not Just Headlines
Late last week the company flew more than one historic mission inside a single day. One carried a crew for the American space agency toward the station. Another sent computing chips associated with a major internet firm into orbit. Stack those next to each other and you get the whole pitch in miniature: reliable rides for people who already trust you, plus a new line of work that did not exist in the old launch brochures.
Crew flights still do something money cannot fake. They tell agencies, insurers, and the public that the cadence is real. A missed window or a scrubbed countdown does not kill the equity story, but a clean run supports the part of the multiple that depends on being the default ride. The chip flight is different. It is a receipt. Someone with a serious AI budget paid to put hardware above the atmosphere, on this company’s rocket, on this company’s timetable.
Is orbital compute a business or a demonstration? Honest answer: both, for now. Demonstrations that get repeated become line items. Demonstrations that stay one-off become conference slides. The equity market, being impatient, is trying to price the line item early. That is how you get an 8 percent Monday after a Sunday note that name-checks neocloud contracts in the same breath as rocket progress.
- A crewed station mission reinforces the government and agency franchise.
- An orbital chip launch gives the AI-capacity story a physical exhibit.
- Doing both in one day is the kind of cadence investors can retell without a footnote.
- Neither flight, alone, settles the valuation argument the $300 target opened.
The Rocket Everyone Is Waiting to See Caught
Starship is the next-generation system, the largest rocket anyone has built, drawn up to be fully reusable. Booster and upper stage are both supposed to come home. In earlier tests the upper stage has splashed down in the ocean. Splashdown is data. It is not reuse. Reuse is the economic claim. Until the hardware flies again, lands again, and flies again without a rebuild that eats the margin, the claim stays partly on paper.
Analysts suggested that an attempt to catch the upper stage ship on the next test could be the biggest positive catalyst since the initial offering. I think that phrasing is aggressive, and I also think it is directionally fair. The market has already paid for “they launch a lot.” It has not fully paid for “the giant one comes back in a way that changes cost per kilogram for everyone who wants a ride, including their own satellite constellation.”
Catching a ship is a visual event. Markets like visual events more than they admit. A clean catch would travel further on trading floors than a paragraph about specific impulse. A failed attempt would travel just as far, in the other direction. That asymmetry is why the note told clients not to wait around.
What the system is supposed to unlock, if the engineering holds, is volume. More of the company’s own connectivity satellites. Cargo and crews for other firms and agencies. A launch tempo that makes today’s busy calendar look like a warm-up. None of that arrives on the day of a single test. It arrives if the test becomes a habit. Still, habits start with a flight someone can point at.
Starship claim, in plain language:
  Upper stage returns, not just splashes.
  Booster returns, already the better-known half.
  Cost per flight falls enough to change the satellite plan.
  Outside customers trust the cadence with cargo and crew.
How the Summer Selloff Set Up This Bounce
The shares started trending lower soon after that mid-June record. By early August they had bottomed. A 58 percent climb since then is the kind of recovery that makes late sellers feel foolish and early dip buyers feel briefly brilliant. Both feelings are temporary. What actually changed between August and October is a mix of flight results, a clearer AI-capacity narrative, and the simple fact that a new listing eventually runs out of tourists.
Tourists leave. Operators stay. The operator question is whether launch margin, satellite cash generation, and rented compute can be discussed in the same earnings call without one of them being a footnote. Late October is the next chance to see that attempted in public. Until then, the stock is trading the anticipation of the call as much as the call itself.
I have found that the ugliest weeks after an IPO often do more for the long-term holder than the pretty ones. They shake out people who wanted a ticker, not a factory. August looks, in hindsight, like that shakeout. Monday looks like the market admitting the factory is still running.
The AI Business Inside the Rocket Company
SpaceX picked up an artificial intelligence operation through last year’s acquisition of the founder’s AI venture, then widened it with the more recent purchase of a coding-tool firm. The homegrown model has not broken into the front rank the way the leading labs have. That is an awkward fact, and it is worth saying plainly. Brand heat is not the same as model leadership. Anyone modeling this segment as a consumer chatbot winner is modeling a different company.
The revenue that is showing up is less glamorous and, for now, more bankable. Capacity is being rented to large customers, including a major search firm and a leading AI lab. Renting power, chips, and the buildings around them is a different sport from winning the benchmark table. It can still be a large sport. Neocloud is the industry nickname, and the Sunday note treated additional contracts in that niche as a reason to own the stock before the next rocket test, not after.
There is a tension here I do not think the market has resolved. A rocket company that also sells compute looks, on a good day, like a platform. On a skeptical day it looks like two businesses sharing a founder and a balance sheet. The acquisitions pull the second reading toward the first, but only if the rented capacity keeps growing after the press releases fade. Product releases still to come are the other half of the analyst case. Until those land in customers’ hands, they are a call option, not a run-rate.
The model that does not lead the leaderboard can still sit on top of a very expensive pile of chips. The question is who pays to use the pile, and for how long.
Government Work, Defense Dollars, and a New Title
A large slice of revenue still comes from the U.S. government, and a growing slice from defense contracts. Tracking cited by industry researchers puts Defense Department work above $12.7 billion to date. That is not a rounding error. It is a franchise. It is also a political fact, whether or not anyone on the equity desk wants to talk about politics before lunch.
Midweek, the Pentagon named Musk co-lead of an initiative called Project Meridian, aimed at identifying weapons, technologies, and military capabilities the country may need in future wars. Close ties to the current administration are an advantage on contract timing and a risk if the political weather changes. Both sentences can be true. Investors who pretend one of them is not are doing their own discount rate a disservice.
Over the weekend the founder said the AI division, previously branded in a way that echoed the acquired lab, would be renamed to lean into the administration’s preferred styling. Branding is not cash flow. It is a signal about which room he wants the division discussed in. Signals get traded, briefly. Then the contract list reasserts itself.
He was also notably absent from a New York City Council hearing where officials questioned AI executives and researchers about regulation. Representatives from the big labs and platforms were in the room. A council member argued that AI had taken over the economy, inflated valuations, consumed public land for data centers, and lifted the net worth of executives, naming Musk as the first trillionaire. The stock did not need him in that chair to rally. The hearing still belongs in the file, because the regulatory mood in big cities is part of the cost of building the buildings that feed the neocloud story.
The Trillion Line, and Why It Is a Distraction
According to the real-time billionaire tally that factors in the car-company stake and the rocket-company stake, Musk stood at about $1.03 trillion after Monday’s move. He had crossed that line before. He had slipped under it when the new listing cooled. Crossing it again is a media event. It is a weak investment thesis.
Wealth rankings move when share prices move. They do not tell you whether $171 is cheap relative to the cash the constellation can throw off, or rich relative to the years Starship still needs. They do tell you that a huge fraction of one person’s net worth is marked to market every afternoon. That concentration is part of why the stock trades with a personality. It is also why a single Sunday note can feel, for a session, like it rewrote the weekend.
In my experience, the sessions that restore a round-number headline are good for attention and mediocre for entry discipline. If you needed the trillion label to notice the 58 percent climb off the August low, you were late to the recovery and early to the victory speech. The useful work is comparing the close to the June high, the target to the close, and the next flight to both.
| Marker | Figure | Why it matters |
| June 12 | Listing day | Start of the public record |
| June 16 close | $201.80 | Record, still the overhead mark |
| Early August | Session low area | Sentiment trough after the debut |
| Monday close | $171.09 | Best since mid-June, up nearly 8% |
| Climb off the low | About 58% | Recovery, not a full round trip |
| Street target cited | $300 | Roughly 75% above Monday |
| Founder tally | About $1.03 trillion | Headline, not a valuation model |
What Cheap Means When the Asset Is This Strange
Calling the stock cheap is a relative claim. Relative to what? Relative to the $300 target, obviously. Relative to the June high, it is cheaper than the first wave of buyers. Relative to a sober discount of launch cash flows plus satellite cash flows plus a young compute rental book, nobody outside the company has the full worksheet. Public investors are still building the model in public. That is normal for a listing this young. It is also why words like cheap travel faster than spreadsheets.
A few ways people are framing it, without pretending any one frame is the truth:
- Launch utility: price the rides, the reuse rate, and the government book, then treat everything else as upside.
- Connectivity platform: price the satellite network as the core, and treat rockets as the captive supplier.
- Compute landlord: price the rented AI capacity, and treat orbit as a differentiated site, not a gimmick.
- Option on the giant rocket: pay up because a working, reusable heavy lifter rewrites the first three frames.
The Sunday note is closest to a blend of three and four, with one still in the background. If you only believe frame one, $171 may already feel full. If you believe frame four is a this-year event rather than a this-decade event, $300 can look conservative. Most serious holders I talk to are stuck between those poles, which is another way of saying the stock will stay jumpy.
Earnings, the Next Flight, and the Gap Between Them
Third-quarter results are expected late in October. Between now and that print sits the possibility of another heavy-rocket test. The analysts’ suggestion was to own the shares ahead of both. That is coherent if you think either event can gap the stock and you do not want to be the person buying the gap. It is less coherent if you think both events are already in the price after an 8 percent day.
Here is how I would separate them. The flight is binary in the short run and narrative in the long run. A catch attempt that works becomes the clip everyone sends. A catch attempt that fails becomes the clip everyone sends, with a different caption. The earnings report is slower. It should tell you whether the AI rental book is a paragraph or a segment, whether launch cadence is converting into margin, and whether the satellite side is still the quiet engine. Markets can ignore a quiet engine for a quarter. They cannot ignore it for a year.
If the flight slips and the report is merely fine, Monday’s enthusiasm has to live on the note alone. Notes age in days. Hardware ages in flights. That is the trade-off hiding inside the 75 percent upside case.
Risks That Do Not Fit in the Rally Recap
Reuse is unproven on the upper stage. That single sentence should sit on every bull slide. Ocean splashdowns are progress. They are not a caught ship, and a caught ship is not a fleet. Schedule slips on vehicles this large are normal. The equity story sometimes treats them as betrayals. They are not betrayals. They are the work.
Customer concentration is another. Government work above twelve billion dollars to date is a strength until budget politics or a rival’s certification changes the mix. AI capacity rented to a handful of famous names is a strength until those names build their own halls or negotiate harder. The acquired coding tool and the homegrown model add integration risk. Integrations fail quietly, then show up as a segment that never quite becomes the segment you modeled.
There is also key-person gravity. A founder who is co-leading a defense initiative, renaming divisions to match a political brand, skipping a city hearing, and marking a trillion-dollar fortune to two liquid stakes is not a normal CEO calendar. Some investors want that gravity. Some price it as a discount. Monday’s tape voted for the first group. Votes can be recast.
Valuation gap risk is the dull one, and the one that hurts. A stock 58 percent off its low can still be expensive if the low was panic and the business did not improve 58 percent. A stock still below its June high can still be expensive if June was the tourist price. Both descriptions fit this chart. Living with that ambiguity is the job.
How a Careful Reader Might Hold the Story
None of this is a personal recommendation. It is a way of not getting hypnotized by a round number. If I were building a checklist for the next month, it would look less like a slogan and more like a set of questions.
- Does the next heavy-rocket test attempt a ship catch, or another splashdown with better data?
- Does late-October reporting break out compute rental clearly enough to model?
- Are new capacity contracts named, or still described as pipeline?
- Does launch cadence for the existing fleet stay boring in the best sense?
- Does the government book grow, stall, or get noisier for non-operational reasons?
- Does the stock hold $171 after the headline fades, or was Monday a one-session argument?
Boring cadence is underrated. The crew flight and the chip flight were the opposite of boring, which is why they led the weekend. The business that funds the next five years is allowed to be repetitive. Satellites replenished. Rides sold. Capacity leased. A giant rocket that, one day, stops being a test. Repetition is how a listing stops being a story and starts being a compounder. We are not there yet. Monday was a reminder that the path is still open.
Orbital Chips and the Temptation to Overread
Putting accelerators in orbit is a striking picture. It photographs well. It also invites a leap from one flight to a whole architecture of space-based computing. Leap carefully. Power, cooling, latency, radiation, and the cost of getting mass up and, sometimes, back down are not solved by a single successful insertion. They are solved by repetition and by customers who renew.
The fair reading of last week’s chip flight is narrower and still bullish. A sophisticated buyer trusted this rocket with valuable hardware. That trust is a commercial asset. It supports the idea that the company can sell more than seats and more than its own satellites. It does not, by itself, prove that orbit is about to undercut terrestrial data halls on price. Anyone selling you that proof this week is selling you the caption, not the physics.
I suspect the equity upside in this corner of the story, if it arrives, will look dull in the footnotes and loud in the multiple. A contract extension. A second customer. A disclosure that capacity utilization is not a science project. Those are the lines I would rather see than another rendering of a server floating above a coastline.
Satellite Internet Still Sits Under the Noise
It is easy, on a day like Monday, to talk only about the new rocket and the new compute brand. The connectivity constellation is still the asset that makes the launch cadence self-funding in the bull case. Every heavy-lift improvement that actually works should, in theory, make it cheaper to refresh and expand that network. That loop is the original reason public investors were willing to debate a valuation this large. AI capacity is the plot twist. It is not the whole plot.
Subscribers, average revenue, terminal costs, and competition from other constellations will matter more in the October discussion than a single green session. If those numbers are healthy, the 8 percent day has a floor under it. If they are soft, the rocket option has to carry more of the multiple than is comfortable. I have a bias here: I would rather own a launch company whose own customer is growing than a launch company waiting on outside manifests alone. This firm is both. The mix is the argument.
Politics as a Factor, Not a Thesis
Administration proximity cuts both ways, and it is fashionable to pretend otherwise. A co-lead role on a future-capabilities project can open doors for a contractor that already holds a deep defense book. It can also tie the equity story to a news cycle the operating company does not control. Renaming an AI unit to echo a political brand is a choice about audience. City hearings the founder skips still happen, and the quotes from them still circulate.
A practical way to hold this, without turning a stock note into a campaign note, is to ask whether the contracts would survive a change in tone. Hardware that works, launches that leave on time, and capacity that customers renew are more durable than proximity. Proximity can accelerate the first purchase. It rarely saves a bad second one. The $12.7 billion defense tally is evidence of a relationship that predates the current headlines. Treat new titles as incremental, not as the franchise.
A Cleaner Way to Read the 75 Percent Gap
From $171.09 to $300 is not a gentle stroll. It assumes the market will pay, within the target horizon, for events that have not happened. A caught ship. A compute book that looks like a business. Product releases that are more than a keynote. Additional contracts that survive legal review and power-grid reality. You can believe those are likely and still admit the path is narrow.
You can also believe the shares are not cheap and still admit Monday was rational. New information arrived. A credible desk put a number on it. The stock had already climbed 58 percent off the low, which means buyers were not starting from despair. They were adding to a recovery. Adding to a recovery is different from bottom-fishing. It fails more often when the next datapoint is late.
So the gap is a hypothesis. Hypotheses get tested by calendars. This one has a flight window and an earnings window. After those, the hypothesis either grows a scar or grows a citation. I would rather judge it then than judge it against a trillion-dollar headline that will move again the next time the car stock has a mood.
What the Listing Has Already Taught
June taught everyone the size of the appetite. August taught everyone that appetite is not a floor. October, so far, is teaching something subtler: the market will pay up again when hardware and a research note arrive on the same weekend. That is not wisdom. It is a pattern. Patterns in new listings break the moment the company has to be specific.
Specific looks like this. How many flights. What reuse was actually achieved. What the compute customers paid, and whether they can leave. What the constellation added. What the defense book renewed. A founder above or below a round number is color. Color fills the afternoon. Specifics fill the model.
If you only remember one tension from this move, make it that one. The tape reclaimed a June level and restored a status headline. The business still has to reclaim the claim that made the June level possible in the first place: that the largest rocket in the world can come home, and that the company wrapped around it can sell more than launches. Until those are ordinary, $171 is a conversation, not a conclusion.
Questions Worth Sitting With Before the Next Session
Is the stock cheap, or is the target optimistic? Those are not the same question, even though the note treats them as cousins. Cheap relative to a $300 destination assumes the destination is a place the business can reach without a dilutive surprise or a slipped vehicle. Optimistic is allowed. It should be labeled.
Would a failed catch attempt erase the crew flight and the chip flight? It should not, logically. Markets are not purely logical on test days. Expect the clip to dominate the session if it happens, then expect the October report to matter more two weeks later. Sequence is a form of risk management.
And the wealth line: does it change the operating plan? No. It changes the audience. A larger audience brings sharper questions, which is healthy, and noisier ones, which is the tax. The company did not need to answer either kind on Monday. It will need answers when the numbers show up.
A simple filter for the next headline:
  Did metal fly, or did a label change?
  Did a customer pay, or did a target move?
  Did reuse improve, or did a splashdown get a better camera?
  Keep the first of each pair. Discount the second.
That filter would have kept you honest on Monday. Metal flew last week. A target moved on Sunday. A label, the trillion line, moved because the shares did. The rename of the AI unit is a label. Project Meridian is a title plus a mandate, which sits somewhere between label and contract. Sort them and the day gets smaller, which is useful. Smaller does not mean unimportant. An 8 percent re-rating in a company this closely watched is a fact. Facts can be sized without being dismissed.
I will be watching the flight attempt and the late-October report more closely than the next wealth screenshot. If the ship comes home in a way the earlier tests did not, the June high stops looking like a ceiling and starts looking like a chapter. If it does not, Monday will read as a well-argued overreach, the kind public markets forgive only when the next quarter does the arguing instead. Either way, the listing has left the souvenir phase. It is in the proof phase now. That is the more interesting place to be, and the less comfortable one.
Technical analysis is the study of market action, primarily through the use of charts, for the purpose of forecasting future price trends.

Gas Cars Fall Under 50% Of Global New Auto Sales
Lucid Q3 Deliveries Fall As Production Cuts Meet Demand
Related Articles

Ethereum Price Surges Toward $2000 as Nasdaq Rally Fuels Demand
Ethereum has climbed back above $1900 and is eyeing $2000, but will the Nasdaq momentum and ETF inflows be enough to break through resistance? The charts tell an interesting story...
Global Peace in 2025? Why Markets Say No Chance
Markets just priced in an Australian rate hike while the US sheds jobs and Putin laughs off peace talks. Everyone is talking about a soft landing, but the signals scream something very different. Here's what almost nobody wants to admit yet...

Gold and Silver Rally Poised to Resume as Peace Hopes Emerge
As hopes for a U.S.-Iran peace settlement grow, gold and silver are perking up. But is this the start of the next big leg higher in the historic rally? The factors at play might surprise you...