

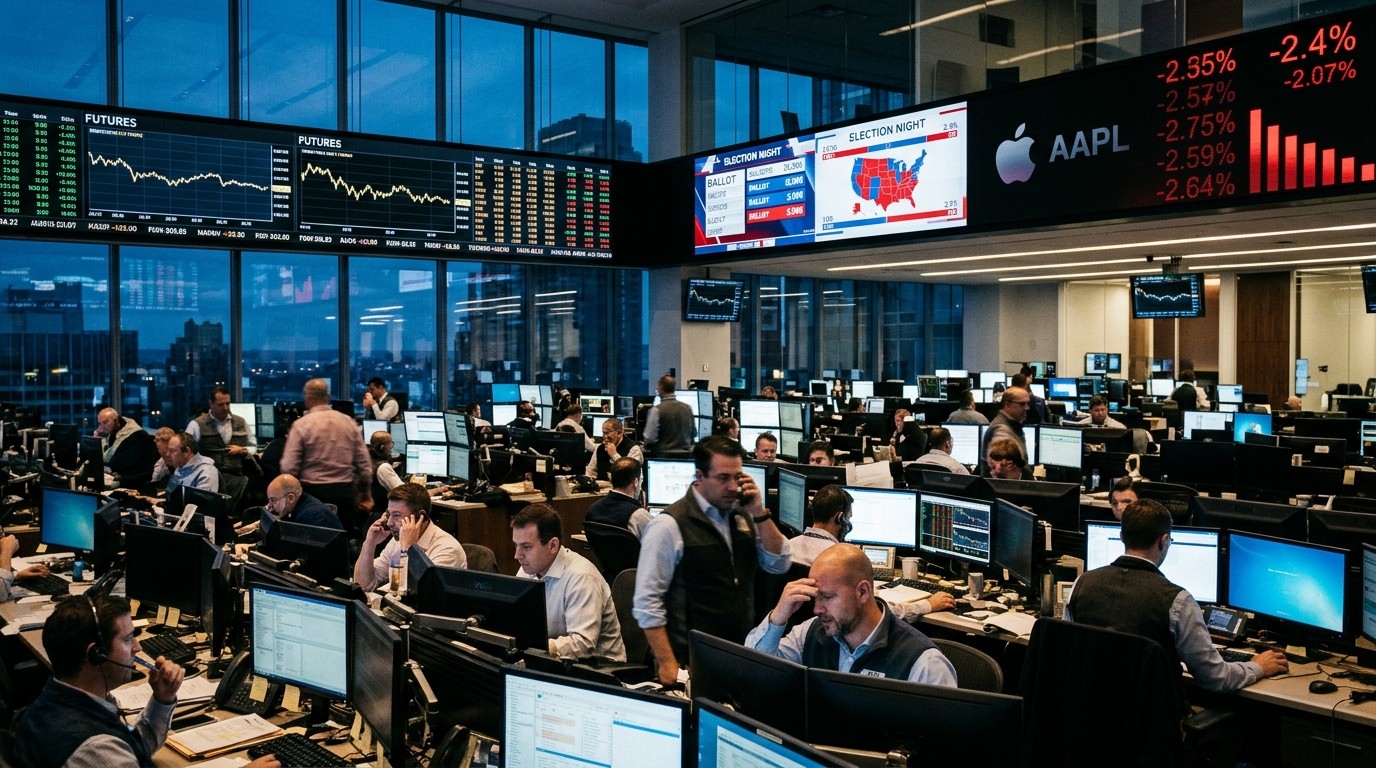
Stock Futures Flat After Apple Earnings Ahead Of Midterms

Apple shares tumbled after hours on soft guidance while stock futures barely moved. With midtermsDrafting the stock market blog post hours away and a massive semiconductor deal shaking the sector, the next session could look very different. Here’s what traders are watching closely right now.
Financial market analysis from 02/11/2026. Market conditions may have changed since publication.
I’ve been watching the screens longer than usual tonight. Something about the quiet in the futures market feels heavier than a normal Monday. After a full day of tech stocks getting sold and Apple dropping a guidance number that left traders underwhelmed, the overnight session has settled into an almost eerie stillness. S&P 500 futures are basically flat. Dow futures slipped a couple of points. Nasdaq-100 futures managed a tiny gain. On the surface it looks calm. Underneath, nobody is really relaxed.
What Really Happened After The Closing Bell
Apple came out with its numbers and the reaction was immediate. Shares slid roughly three percent in extended trading. The company guided December-quarter revenue growth between seven and ten percent. Wall Street had been sitting closer to eleven and a half percent. That gap was enough to sour the mood. I’ve seen Apple miss expectations before and bounce right back. This time the miss landed right when investors were already rotating out of the biggest technology names. Timing matters.
During regular hours the Nasdaq Composite finished down just over one percent. The S&P 500 slipped about half a percent. The Dow managed a modest gain of a little more than two hundred points. That split tells you everything about the current market psychology. Money is still flowing, but it is flowing away from the high-flying growth names that dominated the last couple of years and toward areas that feel more defensive or cyclical.
The Semiconductor Shockwave Nobody Saw Coming
While Apple dominated the after-hours conversation, another story was busy rearranging the semiconductor landscape. Marvell Technology announced it would buy Lumentum in a deal valued around one hundred fifteen billion dollars. Marvell shares dropped about twelve percent. Lumentum fell even harder, roughly eighteen percent. Deals of this size almost always create winners and losers in the short term, and tonight the market decided both sides needed to be sold first and asked questions later.
Oracle also joined the decline, sliding about eight percent after revealing plans to raise ten billion dollars in common stock and another ten billion in bonds. The money is earmarked for artificial intelligence infrastructure. In theory that should be good news. In practice, investors focused on the dilution and the sheer size of the capital raise. When a company that large suddenly needs that much fresh capital, people start asking harder questions about cash flow and valuation.
Midterm Elections Are Already Moving Money
Tomorrow’s midterm elections have been sitting in the background for weeks, but the closer we get the more they influence positioning. Prediction markets currently give Democrats roughly a seventy-five percent chance of taking the Senate. A full sweep of both chambers would, according to several strategists I’ve spoken with, likely pressure artificial intelligence related stocks. Even without a complete change of control, a shift in either house changes the oversight picture for defense, healthcare, and the entire technology sector.
I’ve found that markets usually prefer gridlock. Too much power concentrated in one party often leads to bigger spending packages and regulatory swings that create uncertainty. A respected market strategist put it simply earlier today: anxiousness before the vote is normal. Once the results are known, relief tends to follow and stocks often stabilize. The real risk, in my view, sits in the extreme outcomes. A massive wave in either direction could force a faster recalibration of sector weightings than many portfolios are prepared for.
There’s some anxiousness before these elections. Once you are through it, it’s a big relief and markets tend to do pretty well. If you have a huge red wave or a big blue wave, markets actually kind of don’t like that as much because you have too much spending one way and too much power.
That assessment lines up with what I’ve watched in previous midterm cycles. The days immediately after the vote often matter more than the campaign rhetoric. Liquidity can improve once the political uncertainty is resolved, even if the policy direction is not ideal for every industry.
A Crowded Earnings Calendar Arrives Tomorrow
Tuesday will not give traders much time to process the election headlines. Several large companies report before the open, including Pfizer, Shopify, Eaton, and Marathon Petroleum. Later in the day Advanced Micro Devices and Super Micro Computer will add more color to the semiconductor and artificial intelligence infrastructure story. Any surprise, positive or negative, has the potential to amplify whatever direction the broader market chooses after the political results start coming in.
On the economic side the calendar brings the September Job Openings and Labor Turnover Survey plus factory orders. Neither report is usually a market mover on its own, but in a week when political risk is elevated every data point gets examined for clues about the Federal Reserve’s next steps. Soft labor data could reawaken rate-cut hopes. Strong numbers would keep the higher-for-longer narrative alive a little longer.
Why The Tech Rotation Feels Different This Time
We’ve seen rotation out of technology before. What feels different right now is the breadth of the selling and the willingness of investors to abandon names that still show strong fundamental growth. Apple’s guidance miss did not happen in isolation. It arrived after several sessions of steady selling in the largest growth stocks. Once momentum turns, even good news can be ignored and modest disappointments get punished hard.
In my experience the most dangerous phase is not the initial selloff. It is the period when investors start convincing themselves that the leaders of the last cycle will never lead again. That kind of thinking usually overshoots. Many of the companies being sold still generate enormous cash flow and sit at the center of structural growth trends. The question is simply how much valuation compression the market demands before buyers step back in.
- Valuations in several high-profile technology names remain elevated relative to history
- Capital spending plans for artificial intelligence continue to expand at a rapid pace
- Investor positioning had become crowded after a long period of outperformance
- Political uncertainty adds another layer of risk premium that was previously underpriced
None of those factors disappear overnight. They simply get reweighted as new information arrives. Apple’s revenue range was the first concrete data point of the week. The election results will be the second. Earnings from the semiconductor and software names will supply the third. By the end of the week the market should have a clearer hierarchy of winners and losers.
Futures Action And What It Signals For The Open
Looking at the overnight session, the lack of conviction stands out more than the actual numbers. Nasdaq-100 futures managed a small gain after six o’clock Eastern while the S&P 500 and Dow futures hovered near unchanged. That kind of narrow range often means larger players are waiting. They want to see how the election narrative develops and how the early earnings reactions unfold before committing fresh capital.
I’ve sat through enough quiet overnight sessions to know they can explode once the cash market opens. Liquidity thins out after regular hours. A single large order or a headline can move futures more than the entire previous day. With both political and corporate catalysts stacked on top of each other, the opening hour tomorrow could set the tone for the rest of the week.
Sector Implications Beyond Technology
While technology grabbed the headlines, other parts of the market were quietly doing better. The Dow’s gain reflected strength in industrial and financial names that tend to benefit when growth stocks cool off. Energy and healthcare also showed relative resilience. That pattern often continues when investors reduce risk in the highest-duration assets and rotate into areas with more tangible near-term cash flows.
Defense stocks remain particularly sensitive to the election outcome. A change in congressional control can alter spending priorities and oversight intensity. Healthcare faces similar uncertainty around potential policy shifts. Even if the ultimate legislative impact takes months to materialize, the market tends to price the risk immediately.
| Sector | Recent Pressure Level | Key Near-Term Catalyst |
| Technology | High | Apple guidance, AI capital raises |
| Semiconductors | Very High | Large acquisition announcement |
| Healthcare | Medium | Election oversight changes |
| Defense | Medium-High | Congressional control shift |
| Industrials | Low | Relative rotation beneficiary |
The table above is a simplified snapshot of how the market is currently sorting risk. These rankings can shift quickly once actual election results and fresh earnings land.
Positioning Thoughts Heading Into The Vote
Perhaps the most interesting aspect of the current setup is how little directional conviction exists in the futures market. Traders are hedging, not swinging for the fences. That usually means the first clear narrative after the election will attract rapid capital. If the results point to gridlock, the relief rally could be broad. If one party sweeps, the market may punish the sectors most exposed to policy risk and reward those that benefit from the new power balance.
I’ve been reducing exposure to the most expensive growth names over the past couple of sessions while keeping a core position in companies that still show durable free-cash-flow growth. Cash levels are a bit higher than normal. That is not a permanent stance, just a recognition that two major catalysts are landing within twenty-four hours of each other. Flexibility feels more valuable than heroic conviction right now.
Longer-Term Context Behind The Noise
It is easy to get lost in the daily headlines and forget the structural backdrop. Corporate investment in artificial intelligence infrastructure continues at a pace rarely seen outside of major technology platform shifts. Capital spending plans from the largest cloud and semiconductor companies still point higher for the next several years. That spending supports a wide ecosystem of suppliers, software firms, and energy providers.
At the same time, valuations in parts of the market had simply run ahead of near-term fundamentals. Apple’s more modest growth outlook is a reminder that even the strongest franchises face slower periods. The market is in the process of resetting expectations to something more sustainable. That process is rarely comfortable, but it often creates the cleaner entry points that patient investors look for.
Interest rate expectations also remain a quiet undercurrent. Every economic release is still filtered through the lens of what it means for the Federal Reserve. A softer labor market would give the central bank more room to ease. Stronger data would keep financial conditions tighter for longer. Either path is possible. The market simply wants clearer evidence before it commits to one narrative.
Practical Takeaways For The Coming Sessions
First, respect the political calendar. Liquidity and volatility patterns around midterm elections have a long history. Second, treat the early earnings reactions as information rather than gospel. One or two companies do not define an entire sector. Third, watch the behavior of the largest technology names after the initial emotional response fades. Sustained buying or selling in those names usually sets the tone for the broader index.
- Monitor overnight futures for early clues about institutional positioning
- Separate election rhetoric from actual policy probability once results are known
- Pay close attention to guidance language from semiconductor and software companies
- Keep position sizes modest until the dual catalysts of politics and earnings are absorbed
- Reassess sector weightings once the market reveals its post-election hierarchy
None of these steps guarantee profits. They simply improve the odds of staying aligned with the market’s evolving consensus rather than fighting it.
The Mood On The Desk Right Now
Walking around the trading floor earlier, the conversations felt more measured than panicked. Nobody is declaring the end of the technology bull market. At the same time, few are rushing to add risk ahead of tomorrow’s events. That middle ground is healthy. Excessive optimism or excessive fear both tend to be expensive. Cautious engagement with clear invalidation levels feels like the more durable approach.
Apple’s guidance will be dissected in every research note that hits inboxes tonight. The Marvell-Lumentum transaction will force analysts to update models across the optical and networking supply chain. Oracle’s capital raise will keep the artificial intelligence spending debate alive. And through it all the election results will arrive in waves, first with exit polls, then with called races, and finally with the ultimate balance of power.
By the time the closing bell rings on Tuesday the market will know a lot more than it does tonight. Whether that knowledge produces a relief rally, a fresh leg lower, or another day of sector rotation remains to be seen. The futures market’s current stillness is not indifference. It is the quiet that often precedes a more decisive move.
For now the best stance is simple: stay informed, stay flexible, and avoid the temptation to overtrade the noise. The real signals will become clearer once the votes are counted and the earnings calls are finished. Until then, the flat futures print is less a forecast and more a pause. Markets do not stay quiet forever. The next chapter is already being written.
Looking further ahead, the combination of political resolution and a heavy earnings calendar should reduce one major source of uncertainty even if it introduces new ones. Investors who have lived through previous midterm cycles know the pattern. Anxiety builds, volatility rises, and then a new equilibrium forms once the power structure in Washington is known. That equilibrium is rarely permanent, but it usually lasts long enough for the market to refocus on corporate fundamentals and economic data.
Apple’s more restrained outlook may ultimately prove temporary. Product cycles, services growth, and installed base expansion have supported the company through previous soft patches. The same can be said for many of the technology names currently under pressure. What changes in the short run is the multiple investors are willing to pay. Multiple compression is painful while it happens and often creates opportunity once it stabilizes.
The semiconductor deal activity also deserves continued attention. Large acquisitions at elevated valuations can signal confidence in long-term demand, or they can signal that strategic buyers see limited organic growth and prefer to buy rather than build. The market will sort that distinction out over the coming weeks as integration plans and synergy targets become clearer.
In the end, nights like this remind me why index futures exist in the first place. They give participants a continuous way to express views when the cash market is closed and information is still arriving. Tonight the collective view is one of caution. Tomorrow that view will be tested by real election results and a fresh batch of corporate numbers. The gap between today’s quiet and tomorrow’s reaction is where the next set of opportunities will appear.
I’ll be watching the same screens again at the open. The story has only just begun.
A journey of a thousand miles must begin with a single step.

Nvidia Humanoid Robots Rely On Chinese Robot Hands
China Plunge Protection Team Deploys 15 Billion Swap Rescue
Related Articles

Korea Zinc Stock Plunges 13% Amid Shareholder Dispute
Korea Zinc's shares tumbled more than 13% in a single session after its biggest shareholders vowed to block a massive U.S.-backed smelter project. Is this a fight for control or a genuine concern over dilution? The drama is intensifying...
Apple’s Rally Sparks S&P 500 Surge: Market Insights
Apple’s 6% surge fueled the S&P 500 rally, but what’s driving the market’s churn? Dive into consumer trends and rate cut expectations to uncover the next big move...

How Fake Local News Sites Are Poisoning AI Chatbots Before Elections
A quiet network of websites appeared almost overnight and began shaping what AI chatbots tell voters about candidates. The sites look like local journalism but exist for a very different purpose. What happens next could change how millions decide.