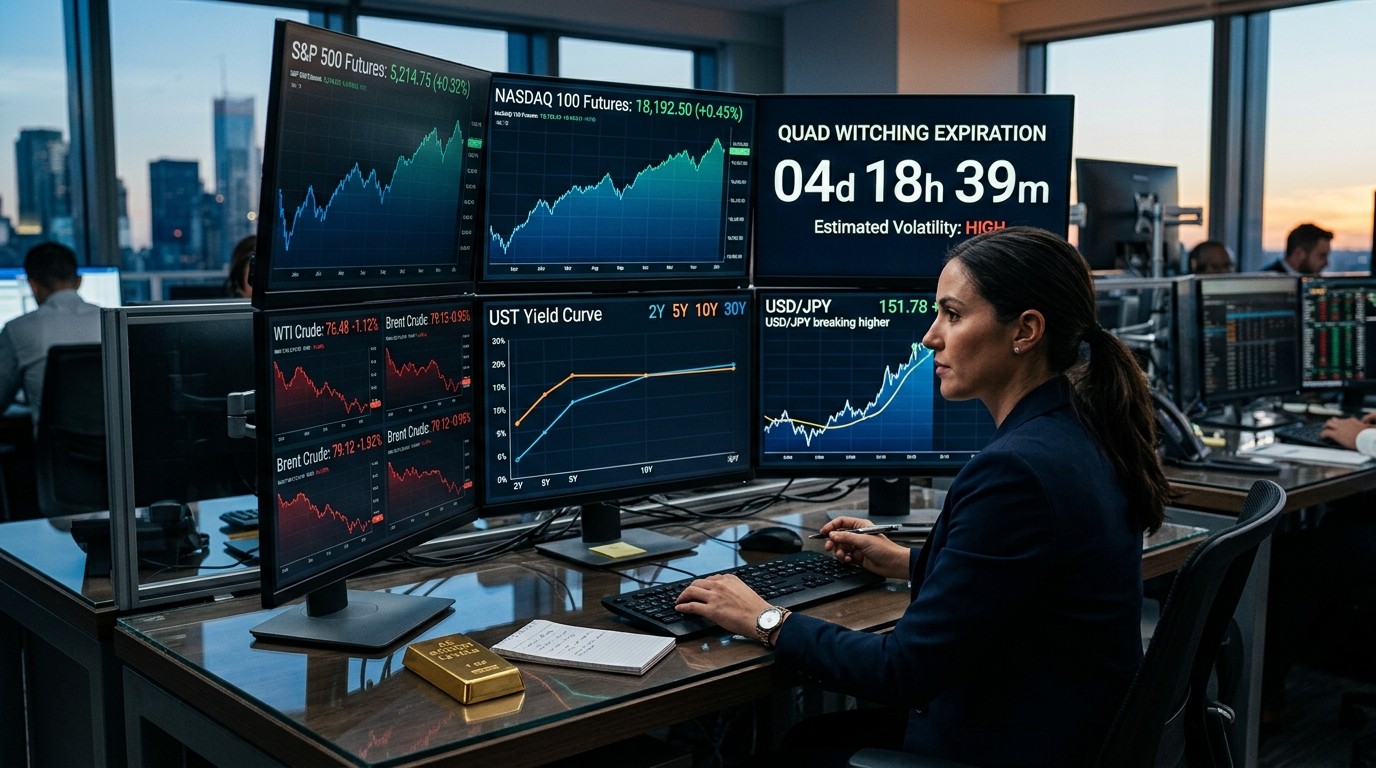

Have you ever watched a market look bored on the surface while something enormous ticks underneath? That is the feeling this morning. U.S. stock futures are barely moving, yet a near-record quad witching of roughly $7 trillion in options notional is set to roll off, index rebalances hit after the close, and Treasury yields have started climbing again. I have covered plenty of expiration Fridays that looked sleepy at 8 a.m. and then turned messy by lunch. This one has that same quiet-before-the-shuffle energy.
Why A Flat Open Can Still Be A Big Day
As of the early New York hour, S&P 500 futures were up a slim 0.1% around 7,713, after giving back a little of the overnight lift. Nasdaq futures held a firmer 0.3% bid. That is not a stampede. It is more like the market keeping its shoes on while it waits to see who has to unwind what. Big tech is doing the heavy lifting again. Alphabet led the Magnificent Seven higher in premarket trade. Amazon sat near flat after a sharp rally tied to a long-term energy-equipment deal. Apple lagged the group. Nvidia, Tesla and Meta were modestly green. Microsoft slipped a touch.
Oil is the other mood setter. Softer diesel and WTI prices have taken a bit of heat out of the inflation story, at least for a session. Brent hovered near $104. WTI futures were roughly unchanged around $96 after earlier weakness. Gold pushed toward $4,400 an ounce. The dollar firmed about 0.2%. Those cross-currents explain why risk appetite looks fine in chips and a little cautious everywhere else.
I keep coming back to positioning. When that much options value expires on the same day as index adds and weight tweaks, realized volatility can jump simply because the hedges that were pinning prices disappear. One dealer note put it plainly: Friday’s expiration may remove the very flows that have damped day-to-day swings. If you have been wondering why the tape felt sticky, that is part of the answer.
The Yield Story Is Back In The Driver’s Seat
Treasuries resumed losses after a brief rebound. The 10-year yield rose about three to four basis points toward 4.97%. Front-end yields were four to five basis points cheaper on the day at one point, which flattened 2s10s toward 24 basis points, almost a year-to-date low. The 5s30s spread sat near 46 basis points, the tightest since early 2025. That is a classic bear-flattening mix: policy credibility plus sticky energy risk, with traders still not ready to price a long stretch of easy money.
In my experience, a flattening curve after a central-bank week is the market’s way of saying two things at once. Near-term growth is not collapsing. Longer-term inflation is not fully tamed either. UK and German yields moved higher as well, so this is not a purely domestic Treasury story. Investment-grade dollar issuance has been busy. Six deals priced a day earlier for about $21 billion, with books more than four times covered. Dealer talk for next week sits near $35 billion. Auctions of two-, five- and seven-year notes start next week. Supply does not vanish just because equities look calm.
Energy prices and monetary policy expectations will remain the main market drivers until the third-quarter earnings season begins.
That line from a European strategist captures the tape better than any slogan. Diplomacy headlines around energy supply can knock crude around for a day. Policy talk can knock bonds around for a week. Earnings will eventually decide whether the AI trade still funds the whole house.
What The Bank Of Japan Actually Delivered
Overnight, the Bank of Japan raised its benchmark by 25 basis points, as expected, taking the target near 1.25%, the highest in decades. The surprise was the vote, not the move. Two members appointed by the current prime minister dissented. Markets read that split as dovish. The yen slid sharply, with dollar-yen breaking above 157 and trading toward 158. Japanese stocks rallied, tech more than banks. The dollar caught a bid after the decision.
Official language still pointed to further increases if the economy and prices evolve as projected. The press conference did not sound urgent. Easy financial conditions were described as likely to persist. Lending and asset markets were called accommodative even after the hike. Inflation prints overnight were a touch soft on key measures. Core readings sat close to target rather than running hot. That combination — a hike, a split board, no sprint signal — is exactly how you get a weaker currency and a steeper local curve.
Japanese officials later stressed they would work to keep the foreign-exchange market orderly and would not hesitate to act with partners if needed. Fine. Traders still sold the yen first and asked questions later. If the gap between U.S. and Japanese policy rates stays wide, dollar-yen can drift back toward the 158–160 zone without much drama. I would not treat every rebound in the yen as the start of a new regime. Differentials still matter more than speeches.
Tech Leadership, Single-Stock Noise, And The AI Bid
Alphabet was the clear premarket leader among mega-cap peers, up more than 2%. Nvidia’s chief executive said he expects to sell twice as many chips in the coming year as artificial intelligence spreads across industries. That kind of comment does not need a press release to move sentiment. It just needs a market that already wants to believe the cycle has more runway.
Not every name played along. Netflix dropped nearly 3% after a downgrade that cited worrying engagement trends. A storage company took another cut to hold after an outlook trim. A tax-software name was little changed after an investor day; analysts still called it a show-me story in the AI era. A semiconductor-device firm rose after an upgrade on valuation. A ticketing platform gained after an upgrade on robust quarterly trends. A meat producer ticked higher on an overweight call. A biotech name collapsed about 27% after it paused enrollment in depression studies. That last one is a reminder that expiration days are also ordinary stock-picking days. The index can look flat while individual names go vertical or fall through the floor.
Crypto-linked stocks were bid after regulators cleared a path for digital versions of securities to start trading. European telecoms sold off on competition worries from satellite operators and from agentic AI tools that could disrupt service models. Software, left for dead earlier in the year on AI-displacement fears, is trying to stage a recovery. I find that swing interesting. Markets love a narrative, then they love the rebound from the narrative.
- Mega-cap tech is still setting the tone for index futures.
- Single-name downgrades and clinical pauses are creating wide dispersion under a calm headline index.
- Chip demand comments continue to outweigh most macro jitters in the short run.
- Software is no longer priced as if it is about to vanish.
Oil, Metals, And The Geopolitical Overlay
The week started with Brent at a four-month high and 10-year yields at levels not seen in a very long time. Chipmakers were under pressure on existential-AI chatter. Then a U.S. rate move helped the inflation-fighting story, Middle East supply worries eased in spots, and the chip supply-demand imbalance kept profit outlooks intact. That is a lot of narrative compression in five sessions.
Energy still sits in the middle of every forecast. A major producer told some European refining customers they would not be allocated crude next month. That put supply risk back on the desk even as prices pulled back from the week’s peak. Escalatory strikes in the Gulf appeared to slow, and traders started looking through incident reports toward talks. Conditions for reopening a key waterway were floated through intermediaries. None of that is a peace treaty. It is enough, some days, to clip $2 off the barrel and let equities breathe.
Gold’s grind higher fits the same messy picture. Lower yields on some days, residual inflation fear on others, and a habit of buying metal when diplomacy and energy headlines refuse to line up. Copper regained a high handle as Chinese demand gauges improved and domestic output slipped a bit. Base metals do not need a boom. They need the fear of a bust to fade.
Perhaps the most interesting aspect is how quickly the oil tape can change the bond tape. A two-day drop of more than 3% in Brent was enough, earlier in the week, to help the 10-year yield post its largest daily decline in months and to snap an eight-session losing streak in Treasuries. Today yields are up again. That is not inconsistency. That is a market that still treats energy as the swing factor for inflation expectations.
Asia First, Europe Cautious, Flows Quietly Supportive
Asian stocks rose on the back of Wall Street’s rebound and a friendlier oil print. A regional gauge of chipmakers jumped about 3.5%. South Korea led with a gain near 2.7%. Taiwan, China and Hong Kong followed. Japan advanced after the rate decision, helped by the weaker yen. Most sectors outside tech were softer, which tells you the rally was narrow. Chinese optical names firmed after a large equipment maker said near-packaged optics modules would ship in coming quarters. Robotics-component suppliers extended gains on reports of fresh audits tied to humanoid-robot production plans. The Philippines lagged on higher local energy-cost fears.
Europe opened on the back foot. A pan-European benchmark was down about 0.4%, with telecoms and insurance weighing and technology plus healthcare holding up. Nestlé traded lower after a decree placing local stakes under temporary administration. Still, the region was on track for its first weekly advance in three as oil retreated. Strategists in one survey were the most constructive on European equities for September in years, citing earnings as a cushion against energy and yields. I would take that with a grain of salt. Surveys look brilliant until the next supply shock.
Fund-flow data added a quieter bullish footnote. U.S. equity funds saw the largest weekly inflow in three months, around $64 billion. That does not guarantee a melt-up. It does mean cash has been coming back while the calendar turns toward expiration and rebalance. Bloom Energy, Illumina and another name are slated to join a major U.S. benchmark. A large space company is due a heavier Nasdaq-100 weight. Those mechanical bids matter more on a Friday than any speech.
Policy Speeches, Data, And The Calendar After Blackout
The communications blackout around the latest U.S. rate decision is over. A Fed governor speaks in the morning. A regional president follows later. August industrial production, manufacturing output and capacity use print at 9:15 a.m. The leading index follows at 10. None of those releases is priced as a regime-changer. They can still nudge the front end if the factory complex looks hotter or colder than the 0.3% monthly guesses.
Abroad, UK retail sales beat, German producer prices ran hot, and euro-area consumer inflation expectations ticked up a tenth or two across horizons. Several European officials sounded alert to second-round effects without promising an immediate encore hike. Australian officials warned that some upside inflation risks look like they are materializing and that businesses are more willing to pass through costs. The global hiking cycle is not a myth. It is also not a parade in lockstep. Each board has its own dissenters, its own energy shock, and its own politics.
Tariff timing is another hanging thread. New duties on China and other partners are expected to wait until after a leaders’ meeting next week. Artificial intelligence — chip access and safety rules — is widely expected to dominate that conversation. Corporate finance is already acting as if the AI buildout needs more cash. One conglomerate increased a margin loan backed by its chip-unit shares by $5 billion, to $25 billion. That is a funding choice, not a morality play. It tells you how expensive the race has become.
How Traders Might Frame The Session
Think of today as three overlapping games. First, the mechanical game: options expire, hedges come off, indexes rebalance. Second, the macro game: yields, oil, the yen, and whatever a Fed speaker lets slip. Third, the narrative game: is AI still the only growth story that can outrun tighter financial conditions?
- Watch whether the 10-year yield can hold below 5% once New York cash bonds are open for real size.
- Watch whether mega-cap leadership broadens or stays trapped in a handful of names.
- Watch crude for any headline that reopens the supply-risk premium.
- Watch dollar-yen for signs that intervention talk is more than talk.
- Watch single-name gaps around rebalance candidates after the close.
Dispersion trades that lived off rich single-stock volatility versus index vol have had a tougher stretch since midsummer. If expiration removes some of the pinning, that premium could behave differently next week. I am not calling a volatility explosion. I am saying the dampener is smaller after today.
Corporate Footnotes That Still Move Money
A legendary holding company founder is stepping down as chairman, with his son slated to take the role. That is succession, not a strategy overhaul, but markets love a headline they can file under “era ending.” A food giant and a retailer saw Russian operations placed under temporary administration. Airport-concession advice mandates, a long-haul aircraft order rumor, and a claim that a large share of one lab’s research work is now driven by its own chatbot all sat in the same overnight pile. None of those items sets the S&P by itself. Together they remind you that geopolitics and governance never leave the tape, even on an expiration Friday.
Drug-pricing talk, a confirmed livestock-parasite case in a border state, and visa approvals for officials attending a high-level meeting in New York belong in the same bucket. They are not the reason futures are unchanged. They are the reason a quiet morning can still produce an afternoon headline.
Putting The Week In Perspective
Monday’s mood was grim: expensive oil, old-looking bond yields, and a tech complex arguing with itself about whether its own invention was a threat. By Thursday the S&P had its best session in over a month, jobless claims looked tidy, and crude had slipped enough to let duration catch a bid. Friday is the digestion session. Futures flat does not mean the argument is over. It means the argument is waiting for the mechanical flows to finish.
I’ve found that investors get into trouble on these days by treating the open as the story. The open is the placeholder. The story is whether yields keep rising into a $7 trillion expiration, whether oil stays heavy, and whether the same five or six stocks can keep carrying the indices while the rest of the market argues about insurance, telecoms, and meatpackers.
If diplomacy takes even a small step in the coming weeks, both bonds and equities could catch a friendlier breeze. If energy supply tightens again, the curve can flatten for the wrong reasons and the equity multiple can look expensive in a hurry. Midterm politics will creep into the conversation as platforms get bolder. That is later. Today is plumbing, prices, and patience.
Stay light on certainty. Stay heavy on levels. And remember that a market that refuses to move at 8 a.m. often makes its real decision after the options clock runs out.