

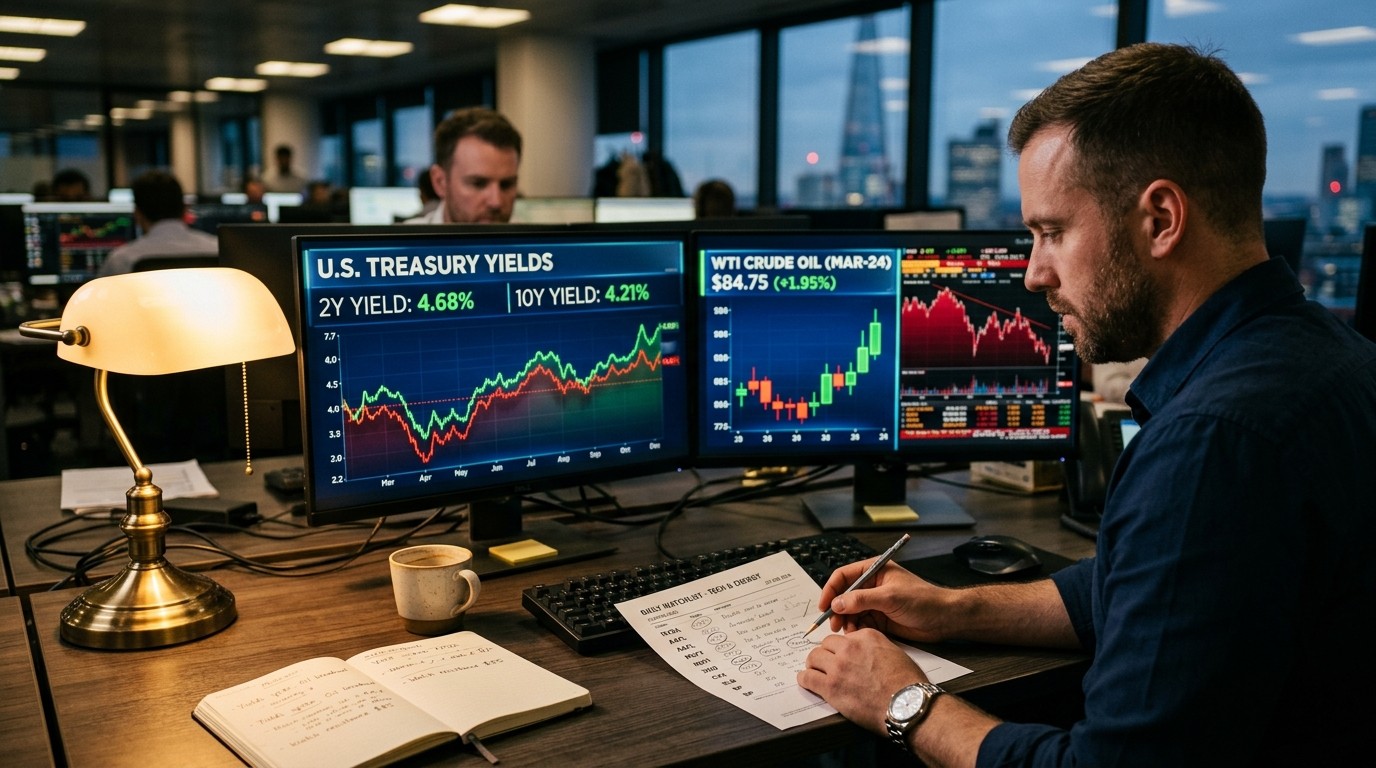

Have you ever watched a perfectly decent Monday get wrecked by two numbers that have nothing to do with the company you actually own? Oil rips higher. Treasury yields follow. Indexes slump. Suddenly every conversation turns into an exit plan. I have sat through enough of those sessions to know the instinct. Sell first, think later. That instinct feels responsible. It is also how people miss the names that keep working when the tape is ugly.
Why Oil And Yields Still Rule The Tape
The market does not need a new story every week. It recycles the same two villains. Crude sets the inflation mood. Bond yields set the cost of money. When both rise together, multiples compress and risk appetite thins out. Monday was a textbook version. Yields jumped at the open. The Dow lost hundreds of points. The S&P 500 and Nasdaq slipped almost in lockstep. Crude had been soaring earlier, then eased after talk of possible sanctions relief, but the damage was already baked in by the close.
That pattern is not mysterious. Higher oil feeds input costs and keeps inflation sticky in the public mind. Higher yields make future cash flows look cheaper in present-value math. Growth stocks feel it first. Highly levered balance sheets feel it next. The broad index does not pause to ask whether your particular holding has pricing power. It just sells the basket.
Here is the part I keep repeating to myself. Trying to time every twist in crude or the ten-year is a full-time job with a lousy hit rate. Long-term money does better when it asks a narrower question. Which businesses still have demand, pricing power, and scale when the cost of capital is rising? If a company has all three, higher rates tied to geopolitical noise hurt less than the headline suggests.
You do not abdicate. You do not declare the situation impossible. You get more selective and you double down on the names that can still deliver.
What Demand, Pricing Power, And Scale Actually Mean
Those three words get thrown around like slogans. They are not slogans if you treat them as filters.
Demand means customers keep showing up even when budgets tighten. Not one-off hype. Recurring need. A product cycle that is already in motion, not a slide deck about a cycle that might arrive.
Pricing power means the firm can lift prices or hold margins without losing the account. In a higher-oil world, that often separates commodity processors from platforms that sit closer to the end user.
Scale means the cost structure can absorb a rate shock. Big installed bases. Distribution that smaller rivals cannot copy overnight. Cash that funds the next product without begging the bond market every quarter.
I have found that portfolios break down when people own only one of the three. Demand without pricing power turns into a volume story with shrinking margins. Pricing power without scale can still get picked off by a well-funded competitor. Scale without demand is just a large company shrinking in slow motion. The filter only works when all three sit in the same ticker.
Tech Names That Still Fit A Tighter Tape
Technology usually suffers first when yields jump. Duration is long. Valuations assume years of cheap money. That is why the interesting work is not “is tech dead.” The work is “which tech names have a product cycle that does not need perfect macro weather.”
Start with the social giant that keeps turning attention into infrastructure. The company is rolling a personal assistant designed to live inside an already massive user base. That matters more than another standalone chatbot fighting for a niche audience. Distribution is the unglamorous advantage. Billions of people already open the apps. If the assistant is good enough, it does not need to invent a new habit from zero. It rides an existing one. In my view, that is how market share fights get decided when capital is no longer free.
Then there is the chipmaker trying to crawl back from years of missed cycles. Central processors for agents still need silicon that is reliable, available, and cheaper than the flashiest accelerator in every workload. A more disciplined spending plan and a serious foundry push change the story from “turnaround rumor” to “execution watch.” Faith in a turnaround is never free. You watch capex, you watch customer wins, you watch whether management stops promising the moon and starts shipping wafers. Still, demand for compute is not a fashion. Agents need cores. That demand sits underneath the noise about yields.
Software with an assistant layered across office suites is quieter, and that is the point. Copilot-style tools do not need a keynote every week to keep attaching to seats that enterprises already pay for. Attachment is a dull word. It is also how software compounds when CFOs freeze new vendor lists. If the tool sits inside the workflow, cancellation becomes a political decision, not a line-item cleanup.
Hardware with a consumer cult following is a different animal. A first foldable device is not a guarantee. Product cycles slip. Prices start high. Early units can look like toys. Even so, a company that already owns the upgrade treadmill has a shot at turning a form-factor change into a replacement wave. I would not bet the farm on one gadget. I would watch whether the install base treats the new shape as a reason to stay inside the ecosystem rather than shop around.
- Look for product cycles already in market, not vapor.
- Prefer distribution that already exists over distribution that must be bought.
- Treat capex discipline as a feature when rates are rising.
- Ask whether the customer can delay the purchase for a year. If yes, size the position smaller.
Energy Is Not A Side Bet When Crude Is The Story
When oil is the problem for the index, it is often the solution for a slice of the market. That slice is not every driller with a press release. It is producers with global footprint and balance sheets that can fund dividends through a messy geopolitical week. It is midstream names that move molecules whether the headline is hawkish or conciliatory.
A major integrated producer with operations spread across regions is less of a single-country hostage. Scale here is literal. Wells, pipelines, trading desks, and a treasury that can refinance without drama. Higher crude is not theoretical for that model. It shows up in cash generation, then in the capacity to keep returning capital.
Pipeline operators live in a different rhythm. Volume and contracts matter more than the last tick on the front-month contract. A mid-single-digit yield is not exciting in a meme chat. It is useful when bond yields are climbing and you still want equity exposure that pays you to wait. Natural gas exposure through a midstream partnership adds another lane. Power demand from data centers did not vanish because the ten-year sneezed.
I am not arguing that energy is risk-free. Politics can flip a session in an hour. Relief talk can knock crude off its highs and take the group with it. That is why position size matters more than slogans about “buy the dip in oil.” Own the operators that still make money if crude settles a few dollars lower than the panic high.
| Filter | Tech tilt | Energy tilt |
| Demand | New product cycle, installed base | Global production and contracted volumes |
| Pricing power | Software attach, brand upgrade path | Commodity realization plus fee businesses |
| Scale | Balance sheet and distribution | Footprint and investment-grade funding |
| Main risk | Multiple compression from yields | Headline reversals in crude |
Why Abandoning The Market Is The Lazy Trade
Cash feels brilliant on a red Monday. It feels less brilliant six months later if the names with real demand kept compounding while you waited for a perfect all-clear. Markets rarely give a perfect all-clear. Yields settle, oil wobbles, then a new scare arrives. If your process is “I will buy when both foes go quiet,” you may wait through an entire product cycle.
Selectivity is not the same as stubbornness. You can cut the companies that fail the three-part test. You can refuse to average down in stories that only work when money is free. You can still hold the ones that keep printing cash or shipping product. That is not hero trading. That is adult portfolio work.
Perhaps the most interesting aspect is how quickly commentary swings from “nothing works” to “everything is fine.” Both takes are usually wrong in the same week. The tape is allowed to be two-sided. Energy can help. A handful of tech names can still grow. The index can still finish lower. Those facts can coexist.
A Practical Checklist Before You Add Risk
- Write down how the company makes money if oil stays elevated for two more quarters.
- Write down how it funds itself if yields stay sticky.
- Identify the product or contract that is already selling, not the one promised for next year.
- Decide the maximum position size if crude reverses 5 percent in a session.
- Revisit the thesis after the next earnings print, not after the next headline.
That list looks simple. It is supposed to. Complicated frameworks collapse when the open is chaotic. A one-page note beats a twelve-tab model you will not open on a red day.
How Bond Yields Change The Kind Of Winner You Want
Rising yields punish duration. They also reward businesses that convert sales into cash without stretching payables into next decade. I keep coming back to free cash flow conversion because it is less glamorous than revenue growth and more honest when discount rates move.
A software attach story that improves retention can support a premium multiple even when the ten-year is unfriendly. A chip turnaround that still burns cash needs a longer leash and a smaller weight. An energy major that funds the dividend from operations does not need you to believe in a new multiple. It needs you to believe the barrels keep coming.
In my experience, people confuse “quality” with “expensive compounder everyone already owns.” Quality in a squeeze is closer to this: customers cannot easily leave, prices can flex, and the balance sheet does not depend on a friendly primary market next Tuesday.
Geopolitics Will Keep Hijacking Sessions
Oil is not only a supply-demand spreadsheet. It is a political instrument. Comments about sanctions, relief, or escalation can reverse crude midday and drag equities with it. That is frustrating if you like clean narratives. It is normal if you have watched this market for more than one cycle.
The useful response is not to become a foreign-policy desk. The useful response is to own companies whose earnings do not require you to predict the next statement. Global production helps. Contracted midstream cash flows help. Consumer ecosystems with replacement cycles help. Niche stories that only work if crude stays at the morning high do not help.
I will say this plainly. If your entire book only works when headlines are calm, you do not have a book. You have a weather report.
Building A Watchlist That Survives Ugly Opens
A watchlist for this tape should look slightly boring. A few large technology platforms with live product cycles. A chip name if you accept execution risk and size it that way. One or two energy operators that pay you while you wait. Maybe a midstream name whose yield still competes with cash after you adjust for the usual partnership structure questions.
What should not be on the list? Companies that need multiple expansion to make the math work. Stories that need oil to stay at a spike price. Balance sheets that refinance into a hostile curve. Anything you cannot explain in two sentences to a skeptical friend.
Squeeze filter, short version:
  Demand that is already visible
  Prices that can move without losing the customer
  Scale that funds the plan without emergency dilution
Keep the list short. Five to eight names beat twenty ideas you will not monitor. The point of a turbulent tape is not to collect tickers. It is to know which ones you are willing to add if the index dumps another half percent for reasons that have nothing to do with their customers.
Dividends, Duration, And The Temptation To Hide
When yields rise, income starts looking competitive again. That can be healthy if the dividend is covered. It can be a trap if the yield is high because the price already knows the distribution is shaky. Midstream names with histories of covering the payout through volume, not through hope, belong in the conversation. Growth names with no yield can still belong if cash conversion is real. Hiding in cash is a position too. Just admit it is a position, not a moral high ground.
I have watched investors treat a 5 to 6 percent equity yield as a substitute for thinking. Yield is a tool. It is not a personality. Pair it with coverage ratios and asset quality, or you will learn an expensive lesson the first time crude mean-reverts.
What “Doubling Down On Winners” Should Not Mean
The phrase is easy to abuse. Doubling down is not averaging a loser because you are annoyed. It is adding to the company that is still clearing the three filters after the tape has tried to shake you out. That requires homework you already did on a calm weekend, not a market order placed in the last hour because a commentator sounded confident.
Winners in this environment may lag for days. Meta-style platforms can still trade with the Nasdaq on a yield scare. Energy can give back a spike. The test is whether the operating story changed. If it did not, the red print is a price, not a thesis funeral.
In turbulent stretches the ideas are still out there. They are just fewer, and they demand that you stop treating the whole market as one trade.
A Longer View For People Who Hate Daily Drama
If you invest through a workplace plan or a simple brokerage account and you do not live on the open, the same filters apply. You do not need to trade crude. You need to know whether the funds or individual names you hold are stuffed with companies that fail the test. Rotate slowly. Tax bills matter. So does sleep.
Product cycles in consumer devices and enterprise software play out over years. Energy capex cycles play out over years. Bond yields can stay uncomfortable for a long stretch without making every good business worthless. That is the unfashionable message. Markets can be squeezed and still contain companies worth owning.
Would I rather have a quiet tape? Of course. I would also rather have coffee that never gets cold. Neither wish is a strategy.
Putting The Pieces Together Without Turning Into A Newsletter
Oil and yields will keep hijacking mornings. Indexes will keep overreacting. Commentators will keep offering binary advice. Your job is narrower. Find the firms that still sell something people need, charge enough to protect the margin, and sit on a balance sheet that does not panic when the curve steepens.
Tech can still work if the cycle is real. Energy can still work if the assets are real. Most of the middle of the market will feel like dead money until one of the two foes backs off. That is uncomfortable. It is also how you avoid the worst mistake of a squeeze: selling the handful of businesses that were built for ugly weather because the average stock had a bad Monday.
Stay selective. Stay funded. Stay willing to own something when the screen is red for reasons that have nothing to do with the customer standing at the register. The ideas are out there. They just refuse to announce themselves with a green arrow at 9:31.



