
Have you ever watched the weather shift so dramatically that it starts rewriting the rules for energy prices overnight? That is exactly where we stand right now with this Super El Nino. I have been tracking these ocean patterns for years, and the current setup feels different. The Pacific is running hotter than anything we have measured since the 1950s, and the ripple effects are already showing up in heating markets, power demand forecasts, and the way traders are positioning for winter.
Why This Super El Nino Stands Apart From Past Events
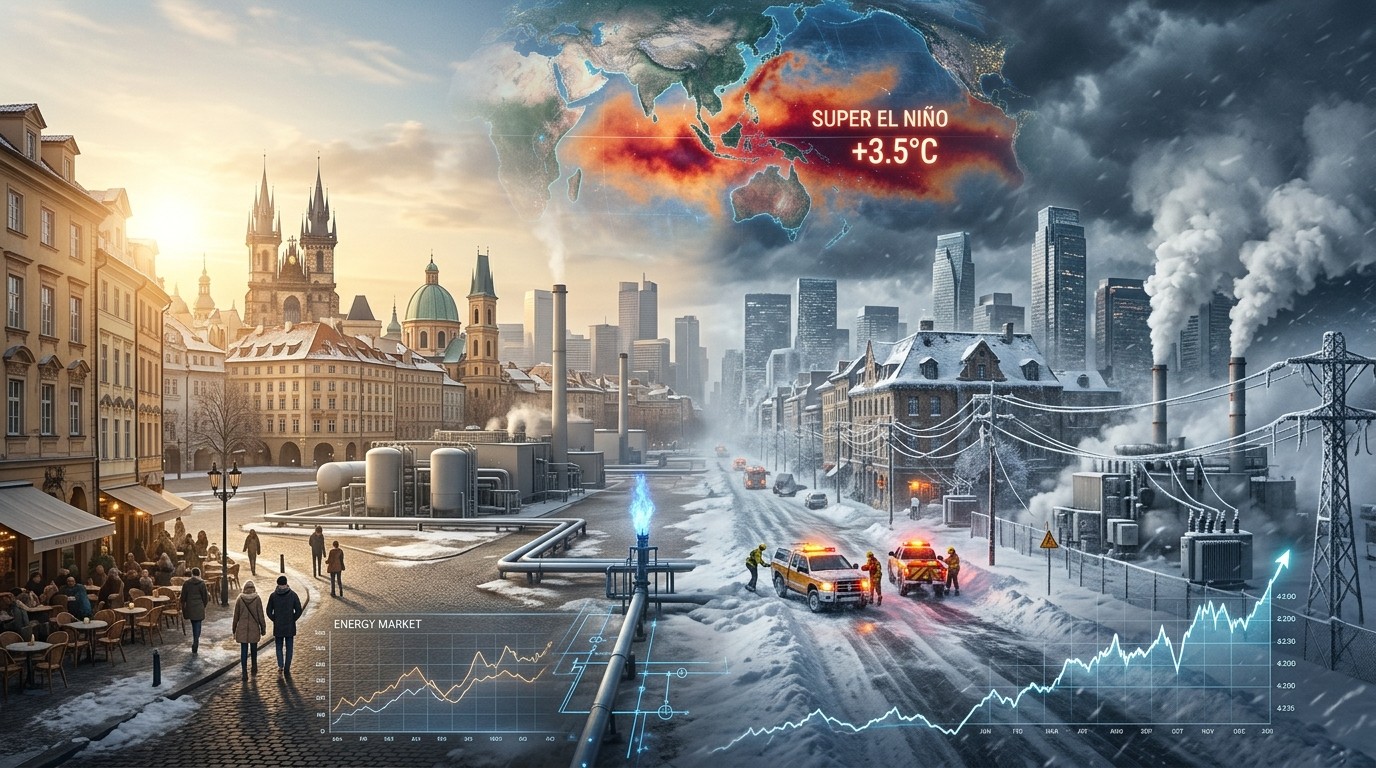
Most El Nino episodes bring a familiar script. Milder winters in some places, wetter conditions in others. This one is writing a new chapter. Sea surface temperatures in the central Pacific have already climbed more than three degrees Celsius above normal in places, and some models suggest peaks above 3.5 degrees. That puts it firmly in Super El Nino territory, the kind of event that only appears a handful of times each century.
What makes the difference is not just the strength but the timing. The event is expected to reach its maximum intensity around January and then slowly fade toward normal conditions by next May. During that window the atmosphere responds in ways that can look orderly on the surface yet hide sharp surprises underneath. I have found that the biggest market moves often come from those hidden surprises rather than the broad seasonal averages.
Energy consumers might breathe a little easier when they hear forecasts calling for above-average temperatures across the northern United States, much of Europe, and parts of Asia. Lower heating demand sounds like good news when refining capacity is tight and certain supply routes remain disrupted. Yet the same pattern that delivers overall mildness can still produce one or two intense cold outbreaks capable of stressing systems that have grown used to milder conditions.
Regional Temperature Signals That Matter Most
The impact is never uniform. In North America the northern tier looks set for temperatures 1.5 to 3 degrees Celsius warmer than normal across the Northern Plains, the Northeast, and parts of Canada. That is meaningful. Every degree of warmth across a large population base reduces natural gas and heating oil consumption in a measurable way. At the same time the southern United States, especially Texas, is more likely to run cooler and wetter than average. The probability of a historic deep freeze is lower than in a typical winter, but the colder baseline still raises the odds of higher demand spikes relative to recent mild seasons.
Europe presents a softer signal. Southern and central regions should average roughly half a degree to 1.5 degrees above normal. Northern Europe looks only modestly warmer. The net effect still points toward reduced heating demand, which arrives at a moment when storage levels and pipeline flows are under constant scrutiny. I keep coming back to the idea that mild seasons can lull markets into complacency until a sudden Arctic outbreak forces everyone to scramble for supply.
Asia is more mixed. Confidence is highest for above-normal temperatures in India and Japan. China remains harder to pin down because continental air masses and complex terrain often override the Pacific signal. That matters because northern China carries a large share of the country’s winter energy demand. A weaker warming signal there leaves open the possibility of stronger cold periods that local markets would feel quickly.
The Black Swan Risk Hiding Inside a Mild Winter
Here is the part that keeps me up at night when I look at energy portfolios. Super El Nino winters are statistically milder on average, yet they have a habit of producing short, sharp extremes. Meteorologists following this event talk about the potential for powerful nor’easters that coincide with Arctic air plunges. Picture major Mid-Atlantic and Northeast cities buried under heavy snow and ice even while the seasonal average remains warm. Those episodes tend to last one to two weeks and are most likely between late January and early February.
Overall the implication for energy markets is lower-than-average heating-related demand for this winter, but one or two intense cold snaps could still create sudden and severe pressure on tight supplies.
Those black swan windows are exactly where risk management becomes more important than seasonal averages. Power grids, natural gas pipelines, and heating oil inventories can handle gradual cold. They struggle more when temperatures crash and precipitation turns to freezing rain or heavy wet snow at the same time. The systems have less spare capacity than they did a decade ago, so even a short disruption carries larger price consequences.
Beyond Temperature: Wind, Rain, and the Quiet Hurricane Season
Temperature is only part of the story. Wind patterns are expected to shift southward across the United States, which often means stronger average wind speeds in key renewable generation regions. That could provide a modest boost to wind power output during the colder months. Europe’s wind outlook is less clear, so the benefit may not travel across the Atlantic in the same way.
Precipitation also diverges by region. The southern United States looks wetter and stormier, which should improve water availability for hydro and other uses. Europe, by contrast, is expected to run both warmer and drier than average. Drier conditions can reduce hydro generation and increase wildfire risk later in the season, adding another layer of uncertainty for power markets.
One quieter aspect of this Super El Nino has been the Atlantic hurricane season. Strong vertical wind shear has suppressed tropical development, and only one significant storm has stood out so far. The absence of late-season storms hitting the Gulf has removed one potential source of supply disruption for energy infrastructure, at least for now. That relative calm has been a small relief in an otherwise tight refining environment.
What Energy Markets Are Already Pricing In
European natural gas futures have been trading near elevated levels even as the seasonal forecast leans mild. That tension tells you the market is still focused on structural supply issues rather than purely on weather. Refining margins remain firm because global capacity has been constrained. Any cold blast that forces higher heating oil demand would hit a system with limited spare room to respond.
In my view the most interesting dynamic is the gap between the seasonal mean and the potential for extremes. Traders who only hedge the average mild outcome leave themselves exposed to those one-to-two-week windows of severe weather. The opposite is also true. Over-hedging for deep cold in a Super El Nino year can become expensive if the cold never materializes at scale. Balance is hard, yet that is exactly where the edge sits.
Perhaps the most interesting aspect is how quickly markets can reprice when a short cold snap arrives. Inventory draws accelerate, prompt prices spike, and the narrative flips from “mild winter” to “supply stress” almost overnight. We have seen versions of this pattern in previous strong El Nino years, though none quite as intense as the current setup appears to be.
Practical Considerations for the Months Ahead
For anyone watching energy exposure, the next several months reward flexibility more than rigid forecasts. The broad signal points to reduced heating demand across many of the largest consumption centers. That should ease some pressure on gas and power prices relative to a colder winter scenario. At the same time the door remains open for disruptive winter storms that can still create short-term shortages and sharp price moves.
- Monitor the late January to early February window especially closely for cold outbreak potential
- Watch southern United States precipitation trends for implications on regional power and agriculture
- Track European storage trajectories even if temperatures run above normal
- Keep an eye on northern China temperature anomalies because the local signal is weaker
- Remember that wind generation could provide a modest offset in certain U.S. regions
I have found that the best approach in these unusual seasons is to treat the mild outlook as the base case while maintaining contingency plans for the black swan events. Those plans do not need to be elaborate. They simply need to exist before the first major snowstorm warning appears.
Looking Past Winter Toward the Transition
By next spring the Super El Nino should be fading. The transition period itself can bring its own weather volatility as the atmosphere readjusts. For energy markets that often means shifting attention from heating demand back toward cooling demand and the start of the next hurricane season. The memory of this winter’s extremes, or lack of them, will influence how inventories are managed and how aggressively positions are built for the following year.
The current event also serves as a reminder that climate patterns of this magnitude still dominate seasonal energy balances even in a world of growing renewable capacity. Solar and wind can help, yet they do not eliminate the fundamental link between temperature and fossil fuel demand during the coldest months. Until storage and transmission systems become far more robust, these large-scale ocean oscillations will continue to move markets in decisive ways.
What stands out most to me is the combination of high confidence in the overall mild signal and the explicit acknowledgment of outlier risk. That combination is rare. Most winters offer murkier forecasts. This one hands us a clearer directional bias while still waving a red flag about short-duration extremes. How markets choose to price that combination will tell us a lot about risk appetite heading into the heart of the season.
The strongest Super El Nino in more than seventy-five years is already reshaping expectations for winter energy demand. Warmer conditions look likely across many major consumption regions, yet the same pattern that delivers mild averages can still generate intense, short-lived cold and snow events capable of stressing tight supply systems. Staying alert to both the broad outlook and the black swan windows may prove the difference between a relatively calm heating season and a series of sharp, expensive surprises.
In the end the atmosphere rarely follows the simplest script. This Super El Nino is offering a clearer mild bias than most recent winters, but it is also reminding us that averages can hide extremes. For energy markets that dual reality is the real story of the season ahead. Those who prepare for both sides of the distribution will be better positioned no matter which version of winter actually arrives.