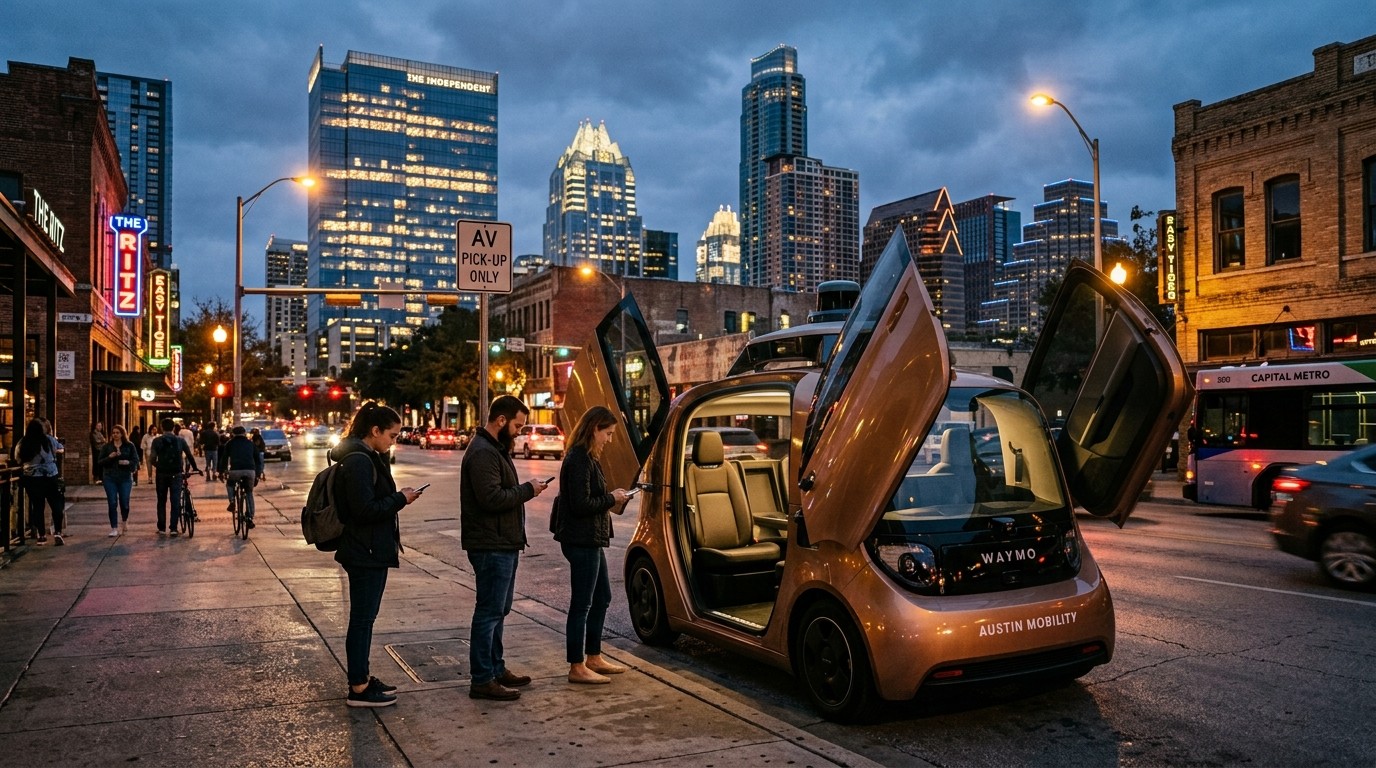

The launch date was September 3. The city was Austin. The vehicle is strange on purpose: no steering wheel, no pedals, no mirrors, no outside door handles. Butterfly doors swing up. A trunk that does not always latch the way a person expects. A cabin built around a large screen. Some riders loved the quiet of having the whole pod to themselves. Others posted videos of pickups in the wrong place and drop-offs that made them walk farther than they wanted. Wait times, in the first rush, stretched long enough to kill the mood of a night out.
None of that is fatal on its own. Early ride-hail services, human or not, are messy. What makes this month matter is the clock behind it. The core car business has been under pressure for a while. Shares were down about 18 percent on the year heading into the latest delivery print, the lone megacap tech name that had not managed a positive return. Friday’s better-than-expected third-quarter deliveries lifted the stock nearly 5 percent, yet deliveries were still about 2 percent lower than a year earlier. Investors are not buying the bronze pod because it looks cool in a downtown photo. They are buying the idea that it becomes a volume product and a network. That idea now has to leave one city.
The Real Test Starts After The Photo Op
A debut is a moment. Expansion is a habit. I have found that markets forgive a clumsy first weekend and then get impatient the second the company starts talking about the next map. Austin was the friendly room: relatively loose state rules, a tech crowd willing to try odd hardware, and a hometown advantage that is hard to copy in Dallas traffic or a Florida tourist corridor. The next rooms will be less sentimental.
Perhaps the most interesting aspect of the first month is how ordinary the complaints were. Not a dramatic crash narrative. Not a viral failure of the driving model in a rainstorm. The gripes were about time, place, and doors. Those sound small until you remember that a ride service is a promise about time and place. If the car is smooth and the handoff is sloppy, the rider remembers the handoff.
What The Permit Count Actually Says
State motor vehicle records are a blunt instrument, and still they are one of the few public scoreboards that do not depend on a launch video. At the unveiling, 45 Cybercabs were authorized for commercial use in Texas. By Friday that figure was 169. Almost four times the starting fleet, inside a single month, is real operational movement. It is also a small absolute number next to a rival that already had 1,154 autonomous vehicles authorized in the same state, including 359 of a newer low-step model with sliding doors.
Austin is still the only city where the Cybercab is running as part of the driverless ride-hail service. The Texas robotaxi mix is not only the pod. Another 420 Model Y vehicles carry the company’s automated driving systems and sit in the same broader fleet picture, though those systems are not yet sold to individual buyers in that form. So the story is two hardware paths at once: a purpose-built two-seater with no manual controls, and a more familiar crossover doing driverless work under a different setup.
Does 169 change the competitive math? A little. It shows the company can add authorized units without the count freezing. It does not show that supply has caught demand. An Austin resident who has ridden the pod about 30 times, a former intern now studying computer science and running a public tracker that reads traffic cameras and records, described early waits of 45 minutes or more. Those waits eased as demand evened out. That is the classic early-network pattern. Scarcity flatters the product and punishes the rider.
A permit is permission. A repeat ride is proof. The first month produced more of the former than the latter.
The Passenger Experience Nobody Can Spin
Reviews landed in the messy middle, which is more informative than a cheer or a pile-on. Riders who liked the Cybercab talked about personal space, a large screen, media controls, and a drive that felt smooth. That matches what you would hope from a vehicle designed around the passenger rather than a driver. The cabin is the product. If the cabin feels like a private lounge for twelve minutes, some people will forgive a weird door.
The other half of the feedback is less kind, and I think it matters more for expansion. Long waits. Pickups and drop-offs in the wrong spot. Butterfly doors that stick out and feel less convenient than a normal door or a slider. Trunks that do not always close cleanly. Technical hiccups that turn a simple exit into a small performance. None of these require a lab to understand. They show up the moment a person with luggage, or a person in a hurry, meets the hardware.
Butterfly doors are a design statement. On a quiet street at dusk they look intentional. On a narrow curb next to a bike lane they become a geometry problem. The door needs room the sidewalk may not offer. A rider who has used both the pod and a rival service with sliding doors noticed the difference immediately. Convenience is not a slogan here. It is shoulder clearance and the number of steps between the car and the restaurant door.
- Early wait times often ran long enough to break plans, then eased as more cars and calmer demand overlapped.
- Wrong-place pickups and drop-offs kept showing up in rider posts, which is a routing and curb problem as much as a driving problem.
- Door and trunk behavior created friction that a smooth ride cannot fully erase.
- The screen-and-space cabin was the clearest win, especially for riders who want the vehicle to themselves.
I keep thinking about how unglamorous that list is. Autonomy debates love edge cases. Paying customers complain about the curb. If the company treats curb quality as a software afterthought, the next city will teach the same lesson at a higher volume.
Why Austin Became The Laboratory
Austin did not win this role by accident. State rules are relatively permissive compared with coastal markets that still want a human at the wheel. The city has a dense tech crowd that will try a new service and then talk about it. The company is local in a way that still carries some goodwill, even among people who argue about the stock. Amazon’s Zoox has also been testing there, so the streets are already a small exhibition of competing robotaxi ideas.
That mix is useful and a little misleading. A laboratory flatters the experimenter. Riders are curious. Local coverage is intense. Employees and fans seed the first weeks. The moment the same vehicle has to work for a visitor who does not care about the brand, the margin for odd drop-offs shrinks. San Antonio and Dallas are the obvious in-state next steps being discussed around the expansion plan, along with Nevada and Florida, where warm weather and friendlier rules tempt every autonomy team. Weather is not a trivia point. Sensors and rider patience both change when the sky does.
California remains the awkward contrast. Rival driverless cars are a common sight in several cities there. The company still has not secured permits to run vehicles on public roads in that state without a human at the wheel. You can call that politics, process, or prudence. From a network perspective it is a hole in the map. A service that cannot operate unsupervised in the country’s biggest car market is not yet a national service, no matter how clean the Austin footage looks.
The Gap With A More Mature Rival
Comparisons are annoying when they become scoreboard worship. They are also unavoidable. A rival service is already open in 15 U.S. markets, with 15 more on the horizon, and has talked about London, Tokyo, and Munich. In Texas alone it had 1,154 authorized autonomous vehicles as of Friday. Nationally it is running more than 500,000 paid rides a week, has logged 270 million fully autonomous commercial miles at home, and fields over 4,000 driverless vehicles in commercial operations.
Those figures are not a moral verdict. They are time. The rival has been doing commercial work longer, which shows up as 24/7 coverage and support that feels less experimental. Even fans of the Cybercab cabin say as much. Early days for the other service in Austin included harsh braking that later calmed down. Maturity is mostly repetition plus the unglamorous work of fixing what riders actually hate.
The hardware philosophies diverge in a way a rider can see without reading a spec sheet. One side is adding a low-step model with doors that slide. The other is betting on a two-seat pod whose doors lift and whose controls live entirely in software. Both can work. Only one of them asks the public to accept a car that cannot be nudged by a human in the ordinary sense. That ask is the whole product bet, and it is also the regulatory sore spot.
| Signal after one month | Cybercab picture in Texas | Why it matters for expansion |
| Authorized commercial units | 45 at launch, 169 by Friday | Shows ramp speed, still a small base |
| Cities with the pod in service | Austin only | The map has not started yet |
| Rider friction | Waits, curb errors, doors, trunks | Repeats will stall if this lingers |
| Reported serious collisions | None significant since commercial debut | Helps the safety case, does not end it |
| Nearby rival scale | 1,154 authorized vehicles in Texas | Sets the local benchmark |
I do not read that table as a eulogy. I read it as a sequence. Fleet first, city second, habit third. The company has moved the first cell. The second and third are the hard part the headline keeps pointing at.
Doors, Drop-Offs, And The Small Frictions That Kill Repeat Rides
There is a temptation in autonomy writing to skip the door. I think that is a mistake. The Cybercab’s butterfly doors extend outward. They look clean in a studio. On a real curb they compete with pedestrians, signposts, and the simple desire not to step into the street to get out. A rider who has tried every public autonomous option in Austin called them less convenient than traditional doors or sliders, even while praising drive quality. That split is the product in one sentence. Smooth motion, awkward arrival.
Drop-off quality is the other quiet killer. A car that stops a block away because the pin was fuzzy, or because the curb was blocked, creates a story the rider tells at dinner. Wrong-place pickups do the same thing in reverse. These are solvable problems. They are also the problems that decide whether a curious first ride becomes a Tuesday habit. Networks die from inconvenience more often than from philosophy.
Trunk behavior sounds trivial until you are holding a bag and the lid will not sit. Early technical complaints included closures that did not behave. In a two-seat pod the trunk is not a bonus. It is half the practical case for using the car instead of walking. If that latch is moody, the vehicle feels unfinished, no matter how confident the driving model is on a straight road.
Wait times tell you about fleet density more honestly than a permit chart. Forty-five minutes is not a service. It is a lottery. The easing of those waits in later weeks is encouraging, and it tracks the rise from 45 to 169 authorized cars plus whatever routing tweaks happened behind the app. Still, equalized demand in one city is not the same as spare capacity. Expansion multiplies the lottery unless the car count rises faster than the curiosity.
What a repeat rider actually scores:
  Ride smoothness      high marks so far
  Cabin and screen     clear advantage
  Door convenience     still a compromise
  Curb accuracy        inconsistent
  Wait time            improved, not solved
Regulators Are Not Done Asking Questions
After the launch, the federal auto safety agency opened an audit query to check whether the vehicles meet federal safety standards. The original response date was September 30. The company received an extension, according to an agency spokesperson. An extension is not a finding. It is a sign that the question list is long and the answers are not a weekend project.
This is the part of expansion that does not care how bronze the paint is. A purpose-built vehicle with no wheel and no pedals sits outside the muscle memory of the rulebook. Standards written for cars that a person can steer have to be mapped onto a machine that can only be steered by code. Audits exist for that mapping. They also exist because a commercial rollout makes the mapping urgent.
I have watched companies treat a query like a public-relations weather event. That usually ages badly. The useful posture is boring: answer completely, show the test trail, and do not pretend a new body style is a footnote. If the extension buys clearer documentation, fine. If it buys time while cars keep taking fares, the public will notice the overlap. Surveys already suggest people react sharply once they hear an investigation is open. More on that mood in a minute.
What First Responders Want That Software Cannot Fake
No significant safety incidents or collisions have been reported in Austin involving a Cybercab since the commercial debut. That sentence should be said plainly. It is good news, and it is early news. A quiet month is not a career.
First responders are already thinking past the quiet month. An Austin fire captain who spoke about the rollout said the company provided detailed emergency guidelines and hands-on instruction for both the Cybercab and the Model Y robotaxi vehicles. That is more than a pamphlet. It is still not what he wants as a standing rule. His ask is simple to describe and hard to build: some way for public safety staff to take control, move, steer, or shut down a vehicle with no wheel and no pedals, in emergencies and in ordinary stuck situations.
He also argued for something like dynamic certification. Software changes the car after the car has been approved. A bug or an update can alter behavior. Testing once, at birth, does not describe a product whose personality can be pushed overnight. National or state rules that force a control path and repeat testing would slow a rollout. They would also answer the objection that keeps showing up whenever a wheel-less car blocks a lane and nobody on scene can creep it forward.
Training is not the same as a control the firefighter can use when the script fails.
The practical worry from Austin first responders
The company did not immediately respond to a request for comment on that point. Silence is not an answer, and it leaves the captain’s framing in the room. Expansion into San Antonio or Dallas will meet new firehouses, new police habits, new street geometries. A guideline packet that worked in Austin has to travel, or each city will invent its own anxiety.
Public Mood Is Still The Quiet Bottleneck
Hardware can be fixed in a sprint. Mood moves slower. A September electric-vehicle intelligence survey found that 50 percent of U.S. respondents would not feel comfortable riding in a robotaxi with no steering wheel and no pedals. After hearing about the federal inquiry into the Cybercab, 70 percent wanted rides paused. Those are not Austin-only figures. They are the national weather the expansion has to fly through.
Comfort is not the same as refusal forever. People adapt to elevators, to autopilot in planes, to cars that park themselves. The adaptation usually follows a long stretch of boring success plus an easy exit. The Cybercab’s design removes the easy exit. There is no wheel to grab. That is the point of the product, and it is also why the 50 percent figure should be read as a design cost, not a rounding error. You cannot market your way past a missing pedal if the rider’s mental model still includes one.
The 70 percent pause reaction is more situational. Investigations spook people, sometimes more than the underlying record. A month with no significant reported collisions is the counter-argument, and it has to be repeated without turning into a boast. Boasts age poorly if the next month is different. In my experience, the companies that earn trust here talk about limits in the same breath as miles. The ones that only talk about miles end up explaining a clip.
- Show uneventful miles without pretending uneventful means finished.
- Fix the curb and the door so the first ride does not become a complaint thread.
- Give responders a control path they can trust when software is not enough.
- Answer the audit with documents, not atmosphere.
- Add cars faster than curiosity, or the wait-time story returns in every new city.
The Map That Was Promised And The Map That Exists
In January, at a global forum in Davos, the claim was that robotaxis would be very, very widespread in the United States by the end of 2026. That has not happened. Saying so is not a gotcha. It is the baseline for judging the next sentence about San Antonio, Dallas, Nevada, and Florida. Widespread is a network word. One city plus a permit ramp is a pilot word. Both can be true in sequence. They are not true at the same time.
The honest expansion path, if I sketch it the way an operator would, looks narrower than a keynote. Deepen Austin until waits are dull. Prove the door and trunk behavior on messy curbs, not demo streets. Carry the responder playbook into a second Texas city before promising a third. Use Nevada and Florida for weather and regulatory variety, not as trophies. Treat California as a separate campaign with its own clock, because the permit reality there has not moved to unsupervised public-road service.
Rival teams are already writing international footnotes. London, Tokyo, Munich. That does not mean those launches will be smooth. It means the comparison set is no longer “who can demo in Texas.” The comparison set is who can keep a paid ride boring in more than one legal system. Boring is the compliment.
Why The Car Business Makes This Urgent
Strip away the pod and the stock story is familiar. Auto sales have been sluggish for an extended stretch. The core automotive unit has posted consecutive annual revenue declines. Chinese makers, including brands selling cheaper and more novel models, have been gaining ground and pushing exports into markets that used to be safer, especially across Europe and Asia. A delivery beat can lift a Friday. It does not erase a 2 percent year-over-year drop, and it does not rebuild pricing power by itself.
That is why the robotaxi and Cybercab narrative carries so much weight with investors. It is the path offered when the metal-and-margin story cools. Analysts at one brokerage, after the Friday delivery report, underlined the scale of the claim management has already made: once production ramps, the Cybercab is expected to become the highest-volume vehicle in the lineup. Highest volume. Not a niche shuttle. Not a brand halo. The main car.
I find that claim bracing, and I also find it early. Highest volume assumes a factory rhythm and a city rhythm at the same time. Factories can stamp pods faster than cities can absorb them if permits, curbs, and public comfort lag. The reverse is also possible. Demand in a second and third city could outrun the 169-unit base so quickly that wait times snap back to the bad early weeks. Either mismatch shows up in the same place: the rider’s phone.
Shares down 18 percent on the year, then a near 5 percent bounce on deliveries, tell you the market is trading the turn, not the arrival. The only megacap tech name in the red for the year does not get a long honeymoon for a pilot. It gets a month of attention and then a demand for the next datapoint. The permit jump from 45 to 169 is one datapoint. Paid rides per car, completion rate, and support contacts would be better ones. Those are not in the public tally. Until they are, outsiders are stuck inferring service quality from videos and from people kind enough to count their own trips.
Two Fleets, One Brand, Different Jobs
It is easy to mash the Cybercab and the Model Y robotaxi into one word. They share a city and a company. They do not share a body. The 420 Model Y units in the Texas robotaxi picture still look like cars people already understand. The Cybercab does not. That difference will matter when something goes wrong, and it matters when something goes right. A familiar shape lowers the flinch. A new shape has to earn the lack of a flinch.
Running both is a hedge and a complication. The hedge is obvious. If the wheel-less pod hits a regulatory wall, the more conventional vehicle can keep the network story alive. The complication is support, training, and public language. First responders were briefed on both. Riders will compare both. A brand that says “robotaxi” and then delivers two different door philosophies will spend time explaining itself. Explanation is not fatal. It is friction, and friction is the theme of the month.
There is also a product-line tension worth naming. Management has pointed at the Cybercab as the eventual volume leader. The Model Y is the volume leader people can buy today. If the pod is the future lineup anchor, the factory plan, the safety case, and the city plan all have to point at the same object. Right now the street proof is still an Austin pilot plus a permit ramp. The volume claim lives a few steps ahead of the street.
What Riders Are Really Grading
Talk to enough early users and a grading sheet appears, even if nobody prints it. Drive quality sits near the top for the Cybercab. People notice smoothness. They notice the absence of a stranger in the front seat. They notice the screen. Those are assets. A 20-year-old who has taken both services since the rival arrived in Austin in 2024 put it in plain language: own space, massive screen, media controls, apps, very smooth. Then the caveats. Pickup and drop-off not refined. Doors less convenient. Patience required.
Patience is a luxury of a launch month. It is not a feature you can ship to Dallas. A visitor with a flight does not have 45 minutes of goodwill. A parent with a pickup window does not want a poetic door. The service either respects the clock or it becomes a story people tell against you. I suspect the company knows this. Knowing it and staffing enough cars are different tasks.
Support is the other grade that maturity buys. The rival’s longer commercial history shows up as round-the-clock coverage and a help path that feels less like a beta. Early Cybercab riders who hit a door glitch or a bad pin were, in effect, part of the debugging team. That can be charming for enthusiasts. It is a poor contract for a paid fare. Expansion before support catches up exports the beta.
Cost, Competition, And The Volume Dream
The strategic logic for a cheap, simple, two-seat autonomous pod is not mysterious. Take out the driver. Take out controls a driver would use. Shrink the cabin to the trip people actually take. If the utilization is high, the cost per mile can undercut a human ride and, eventually, the ownership math for a second car. That is the slide. The street version needs the utilization, which needs the density, which needs the permits, the cars, and the trust.
Chinese competition makes the slide more urgent, not less. When affordable, inventive models are taking share and export lanes, a carmaker cannot live on brand heat alone. A network business with software margins is the offered answer. It only becomes an answer when rides are frequent enough to matter in a financial model. A few hundred authorized units in one state are a start. They are not a second pillar of revenue yet.
Analysts emphasizing the volume opportunity are doing their job. They are also describing a conditional. Once production ramps. Once the largest-volume claim stops being a forecast and starts being a delivery line. Conditions are where pilots go to linger. The useful investor question is not whether the pod could be the volume car. It is what evidence, quarter by quarter, would show the condition being met. Authorized units are one line. Cities in service are another. Completed paid rides are the line that still sits mostly offstage.
A Second City Will Be Less Romantic
Austin’s tech crowd will try a bronze pod because it is there and because the story is local. San Antonio does not owe the product that courtesy. Dallas traffic will not pause for a butterfly door. Florida tourists will judge the app the way they judge any other ride button. Nevada’s layout and rules may help, and they will not supply the patience of a launch week. The hard part is not announcing the next city. It is arriving with enough cars that the first weekend does not recreate the 45-minute wait.
Regulatory texture changes by state even when the headline is “friendly.” An audit at the federal level travels with the vehicle wherever it goes. A fire captain’s request for a control path will be echoed by someone in the next city who was not in the Austin training session. Dynamic certification, if it ever becomes a rule, would force the software update habit into the open. None of this is a reason to freeze. It is a reason to expand slower than a keynote and faster than a skeptic expects. That narrow band is the whole management problem.
Zoox testing in the same city is a reminder that Austin is a stage, not a moat. Multiple teams can share a permissive state. The team that leaves with repeat riders, not just test miles, keeps the advantage. Right now the repeat-rider evidence is anecdotal and mixed. That is normal for week four. It will not be normal for week forty.
Safety Quiet Is A Start, Not A Shield
I want to be careful here. No significant reported collisions in the commercial window is meaningful. It should not be inflated into a lifetime claim, and it should not be dismissed because the sample is small. Both errors are common. The fair reading is that the debut month did not produce the incident that would have frozen the conversation. The audit, the door design, and the responder control gap are still live issues beside that quiet.
Public surveys sit on the other side of the same coin. Half the country uneasy about a wheel-less ride. Seven in ten, once an investigation is mentioned, inclined to pause. A company can disagree with the instinct and still has to live with it. Expansion into new cities imports that instinct. Local fans will not outvote it. Only uneventful repetition, visible support, and a credible emergency story move it.
Software updates cut both ways. They let a team patch a harsh brake or a bad pin without recalling metal. They also mean yesterday’s good month is not a lock on next month’s behavior. That is the core of the dynamic-certification argument, and it is a fair argument even if the regulatory form it takes is still unsettled. Riders do not experience version numbers. They experience the ride they got.
What Would Count As A Real Second Month
If I were scoring the next thirty days as a reader rather than as a fan or a short, I would look for dull improvements. Shorter median waits, not a single lucky afternoon. Fewer wrong-curb stories, not a promise that routing improved. Doors that open and close without a clip. Trunks that latch. A public note on the audit that contains answers, not just a new date. A second city only if the first city’s support line can absorb it.
Permit growth can continue and still be the wrong headline. Going from 169 to a few hundred authorized Cybercabs would look good in a chart and mean little if half of them sit idle or if the active half still miss the pin. Conversely, a slower permit ramp with cleaner rides would be the more bullish story, and it would photograph worse. Markets often pick the photograph. Riders pick the pin.
The delivery bounce on Friday bought attention. Attention is a perishable inventory. By the time a second city is real, the question will be whether the Austin month was a prototype of the service or a prototype of the excuse. I lean toward wanting the former, and I do not think the evidence is there yet. Smooth drives and a rising permit count are necessary. They are not the whole fare.
Expansion test: density + curb accuracy + door reliability + responder control + audit answersThe Investor Version Of The Same Story
For anyone holding the stock, the Cybercab is a duration trade wearing a vehicle. The car business has to keep funding the wait. Chinese price pressure does not pause while Austin debugs a latch. European and Asian export fights do not pause either. A network that is very widespread by the end of 2026 was the spoken ambition. The visible footprint is one city, 169 authorized pods, a parallel Model Y robotaxi group, and a federal question list with an extension on it.
That can still bend toward the ambition. Permit counts that nearly quadruple in a month are not the behavior of a program stuck in a garage. Mixed reviews that praise the drive and scold the curb are not the behavior of a program in denial, at least not if the scolding gets worked. The risk is narrative substitution: letting the volume forecast stand in for the ride. Forecasts are cheap. Curbs are not.
A rival doing half a million paid rides a week is the inconvenient neighbor. You do not have to crown that neighbor to admit the distance. Distance is closable. It is not closable by a downtown photo and a Davos sentence. It is closable by cars, cities, and months in which nothing interesting happens. The first month in Austin was interesting. The next ones should be less so.
Leaving The Laboratory
So the hard part is not the unveiling. The unveiling already happened. The hard part is taking a two-seat pod with no wheel, a door that needs space, and a pickup habit that is still learning the curb, and making it feel ordinary somewhere that did not volunteer to be the lab. Texas records say the fleet grew. Rider posts say the experience is unfinished. Responders say they want a way to move the car when the script stops. Surveys say half the country is not ready to skip the pedal. An audit is open, with more time granted to answer it.
Put those together and the expansion case is neither a joke nor a done deal. It is a narrow road. More authorized cars help. Cleaner drop-offs help more. A second city helps only if it inherits the fixes, not just the paint. I would rather see a boring November in Austin than a loud announcement about Florida. Boring is how ride services survive. Loud is how pilots stay pilots.
If the Cybercab is going to be the volume vehicle the lineup is supposedly waiting on, the street has to start agreeing with the factory plan. Agreement looks like short waits, doors that mind their business, trunks that close, and a month that first responders do not have to narrate. Until that shows up outside one capital city, the quadrupling from 45 to 169 is a good opening chapter. It is not the book.
]]>