
Have you ever watched a young horse walk into a ring and wondered how a single animal can pull in millions before it has even raced? I have. And this season that question stopped feeling theoretical. The world’s largest thoroughbred yearling auction just closed at a record $536.7 million, nudged past last year’s high by a few million dollars that, in this world, count as a statement rather than a rounding error.
Why The Racehorse Market Just Hit Another Peak
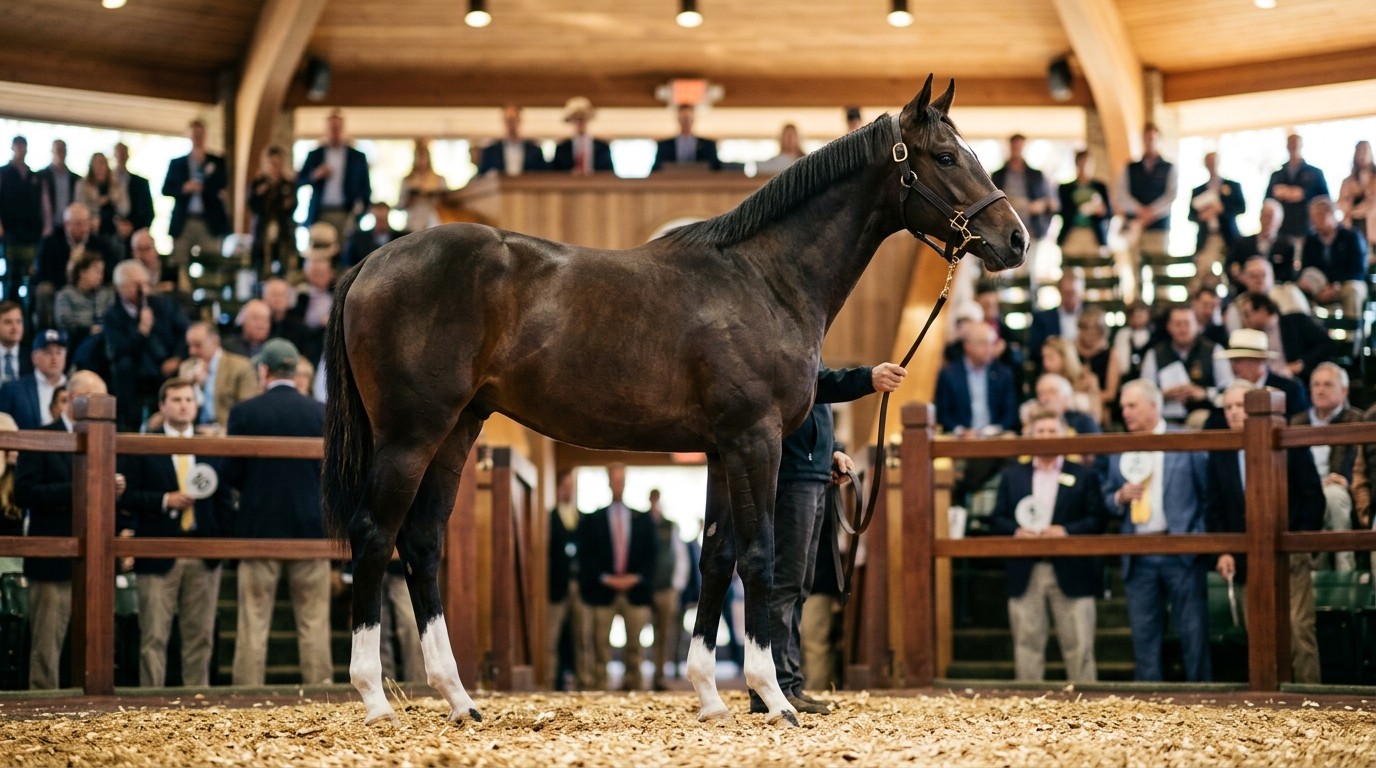
Two weeks of bidding ended in late September with seventy yearlings selling for at least a million dollars. That is up from fifty-six the year before, a mark that had already smashed a nineteen-year ceiling. The average price climbed nearly seven percent to $187,933. The top lot, a dark bay colt with white socks, went for $3.7 million.
On paper this looks like another luxury boom. In practice it is messier and more interesting. Buyers arrived with stock-market gains still warm in their accounts, private-equity exits still fresh, and a tax rule that lets a business write off an entire racehorse purchase in year one. That combination is doing more work than romance about the winner’s circle.
I’ve found that people outside the sport assume horse buying is either vanity or gambling. Sometimes it is both. Often it is also a structured asset play dressed in a leather halter. That is the part worth unpacking.
The Tax Rule That Changed The Math
Last year’s tax legislation permanently restored 100% bonus depreciation. Most conversations about that incentive still orbit warehouses, equipment, and private jets. Racehorses qualify too. If the animal is treated as qualified business property, the owner can deduct the full purchase price in the first year of ownership.
That is not a loophole whispered in a barn aisle. It is a design feature of current tax policy. Related assets can be written off as well: tack, barns, vehicles used in the operation. Some owners form an LLC so the activity sits cleanly inside a business wrapper. An accountant who also breeds horses put it bluntly. If you are already successful and you want a deduction plus a little public glow, the horse business can look like a pretty good place to park capital.
If you happen to be successful and you wanted something that gives you a tax deduction and gives you publicity, the horse business is a pretty damn good investment to make.
– Horse breeder and accountant
Last year’s September sale jumped about twenty-four percent after the bill became law. This year’s result did not repeat that spike. It did lock in the new floor. Markets that reprice once rarely drift back to the old range without a shock.
Is every buyer running a spreadsheet at ringside? Of course not. Some just want the photograph. Still, when the write-off is immediate, the net cost of a six-figure or seven-figure yearling drops in a way that stock certificates never quite match. That changes who raises a paddle.
Stock Gains And The Price Of Admission
Owning a professional sports franchise remains out of reach for most entrepreneurs, even wealthy ones. A racehorse is not cheap. Compared with a team, it is almost approachable. That gap matters when equity markets have minted new fortunes and private sales have cashed out founders who now want a visible asset with a story.
Perhaps the most interesting aspect is how quickly that money found a ritual. Auction week is social as much as financial. You see people who sold a company last winter standing next to families that have bought yearlings for decades. The new money does not always know a cannon bone from a sesamoid. It knows a deductible asset when it sees one.
Higher purses in several racing jurisdictions help the story. A horse that can earn more on the track is easier to justify after the tax benefit is taken. Nobody should confuse that with a guaranteed return. Plenty of expensive yearlings never win a stakes race. The industry has always sold hope with conformation. What changed is the after-tax cost of that hope.
The Colt That Set The Tone
The sale-topper was a dark bay colt sired by Into Mischief, a stallion whose sons have already won three Kentucky Derbies. A group that included paper executive Peter Brant signed the ticket at $3.7 million. Bloodlines like that do not need a sales pitch. Buyers pay for probability, or at least the feeling of it.
White socks photograph well. That sounds shallow until you remember this market also sells narrative. A horse that looks the part on the cover of a catalog is easier to syndicate later. Looks are not performance. They are marketing. In a record sale, marketing still works.
I keep coming back to that number because it sits in a strange middle ground. It is not the all-time individual record for a yearling. It is high enough to dominate headlines and low enough, relatively speaking, that several tables in the pavilion could imagine competing for the next one. That is how a market stays liquid at the top.
Did Geopolitics Keep Buyers Home?
Before the sale, people in Kentucky quietly wondered whether conflict in the Gulf would thin the Middle Eastern benches. Ruling families from Dubai and Qatar have become fixtures at the expensive end of the catalog. The worry was practical, not theatrical. Long-haul travel, optics, timing.
It did not show up in the room the way some feared. Auction leadership said they always hold their breath until those buyers appear. This time, they were not aware of anyone who stayed away because of the conflict. About a quarter of the yearlings went to international accounts, including buyers tied to Qatar, Saudi Arabia, the United Arab Emirates, and Libya. Country-by-country splits were not published. The presence was visible enough.
We always kind of hold our breath until they get here. But there wasn’t anybody that we’re aware of that didn’t come because of the conflict.
– Auction house chief executive
That detail matters more than a single quote. Global luxury markets often wobble when headlines turn harsh. This one absorbed the noise. Demand at the top is sticky when the asset is scarce and the tax treatment is friendly.
Partnerships Did Not Dilute The Sale
The biggest buyer was not a lone owner with a famous silks pattern. It was a newly assembled group of four racing partnerships and owners that spent $16.2 million on twenty horses. A few years ago, the fear was that partnerships would fragment demand and pull prices down. The opposite happened.
People who buy together tend to stretch. They diversify risk across more horses. They get more shots at a stakes winner. They also like the company. Camaraderie is not a line item on a depreciation schedule, yet it keeps paddles in the air.
- Shared capital lets a buyer enter a higher price band without carrying the whole ticket.
- Multiple horses raise the odds that one animal pays for the rest.
- Group decisions can be slower, but they often support stronger total spend.
- Social proof inside the partnership reduces the sting of a horse that never trains on.
In my experience, markets that look clubby from the outside are often just efficient at pooling taste and cash. Racing has always had syndicates. What is new is how openly they compete with traditional solo buyers at the very top of a catalog this large.
What The Numbers Actually Show
| Metric | This Year | Context |
| Gross sales | $536.7 million | New record, about $5 million above last year |
| Million-dollar yearlings | 70 | Up from 56, after a 19-year record fell last season |
| Average price | $187,933 | Nearly 7% higher |
| Sale topper | $3.7 million | Into Mischief colt bought by an investor group |
| Largest buyer group | $16.2 million | 20 horses across four partnerships and owners |
| International share | About 25% | Includes Gulf and North African buyers |
A five-million-dollar lift on a half-billion-dollar gross is not a mania. It is a confirmation. The market digested a huge jump last year and then added a little more. That pattern usually signals acceptance, not a blow-off top. Of course, acceptance can still be expensive if purses flatten or if tax rules change again.
Bonus Depreciation In Plain Language
Bonus depreciation lets a business deduct the full cost of eligible property immediately rather than stretching the write-off across several years. For a racehorse placed in service as a business asset, that can mean the entire hammer price hits the return in year one, subject to the usual rules, basis, and activity tests.
This is where hobby-loss rules still matter. The Internal Revenue Service has never been sentimental about paddocks. Owners who treat the stable like a weekend toy can lose the deduction. Owners who run it like a business, keep books, show a profit motive, and document the operation stand on firmer ground. That distinction is not glamorous. It is the difference between a tax strategy and a very costly pastime.
Related property can sweeten the package. A barn is not a horse, yet it can be depreciable. Equipment used in training can be depreciable. Forming an entity can separate personal cash from operating cash. None of that turns a slow horse into a fast one. It changes the after-tax shape of the bet.
Simple buyer logic this season:
  Immediate write-off on the horse
  Possible write-offs on barns and gear
  Higher purses in some jurisdictions
  Lower relative ticket versus buying a sports team
  Social return that public markets do not offer
Who This Market Is Really Serving
High-net-worth households have more ways than ever to feel rich. Art, watches, vineyards, team slivers, private aviation. A yearling sits in an odd pocket of that menu. It is living inventory. It can become worthless in a morning workout. It can also become a stallion prospect worth tens of millions. Few alternative assets have that barbell so baked in.
That barbell attracts a certain temperament. You need enough wealth that a total loss does not change your life. You also need enough appetite that a long shot still feels worth the dinner conversation. Tax policy did not create that temperament. It subsidized it.
Middle Eastern buying remains a structural feature, not a cameo. Those accounts have depth, patience, and global racing programs that can place a horse where the purse makes sense. Domestic partnerships now sit beside them instead of merely watching. The catalog has enough depth that both groups can leave with horses and still call the week a success.
Risks People Soft-Pedal At The Bar
Let’s not dress this up as a bond substitute. Injury risk is real. Training bills arrive whether the horse is sound or not. Insurance helps, then has limits. Liquidity is poor compared with listed shares. You cannot tap an app and sell a two-year-old at 2 a.m.
Valuation is another quiet problem. Pedigree and walk and veterinary reports are information, not prices discovered by millions of traders. Two sophisticated groups can look at the same colt and disagree by seven figures. That is not a market failure. It is a thin market doing what thin markets do.
- Confirm the activity can stand as a business, not a hobby, before counting on the write-off.
- Budget for keep, vets, transport, and the seasons when the horse does not run.
- Treat partnerships as governance problems as much as capital solutions.
- Do not let last year’s twenty-four percent jump become your baseline expectation.
- Remember that publicity cuts both ways when a high-priced horse never makes the gate.
I’ve sat through enough victory-lane speeches to know the photographs age better than the P&L. That does not make the asset class foolish. It makes honesty useful.
Why Purses And Policy Move Together
Higher purses do not appear by accident. Racing jurisdictions compete for horses, handle, and prestige. When purses rise, the expected earnings of a useful runner rise with them. That supports residual values and makes the first-year deduction feel less like the whole story.
Policy and purses are not the same lever. One is federal. The other is local, commercial, sometimes political. Together they create a narrative that is easy to sell in a pavilion: you can deduct the horse now and maybe earn more later. Easy narratives move rooms.
If purses stalled while depreciation stayed generous, you would still see tax-motivated bidding. You would see fewer dreamers. The current mix has both. That is why the average can rise even when some mid-catalog horses look fully priced.
The Social Layer Nobody Puts In A Model
Walk the grounds during a major yearling sale and you notice how much of the week is not bidding. It is breakfast, inspection, argument, rumor. People who made money in paper or software suddenly share a language with people who have walked yearlings since childhood. That translation is clumsy. It is also part of the product.
Partnerships intensify the social layer. Buying with friends is a phrase that sounds soft until you watch a group celebrate a knock-down they could not have reached alone. Wealth managers talk about alternatives. Buyers talk about the walk over and the way a colt used his hind end. Both conversations are real. Only one of them photographs well.
Is that inefficient? Sure. So is a lot of collecting. The difference is the living animal and the racing calendar, which keep forcing a result. Art can sit on a wall for twenty years. A racehorse asks a question every season.
What Record Gross Does Not Guarantee
A record sale does not mean every consignor won. Averages hide the horses that RNA’d or sold light. It does not mean next year’s crop will clear the same bar. Sire fashion moves. Veterinary findings cluster. Currency swings can change what an overseas bidder is willing to pay in dollars.
It also does not mean tax policy is frozen. Permanent is a legislative word, not a cosmic one. Anyone building a multiyear breeding plan on one deduction should keep a second plan in the drawer. Markets that lean on a single incentive look brilliant until the incentive shifts.
Still, dismissing the result as a one-off would be lazy. Last year reset the scale. This year defended it. International buyers showed up. Partnerships spent more, not less. The top of the catalog found aggressive money without needing a crisis discount.
How A Serious Buyer Might Think About Entry
If someone asked me how to approach this market without pretending I train horses for a living, I would start with purpose. Are you buying a deduction with a hobby attached, or a racing operation that happens to be tax-efficient? Those paths look similar at the fall of the hammer. They diverge by spring.
Next comes structure. Entity choice, management agreements, insurance, and a trainer who will tell you the truth when the x-rays are ugly. Then comes price discipline. Record averages seduce people into thinking the middle of the market is safe. The middle is where keep costs quietly eat the thesis.
Bloodstock agents earn their fees when they talk a client out of a pretty walk. That sentence will annoy some agents and delight others. Either way, independent eyes matter more when the room is hot.
A Longer View Of Wealth And Living Assets
Every few years a corner of the luxury economy discovers an asset that feels productive. Vineyards did it. Sports teams did it. Now yearlings are doing it again, with better tax optics than many collectibles. Productive is a stretch when most horses lose money. Relative to a watch, though, a horse at least has a job description.
That is why this story sits at the intersection of tax efficiency and smart-money behavior. The same households that optimized carried interest, opportunity zones, and private credit are now optimizing a barn. Some of them will look foolish. Some will breed the next fashionable stallion and look prophetic. Most will land in between, with a deduction, a few photos, and a clearer sense of how expensive fun can be.
I do not think the record is an accident. I also do not think it is a perpetual motion machine. Wealth created in public markets is searching for identity as much as yield. A dark bay colt with white socks gives both, at least for an evening. The morning after is when the business either begins or pretends to.
The Quiet Lesson From A Loud Sale
When a market breaks a record two years running, commentators reach for superlatives. The more useful move is smaller. Notice who showed up. Notice what they were allowed to deduct. Notice that fear about missing Gulf buyers did not rewrite the ledger. Notice that partnerships spent like competitors, not like committees afraid of their own shadows.
Those are the tells. They suggest the racehorse market is not merely riding a fashion cycle. It is absorbing a tax regime and a wealth cycle at the same time. That can last longer than a hot sire. It can also reverse if either pillar cracks.
Until then, the pavilion will keep filling. Someone will fall in love with a walk. Someone else will fall in love with a first-year write-off. On a good night, those two people bid against each other, and the average ticks up again. That is how a living asset market looks when money is plentiful and the code is kind.
And if you are still wondering whether a horse can be an investment, the honest answer is the unglamorous one. It can be a business. It can be a deduction. It can be a very public way to spend money you already made. Calling it only one of those things is how people get surprised when the invoice for hay arrives in January.