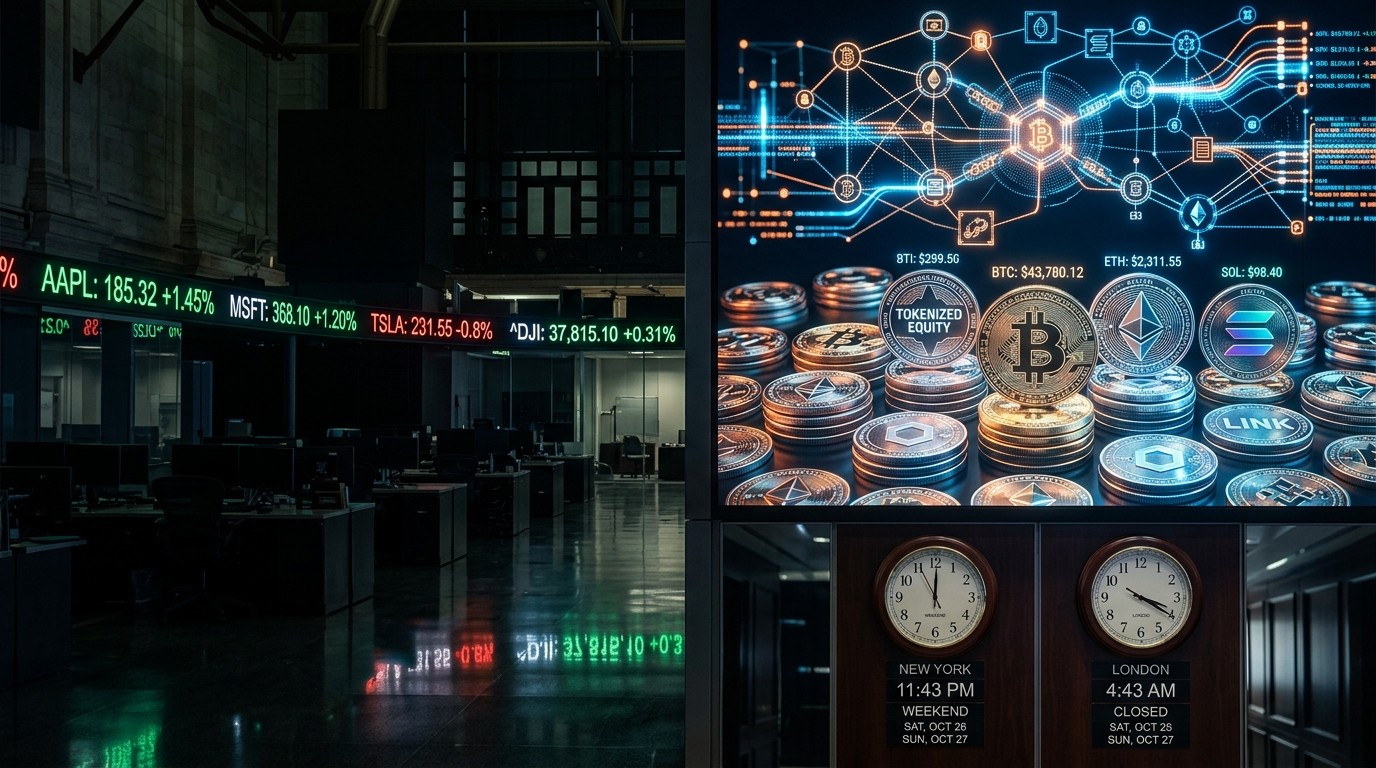

Have you ever watched a price keep moving on a Sunday night and wondered who, exactly, is setting that number? I had that thought again this week. Tokenized versions of U.S. stocks can now sit in permissioned onchain pools while the New York floor is dark, the tape is quiet, and the usual reference market is not publishing a live executable quote. That is not a small inconvenience. It is the kind of mismatch that looks harmless until a large order hits a thin pool and nobody can complete the other side of the trade in the real share.
Why Around The Clock Tokens Still Need A Daytime Market
The new temporary relief lets qualifying venues bring buyers and sellers together through permissioned automated market maker pools for tokenized National Market System stocks. On paper, that sounds like progress. Fully backed tokens. Same rights as the conventional share, at least when the product qualifies. Public and auditable smart contracts on permissionless chains. Coordinated halts when the primary exchange stops the underlying name.
Then you look at the calendar. The New York and Nasdaq cash session runs about 32.5 hours a week. A blockchain week has 168 hours. Ordinary nights, weekends, and holidays are treated differently from an official halt. Token venues can keep running when the deepest U.S. equity market is not producing a live price. I find that detail more important than the usual chatter about fragmentation.
An AMM only prices off its own pool. Arbitrage keeps that honest, but only while the reference market is open.
That line from the oracle side of the industry is blunt, and I think it is fair. An automated market maker does not magically know what Apple or Nvidia “should” cost at 2 a.m. on a Saturday. It knows the ratio of assets sitting in its own pool. While the cash market is open, professional traders can buy the cheap side and sell the rich side. When that cash market is closed, the correction mechanism gets weaker. Sometimes it almost disappears.
What An AMM Actually Sees After The Bell
During regular U.S. hours, a market maker can compare the onchain token with the underlying share and lean on both books. Overnight, the deepest venue is not printing a current executable price. The AMM still reacts to whatever orders arrive in a much smaller pool. A sizable trade can shove the quoted price even when nobody can immediately buy or sell the real stock to finish the arbitrage.
People like to say volume will fix this. I am not convinced. Higher order size can raise the price impact of each AMM trade. The number of hours without a live primary-market reference does not shrink just because more tokens change hands. If anything, the problem gets louder as activity grows.
Think of it like a night market next to a locked warehouse. You can still haggle. You can still move inventory among the people who showed up. You cannot easily check the warehouse ledger until Monday morning. Prices can be honest among the night crowd and still drift from the asset those tokens claim to represent.
Hours Without A Live Reference Price
The calendar math is simple and a little uncomfortable.
| Venue | Typical live session | Share of the week |
| Primary U.S. cash equity market | About 32.5 hours | Roughly one fifth |
| Onchain token pool | Up to 168 hours | The full week |
| Official halt window | Follows the listed stock | Must stop onchain too |
| Ordinary close, weekend, holiday | No live cash print | Tokens may still trade |
A halt is treated as a hard stop. A regular close is not. That distinction is legally tidy and operationally messy. Investors who treat a token quote as “the stock price” after hours are using a different instrument with a different information set. Sometimes the gap is tiny. Sometimes a weekend headline, a thin pool, and one impatient order are enough to make it ugly.
Two Token Classes For The Same Company
The pricing clock is only half the story. The exemption covers tokenized NMS stocks that give holders rights and privileges matching the traditional share. Synthetic or wrapped products already circulating through offshore structures sit outside that box. So you do not just get tokenized versus traditional. You can get two tokenized products tied to the same name, priced differently, governed differently, and offering different rights.
In my view, that split will confuse more people than the technology itself. One product may be a fully backed ownership token under the new framework. Another may be economic exposure through a special purpose vehicle, a trust, or a wrapper that never puts the wallet on the issuer’s register. Both can trade. Both can look like “the stock” in an app. They are not the same claim.
- Conventional listed share with direct register rights when held in the usual way
- Qualifying fully backed token meant to mirror those rights under the exemption
- Synthetic or beneficial-interest token that may block voting and redemption until checks clear
Some existing products represent beneficial interests in shares held through an offshore company and a regulated broker. Legal title often stays with a trust. A wallet holder who has not finished identity, location, sanctions, and anti-money-laundering review can transfer the token and still fail to redeem or vote. That is not a rounding error. That is a different bundle of rights wearing the same ticker costume.
Issuer Notice, Objections, And The Products Left Out
For tokens created by an unaffiliated third party, a venue must give the underlying company written notice and a chance to object before trading starts. That clause exists because public companies have already bristled at seeing their names attached to tokens they did not approve. One entertainment issuer recently objected after learning a synthetic product had been created without the firm’s blessing. Holders of that style of token often receive exposure without ownership, voting power, or standard shareholder protections.
Here is the catch. The products that sparked that fight are synthetic. They are not governed by the new exemption. Notice and objection rights therefore do not automatically clean up the market people already use. The rule addresses one governance dispute and leaves another product class on a different track.
The products causing that fight are synthetic and will not even be governed by today’s framework.
I keep coming back to that sentence. Policy can look complete while the loudest consumer products sit outside the perimeter. Investors will still compare prices across all three versions of “the same” name. Issuers will still see their brands on screens they do not control. Regulators will still be asked why two tokens diverged over a long weekend.
What The Temporary Relief Actually Requires
The order is not a free-for-all. Qualifying tokens must provide equivalent rights and privileges. Venues face limits on symbols and volume. Smart contracts need to be public and auditable. Onchain activity must stop when the primary exchange halts the stock. Liquidity providers using their own capital in approved AMM pools received separate conditional relief from dealer registration. Disclosures on operations, trading, and affiliated activity are part of the bargain.
The clock is also finite. The relief lasts five years after publication. Comments were requested on possible changes and later action. That is a trial period with an expiration date, not a permanent rewrite of equity market structure. Anyone building a business on the assumption that weekend token prices will always be treated as official close cousins of the listed print should read that sunset language twice.
- Confirm the token is a qualifying ownership product, not a synthetic wrapper.
- Check whether the venue must pause when the listed stock is halted.
- Ask how the pool behaves when the cash market is merely closed.
- Review redemption, voting, and register rights before treating the token as the share.
- Watch for issuer notice and any public objection tied to that name.
Price Risk Scales With Data, Consent Risk Scales With Governance
Other tokenized markets already ran into a similar mismatch. Continuous rails meet institutions that still keep office hours. A weekend cross-border tokenized deposit can move in minutes. That does not automatically mean every underlying obligation reached final legal settlement at the same instant. Wholesale payment systems do not always run through Saturday and Sunday. Banks then lean on prefunded balances and extra buffers until the official pipes reopen.
Stock tokens face a data constraint more than that exact settlement constraint. Keeping a share-linked instrument aligned requires reliable prices when the underlying market is open and clear rules when it is not. Price risk grows with the quality of the feed and the honesty of the arbitrage path. Consent risk grows with who was asked, who can object, and who actually sits on the register.
Neither problem is solved by this exemption alone, and both compound as volume grows.
That pairing is the part I would tape to a monitor. Better oracles help during the session. They do not invent a cash print that does not exist at 11 p.m. Better notices help issuers. They do not convert a synthetic token into a fully backed share. Volume without those two rails is not maturity. It is a larger surface for drift.
When Yield Vaults Meet Weekend Prices
Product design is getting more layered, not simpler. Some platforms now drop tokenized index and single-name products into vaults, use them as collateral for stablecoin loans, and route proceeds through cross-chain strategies. Early rollouts have advertised modest estimated net yields. The disclosures are less modest. Liquidation, bad debt, smart-contract bugs, bridge risk, and liquidity gaps all sit on the page. Withdrawals can carry a multi-day wait and stretch longer in stress.
Now add an after-hours AMM quote that may have wandered from Friday’s cash close. Collateral values, loan health, and liquidation triggers start depending on a price that is not being pinned by the primary equity market. Perhaps the most interesting aspect is how ordinary that stack will look to a user who only sees a ticker and an APY. The stack is not ordinary. It is several risk layers sharing one familiar name.
How Traders Can Think About The Gap Without Pretending It Is Gone
I do not think the answer is to ban night trading or to pretend the cash open is sacred in every context. Continuous markets have real uses: hedging, transferring exposure across time zones, letting smaller tickets clear without waiting for Monday. The answer is to stop treating every token print as a substitute for the listed last sale.
A practical checklist looks less glamorous than a launch thread and more useful.
- Separate the qualifying ownership token from any synthetic twin before comparing prices.
- Treat weekend AMM moves as pool prices first, stock prices second.
- Assume arbitrage is slower when the cash book is closed.
- Size orders for impact, because thin night liquidity is not a rumor.
- Read the redemption and voting fine print before calling the token “your shares.”
If you are allocating client money, write the policy down. If the mandate says “U.S. large-cap equity,” decide whether a Sunday token print counts. If it does not, say so. Ambiguity is how two honest people end up arguing about a 4 percent gap that only existed because one market was asleep.
Why This Will Get Harder As The Market Gets Bigger
Growth does not shrink the closed hours of the listed tape. It increases the dollars that can hit a pool while that tape is dark. Price impact per trade can rise with size. Headline risk does not wait for the opening bell. A CEO comment, a geopolitical scare, or a surprise filing can land on a Saturday. Token pools will reprice. The cash market will wait. On Monday those two stories have to meet again.
That meeting can be orderly. It can also look like a gap fill that shocks anyone who marked a portfolio to the Saturday quote. I have found that people underestimate how emotional that Monday reopen can feel when the token already “voted” on the news two days earlier.
There is also a fairness angle. Retail users often see one number. Professionals see a structure: pool inventory, oracle delay, halt rules, redemption gates, and issuer consent. If the public number is the pool and the professional number is the cash print plus basis, the same product is being described in two dialects. That is how trust leaks, slowly, then all at once.
What “Same Rights” Has To Mean In Practice
Equivalent rights is easy to print in an order and harder to live with in a wallet. Voting calendars, corporate actions, dividends, proxy materials, and transfer restrictions all have to map onto a token without turning into a scavenger hunt. If legal title sits with a trust, the wallet is not the shareholder of record. If redemption needs compliance approval, transferability is not the same thing as economic finality.
I would rather see boring operational detail than another sleek wrapper. Who receives the dividend? Who votes? How long does redemption take when markets are calm? How long when they are not? What happens if the issuer objects after a product is already circulating in a different structure? Those questions are not anti-innovation. They are how you keep a token from becoming a slogan.
A Straight Look At Incentives
Venues want flow. Token issuers want distribution. Oracle firms want to be the reference when the cash market cannot be. Issuers of the real stock want control over their cap table and their brand. Traders want a number they can hedge. Each incentive is rational. Together they produce a market that can look unified on a dashboard and fragmented in law.
Permissioned AMMs are a compromise. They try to keep automated pricing while restricting who can sit in the pool. That may reduce some abuse. It does not create a Sunday cash print. Conditional dealer relief may bring more capital into those pools. More capital can deepen a book and still leave the reference-market hole untouched for 135-plus hours a week.
The Five Year Window Is The Real Experiment
Five years is long enough for products to become habitual and short enough for the terms to change. Habits form around screens, not statutes. If users mark weekend token prices in their heads as “the market,” later tightening will feel like a taking even if the original order always said temporary. That is why communication matters as much as code.
Comments requested by the agency are not decorative. This is the period when practitioners should describe actual basis moves, actual halt coordination failures, and actual investor confusion between synthetic and ownership tokens. Vague cheerleading will not age well. Specific operational notes might.
A Clearer Way To Talk About These Products
Language is part of the risk. Calling every onchain claim a “stock token” flattens differences that lawyers, issuers, and liquidators will not flatten later. I prefer three plain labels in any explainer, even if they are less catchy.
- Listed share: the conventional NMS equity in the primary market
- Ownership token: a qualifying fully backed token meant to carry equivalent rights
- Exposure token: a synthetic or beneficial-interest product that may not put you on the register
Once those labels stick, the after-hours debate gets easier. Of course an exposure token can trade on Sunday. The question is whether its price is being sold as a substitute last sale. Of course an ownership token can sit in an AMM. The question is whether arbitrage still has a live cash anchor. Different questions. Different answers. Same ticker on a phone is not a reason to merge them.
What I Watch Next
First, basis between qualifying tokens and the listed print at the Monday open after a noisy weekend. Second, whether issuer objections actually stop unaffiliated listings or merely create a paper trail. Third, whether synthetic products keep growing beside the exempted class and pull price discovery away from the product that carries real rights. Fourth, how vaults and leveraged wrappers behave when collateral marks come from a closed-market AMM.
None of that requires hostility to tokenization. I like the idea of faster settlement rails and clearer transfer records. I do not like the habit of skipping the boring hours problem because the interface looks modern. Markets have always needed a reference. Blockchains did not repeal that need. They made the hours without a reference more visible.
So where does that leave a careful reader? Tokenized U.S. stocks can now live in permissioned automated pools under a temporary exemption that insists on equivalent rights, issuer notice, volume limits, and coordinated halts. That is a real shift. It is not a 24/7 replica of the listed tape. The cash market still sleeps most of the week. AMMs still price their own inventory. Synthetic twins still sit outside the new fence. Yield wrappers still stack extra risks on top of a quote that may have wandered after Friday’s close.
If you remember one ratio, remember 32.5 against 168. If you remember one split, remember ownership tokens versus exposure tokens. If you remember one warning, remember that volume does not shorten the night. The experiment is underway. The prices you see when the building is empty are still telling you something. You just have to ask whether they are telling you the stock, the pool, or both at once.