
Have you ever watched a long-running game of cat and mouse play out on the open ocean and wondered how much longer one side can keep slipping through the net? That is exactly the feeling I get when looking at the latest round of pressure aimed at the vessels still moving Iranian oil toward Asian buyers. The remaining pieces of what many call the shadow fleet just absorbed another heavy set of designations, and the message is clear: the effort to dry up that revenue stream is not slowing down.
Why These New Measures Matter Right Now
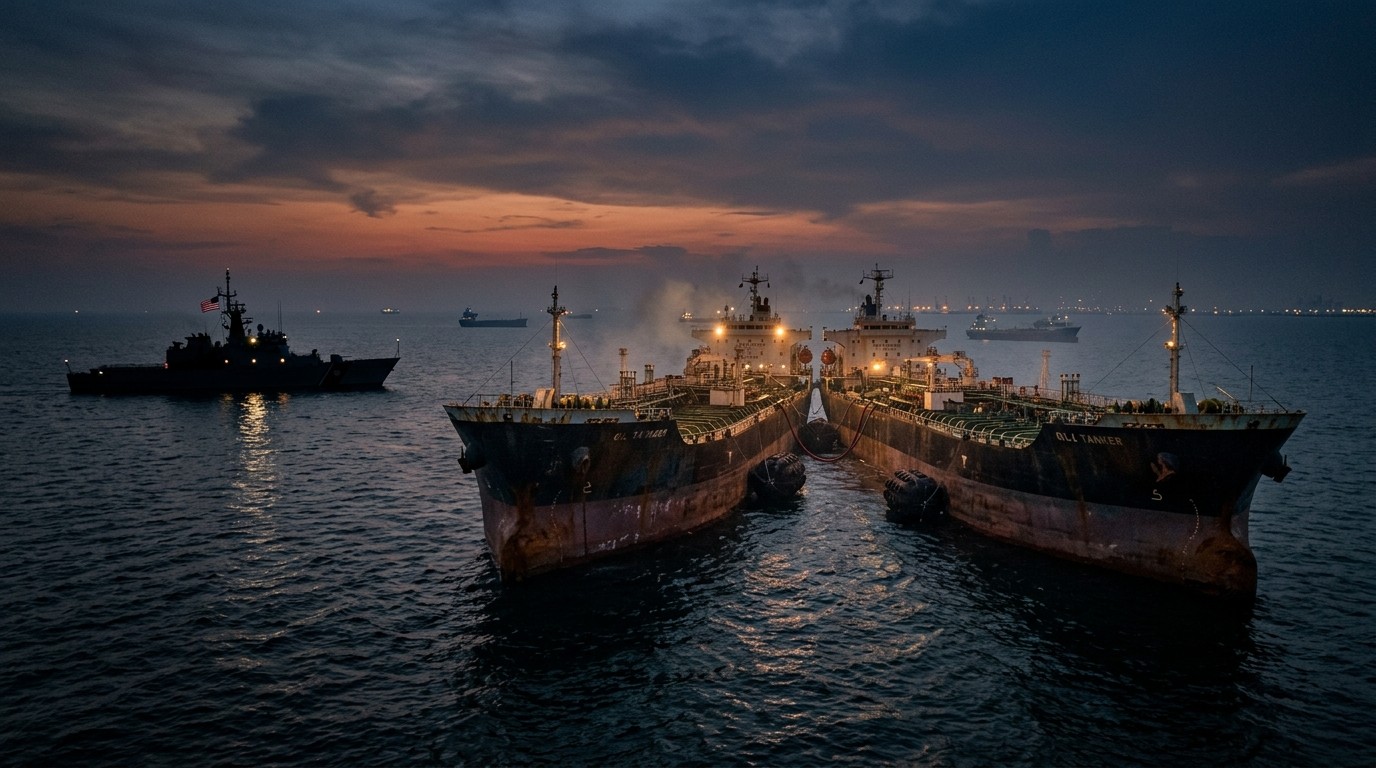
The latest actions focus on a group of aging tankers and the people and companies that keep them operating. These ships have specialized in the quieter work of moving crude, petroleum products and petrochemicals while trying to stay out of the spotlight. Many of them rely on ship-to-ship transfers and other methods that make tracking harder. By naming the vessels and their owners, authorities aim to make it far more difficult for them to find insurance, ports or buyers willing to take the risk.
I find it striking how persistent this network has been. Even after years of restrictions, a portion of the fleet has continued to function. The current push is being described as an attempt to neutralize the vast majority of what was left. Whether that claim holds up over the coming months will depend on how thoroughly the designations stick and how creative the remaining operators become.
The Specific Targets Named This Week
Several vessels received particular attention. One was linked to moving more than three million barrels of Iranian naphtha since last year. Two others were tied to sizable volumes of ethylene and crude. Additional ships were connected to bitumen and asphalt movements. Alongside the tankers, a number of individuals and companies also appeared on the list, including nationals from different countries who allegedly helped keep the operations running.
In my view, the breadth of the designations is what stands out. It is not only the ships themselves but the support network around them. That approach raises the cost of doing business for anyone still willing to participate. Of course, history shows that determined actors often find new routes or new flags. Still, each new layer of pressure adds friction.
No enabler of sanctions evasion is safe from the full force of these authorities.
That kind of language signals continued determination. Officials have also pointed to the broader goal of reducing the funds available for regional activities that many governments view as destabilizing. Whether the economic squeeze produces the desired political outcome remains an open question, and one that has been asked for a long time.
Oil Still Sitting Outside Immediate Reach
Even as the designations land, roughly twenty million barrels of Iranian crude are estimated to sit on vessels far from the main area of naval focus. Those cargoes are positioned near Southeast Asian ports, well beyond the immediate reach of any blockade centered on the Persian Gulf. That floating inventory means some volume can still reach markets for a while longer, even if new loadings become harder.
This is the part that keeps the situation from feeling fully resolved. You can restrict ports and pressure shipping companies, yet cargo already at sea can continue its journey. Buyers and middlemen then decide how much risk they are willing to accept. Some will step back. Others may calculate that the discount is worth the potential complications.
I have watched similar dynamics play out in other restricted energy trades over the years. The initial impact is often visible in reduced loadings and higher freight rates for remaining vessels. Later, new patterns emerge. Whether that happens again here is something market participants are watching closely.
Claims About Zero Oil On The Water
Recent comments from senior officials have been notably assertive. One highlighted that for the first time in a long stretch, Iran would have no oil on the water in a given week and therefore no revenue from that channel. The comparison drawn was between substantial volumes previously moving and a current figure approaching zero through the main strait.
Those statements are bold. They reflect the intensity of the current effort. At the same time, the existence of the floating barrels already mentioned introduces a note of caution. Revenue may slow sharply, yet it may not stop completely overnight. The difference between a sharp reduction and a total cutoff can matter a great deal to both the seller and the buyers who have relied on those barrels.
How The Shadow Fleet Operates In Practice
Understanding the mechanics helps explain why these designations keep coming. Many of the vessels involved are older. They often change names or flags. They conduct transfers at sea rather than docking in the most obvious ports. Tracking systems may be switched off for stretches of time. Insurance coverage can be opaque. All of these steps increase the difficulty of enforcement.
Yet each of those same steps also creates vulnerabilities. When authorities publicly identify a vessel, the risk of detention rises. When they name the owners, banks and insurers take notice. When they list the individuals involved, travel and financial access become more complicated. The cumulative effect is meant to make the whole enterprise less attractive.
- Older tankers with higher operational risk
- Frequent ship-to-ship transfers away from major ports
- Limited transparency around ownership and insurance
- Reliance on intermediaries willing to accept elevated risk
Those characteristics have allowed the trade to continue longer than many expected. They also explain why successive rounds of designations keep appearing. Closing one set of loopholes often reveals another.
Regional Reactions And Rising Tensions
While the economic pressure builds, military and security developments in the region have not stood still. Reports of attacks on vessels in the key waterway have increased in recent days. More than a dozen incidents have been noted over a short period. Those events push global oil prices higher and remind everyone how quickly the situation can escalate.
From my perspective, the combination of tighter sanctions and heightened maritime friction creates a more volatile backdrop. Energy markets dislike uncertainty. When both the supply of one producer and the safety of a critical transit route come into question at the same time, traders reprice risk. That is already visible in price movements.
Tehran has shown a capacity to absorb economic hardship in the past. Whether the current intensity of pressure changes that calculation is the central question many analysts are debating. Hardship alone does not always produce the policy shifts outsiders hope for. Sometimes it hardens positions instead.
What Buyers In Asia Are Facing
Asian refiners and traders have been important outlets for Iranian barrels for years. They have navigated previous rounds of restrictions by adjusting volumes, using intermediaries, or accepting higher logistical costs. The latest designations raise the stakes again. Companies that continue dealing with listed vessels or owners now face clearer secondary risk.
Some will step away entirely. Others may seek alternative suppliers. A few may try to maintain quiet access while calculating that enforcement will remain imperfect. The net result is likely a further reduction in the volumes that move freely and an increase in the discount required to move any remaining cargo.
I suspect we will see more public statements from major buyers emphasizing compliance. Behind the scenes, the scramble for replacement barrels could support prices for other producers. That shift is already part of the broader market conversation.
Broader Goals Behind The Pressure Campaign
Officials have framed the sanctions as part of a larger effort to limit resources available for activities that heighten regional tension. Oil sales have long been a major source of foreign currency. Reducing that flow is intended to constrain options. The language used has been direct: the aim is to starve the regime of funds used for certain purposes.
Whether economic tools alone can achieve complex political objectives is a debate that stretches far beyond this particular case. Sanctions have a mixed record. They can raise costs and limit capabilities. They can also produce adaptation, new alliances, and domestic narratives of resistance. Both outcomes have appeared in different situations over the years.
Perhaps the most interesting aspect is the intensity of the current claim that the shadow fleet has been largely neutralized. If that assessment proves accurate over the next several months, it would mark a meaningful shift in the long-running contest over Iranian oil exports. If new vessels or methods appear, the cycle will simply continue.
Looking At The Numbers That Still Matter
Even with the new designations, the twenty million barrels already at sea remain relevant. That volume is not enormous by global standards, yet it is large enough to influence near-term availability and pricing in certain markets. How quickly those cargoes are absorbed or whether they face additional obstacles will be one of the practical tests of the current measures.
Freight rates for the remaining unlisted or newly deployed vessels could rise. Insurance costs for anyone still involved will almost certainly increase. Banks that previously provided quiet services may become more cautious. Each of those frictions compounds the others.
| Element | Current Status | Potential Effect |
| Listed vessels | Newly designated | Higher operational risk |
| Floating inventory | Around 20 million barrels | Temporary supply cushion |
| New loadings | Under heavy pressure | Sharp reduction expected |
| Regional incidents | Elevated frequency | Price volatility support |
These moving pieces interact in ways that are hard to predict with precision. Markets will sort through the signals in real time. Traders who specialize in this corner of the energy world are already adjusting their models.
The Human And Corporate Side Of Compliance
Beyond the tankers themselves, the inclusion of individuals and companies matters. Five individuals of one nationality and one of another were named for alleged cooperation. Dozens of entities also appeared. For those people and firms, the practical consequences can be immediate: frozen assets, restricted banking, limited travel, and reputational damage that lingers.
I have spoken with compliance professionals over the years who describe the cascading effect of such listings. Once a name appears, counterparties begin internal reviews. Some relationships end almost overnight. Others become far more expensive to maintain. That private-sector reaction often amplifies the official action.
At the same time, determined networks have shown an ability to reconstitute under new corporate structures or through different jurisdictions. The cat-and-mouse dynamic does not end with one announcement. It simply moves to the next phase.
Market Implications Beyond The Immediate Region
Global oil markets are interconnected. When one source of supply faces tighter constraints, other producers can benefit from higher prices or increased market share. Refiners who previously ran Iranian grades may need to adjust configurations or seek alternative crudes. Shipping patterns shift. Freight markets for certain vessel classes tighten or loosen depending on demand.
Price volatility tends to rise during these periods. Speculators position themselves around headlines. Physical traders reassess risk premiums. The recent uptick in attacks on vessels in the key waterway has already fed into that process. Sanctions and security concerns are reinforcing each other for the moment.
In my experience, the first few weeks after a major designation package often produce the clearest market reaction. Later, adaptation sets in and the initial impact can fade unless enforcement remains consistent and visible. That consistency is the variable many will watch.
Will The Pressure Produce Strategic Change
This is the question that sits behind every technical discussion of vessels and barrels. Economic pressure is a tool. Its effectiveness depends on many factors: the resilience of the targeted economy, the availability of alternative partners, the domestic political calculations of leadership, and the broader regional security picture.
History offers examples in both directions. Some campaigns have contributed to policy adjustments. Others have coincided with prolonged stalemates. The current effort is being described by its architects as more comprehensive than previous ones. Time will tell whether that assessment is borne out by results on the ground and at sea.
Meanwhile, the day-to-day reality continues. Ships still need crews. Cargoes still need buyers. Insurance still needs underwriters. Each of those practical requirements creates potential points of leverage. The latest designations are designed to press on as many of those points as possible.
What Comes Next In This Long Contest
Further designations remain possible. Enforcement actions against specific vessels could increase. Diplomatic efforts to coordinate with other governments on port access and financial services will continue. On the other side, efforts to obscure ownership, switch flags, or develop new transfer locations will likely persist.
The floating inventory of roughly twenty million barrels will gradually clear or face its own complications. New loadings will be harder. Prices will respond to both the reduced Iranian volumes and any escalation in regional maritime incidents. Market participants will keep updating their assumptions as fresh information arrives.
I keep coming back to the image of those aging tankers operating at the edge of visibility. They represent both the ingenuity of those determined to keep oil moving and the limits of that ingenuity when faced with sustained, coordinated pressure. The latest round of measures tests those limits once again.
Whether this chapter ends with a lasting reduction in exports or simply another adaptation remains to be seen. What is already clear is that the cost of participation has risen again. For anyone still involved in moving those barrels, the calculations just became more complicated. For the broader energy market, the uncertainty adds another layer to an already complex picture.
The coming weeks will show how thoroughly the remaining network can be constrained and how the regional security situation evolves alongside the economic measures. Both tracks will influence prices, trade flows, and the strategic outlook for months ahead. Observers will be watching vessel movements, price spreads, and official statements with equal attention.
In the end, the story of the shadow fleet is a reminder that energy markets and geopolitics remain tightly linked. Restricting one source of supply does not simply remove barrels from the global balance. It redistributes risk, raises costs, and forces adjustments across a wide network of participants. The latest designations are the newest chapter in that ongoing process.
As more details emerge about compliance, enforcement, and any countermeasures, the picture will sharpen. For now, the message from the latest actions is unmistakable: the effort to limit the remaining capacity of this fleet is intensifying, and those who facilitate the trade face rising consequences. How durable that pressure proves will shape the next phase of this long-running contest over oil, revenue, and regional influence.