
Have you ever stared at a price chart and felt the story behind it was bigger than the number on the screen? That is where energy markets sit right now. A military command just said it had shepherded about a billion barrels of crude and more than two thousand commercial ships out of the Persian Gulf in a matter of months. Brent eased toward one hundred three dollars by week’s end. On paper that looks like relief. In practice it feels like a pause, not a resolution. I keep coming back to the same thought: escorts can move oil. They cannot erase a deficit that still runs in the millions of barrels a day.
Why A Billion Barrels Does Not Mean The Crisis Is Over
The headline is designed to calm nerves. A billion barrels is a round, almost theatrical figure. It tells households and traders that the world’s most watched chokepoint is not sealed shut. Fair enough. Ships are moving. Some of them are moving under the eye of warships. That is not nothing.
But volume escorted is not the same as volume restored. Before this round of hostilities, combined crude and product flows through the waterway and the usual bypass routes sat well above twenty million barrels a day. Recent weekly averages have hovered closer to twelve. Even a two-day burst toward fourteen million does not close an eight-million-barrel hole. Winter is coming in the Northern Hemisphere. Refineries do not run on press conferences.
I’ve found that markets forgive a scare faster than they forgive a shortage of middle distillates. Crude can look “fine” while diesel tells a harsher story. That split is the part too many casual observers skip.
What The Escort Claim Actually Covers
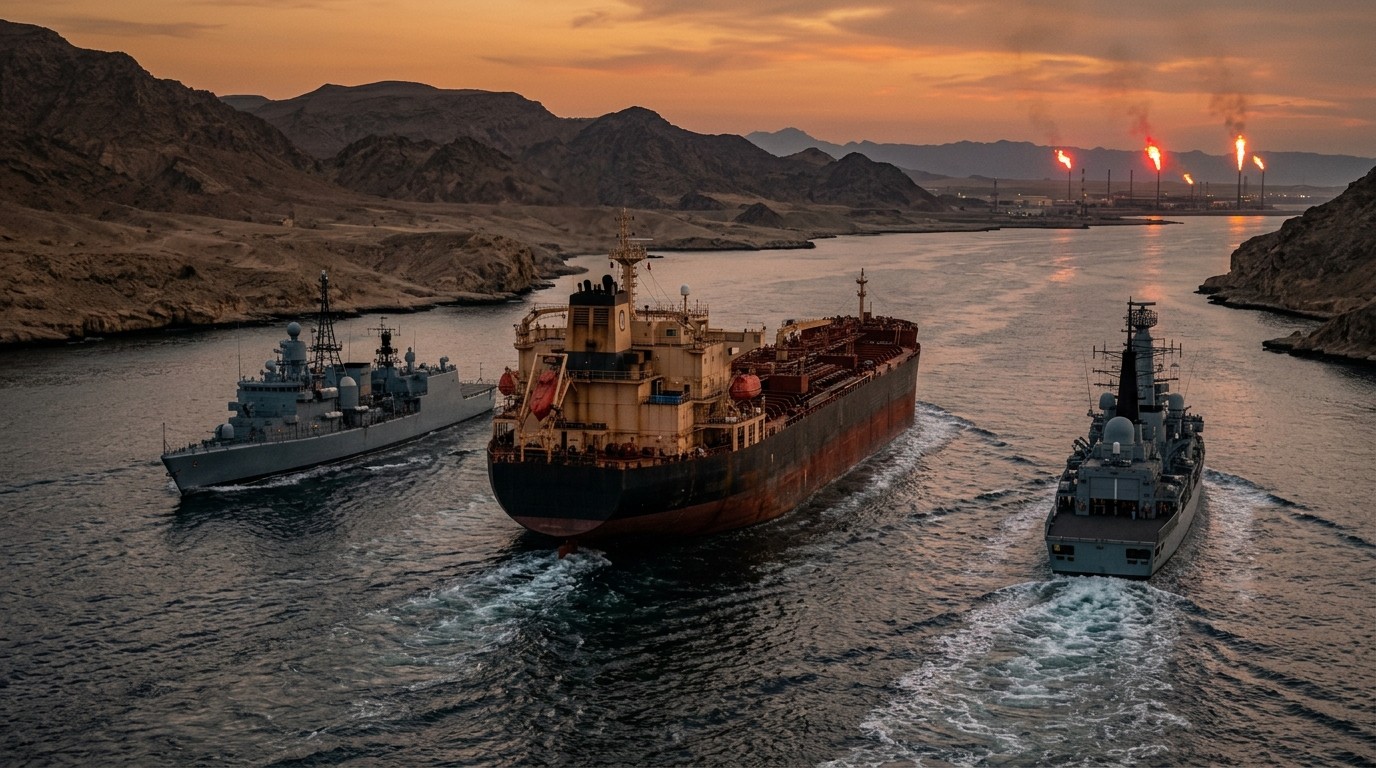
Military officials described an effort spanning a couple of months: commercial traffic protected, crude lifted out of the Gulf, a visible show that the lane remains open. Think of it as a floating corridor rather than a free highway. Captains still calculate risk. Insurers still price fear. Some cargoes still travel in ways that are hard to track in public data.
Those harder-to-see movements matter. Analysts tracking loadings talk about a pickup driven in part by dark transits through the strait. Visible volumes in laboratory-style satellite and AIS products do not always match the full picture. When official counts look thin and physical barrels still show up in Asia, something is slipping through the statistical net.
Reduced worry about the next few days is not the same as confidence about how this ends.
That line, more or less, is the mood among energy desks. Near-term flows improved. Resolution did not. Attacks on vessels did not magically stop because an admiral gave a Saturday briefing. Projectiles still found hulls late in the week. One side claimed a strike after what it called an illegal crossing. The details will be argued for months. The market only needs to know the water is not quiet.
The Price Action Looks Calm Until You Check Diesel
Brent futures settled near one hundred three dollars and eighty-seven cents on Friday after drifting toward one hundred three into the weekend. Mixed political headlines and talk of diplomacy around a major United Nations gathering helped take some heat off the front month. Hope is a tradable commodity. It just expires faster than a futures contract.
The more honest tell sits in the diesel crack spread, which closed around one hundred twelve dollars and sixty cents a barrel. That is not a crude story. That is a refining story. When the crack stays that wide, the system is screaming that middle distillates are the tight piece, not the raw barrel sitting in a floating storage tank.
Perhaps the most interesting aspect is how easily a crude-focused narrative can hide a heating-oil and trucking-fuel problem. People see “oil is off a few dollars” and assume the worst is priced. Fleet managers and European refiners know better. A wide crack is a bill that shows up at the pump, in freight rates, and in winter heating budgets.
Loadings Are Recovering In Uneven Waves
Gulf crude loadings excluding Iranian barrels jumped above ten million barrels a day over a recent two-day window. On a weekly basis they sat near eight point one million, the strongest stretch since the conflict phase began, versus an August average closer to five and a half. Saudi and Iraqi barrels did the heavy lifting. Fresh Iranian crude loadings, by contrast, stayed absent from the public tape.
Bypass routes tell another half of the tale. Including a key UAE hub, those loadings averaged about two and a half million barrels a day over two days and roughly four point nine million so far in September. That sits above August’s three point four million and below July’s six point four million. Product loadings in the Gulf bounced a bit above one and a half million after spending much of the conflict period under one million.
In my experience, these stair-step recoveries fool people. A two-day spike looks like a V-shape. A weekly average still eight million barrels short of the old normal is a flatline with a twitch. Do not confuse a twitch with health.
| Flow Measure | Recent Reading | Pre-Conflict Benchmark |
| Hormuz plus bypass, two-day burst | About 14 million b/d | Above 20 million b/d |
| Same routes, weekly average | About 12 million b/d | Above 20 million b/d |
| Gulf crude loadings ex-Iran, week | About 8.1 million b/d | Higher and more stable |
| Bypass loadings, September so far | About 4.9 million b/d | July nearer 6.4 million |
| Implied weekly shortfall | More than 8 million b/d | Not applicable |
The Pipeline Problem Nobody Can Wish Away
One reason Hormuz traffic matter so much right now is simple geography. An important East-West pipeline link has been disrupted. That forced more barrels back toward the strait just when the strait became a shooting gallery. Kingdom officials have already signaled to major European refiners that crude loadings tied to that system could halt next month if the disruption drags on.
Rerouting is not free. It is not instant. And it is not a perfect substitute for a dedicated westbound line that used to keep some Gulf crude off the most exposed water. When that line coughs, Hormuz becomes the relief valve and the risk concentrator at the same time. Cute, in a grim way.
Reports that a major producer will lift more barrels from an Omani outlet toward Asia over coming weeks fit the same pattern. If the west looks blocked or politically awkward, cargoes hunt east. Asia will take them if the price works. Europe then leans harder on other grades, on products, and on whatever still clears the strait under escort.
Dark Transits, Lng Oddities, And The Fog Of Shipping Data
Energy analysts keep repeating a phrase that sounds like a spy novel: dark transits. It means movements that do not light up the usual tracking products the way a normal commercial voyage would. In a live conflict zone, that is not surprising. It is still frustrating if you are trying to count barrels for a winter balance sheet.
Another small tell: a second liquefied natural gas carrier left the Gulf this month. Gas is not diesel, but it is another reminder that energy traffic of several kinds is still picking cautious paths through the same narrow water. The Bab el Mandeb lane, farther west, has stayed inside its recent range rather than collapsing or exploding. That is stability of a sort. It is not comfort.
- Visible AIS and lab-style flow data can lag real loadings.
- Escorted tankers can move while unescorted owners stay in port.
- Product barrels recover later than crude barrels after a scare.
- Insurance and war-risk premia can choke trade without a formal blockade.
- A single projectile incident can freeze fixtures for days.
None of that is academic. Charter rates, demurrage, and delayed arrivals show up in physical premiums long before they show up in a tidy weekly export table.
Diplomacy Week Versus A “Big Decision”
Political calendar risk is sitting on top of the barrels. The U.S. president said he would soon make a big decision on whether to launch a major campaign aimed at breaking the Iranian regime. He called it a big decision, then added that anything could happen to him. That is not the language of a quiet weekend. Gulf leaders are due in the same diplomatic window. The United Nations gathering adds another stage for speeches, side deals, and last-minute off-ramps.
I am not in the business of predicting war rooms. I will say this as a markets person: kinetic options, a push to secure or neutralize a key Iranian export island, and a next round of sanctions that reach beyond Tehran and into its largest crude customer are all different trades. They rhyme. They do not price the same.
Some desks suspect any major move waits until after midterm elections. That may be cynical. It may also be how large democracies actually sequence risk. Markets do not need the guess to be perfect. They need a distribution of outcomes. Right now that distribution still includes a sudden reopening of the strait risk premium.
Anything could happen is not a forecast. It is a volatility warning dressed as a sentence.
Why The Eight Million Barrel Gap Still Rules The Outlook
Do the simple math and keep it ugly. Twenty-plus million barrels a day used to clear this system. Twelve million on a weekly average is the new working number. Fourteen on a hot two-day print is a weather report, not a climate. The gap is more than eight million barrels from these routes alone. Inventories elsewhere can paper over a week. They cannot paper over a season if the gap stays wide into heating demand.
That is why European refiners hearing about halted loadings next month should not shrug. A missing westbound schedule in October is a fourth-quarter problem, not a headline problem. Product yields matter here. A barrel that never arrives cannot be cracked into diesel. A barrel that arrives late still leaves a hole in September and October runs.
Global balances were not overflowing with spare middle distillate before this. Conflict just made the thin spots visible. If you only watch the Brent screen, you will miss the part that actually hurts transport and heating.
How Traders Are Framing The Next Few Weeks
There is a split personality on the desks. One camp says the escort program and the recent loading bounce mean the worst supply shock is behind us. The other camp says the weekly run-rate is still a crisis wearing a better suit. Both can be right for a few sessions. Only one will be right for winter.
- Watch weekly, not two-day, combined Hormuz and bypass flows.
- Separate crude loadings from product loadings. Products lag.
- Track the diesel crack, not just the outright crude future.
- Listen for official loading guidance into Europe for next month.
- Treat every new vessel strike as a fixture freeze until proven otherwise.
- Map political meetings against options expiry and inventory prints.
- Assume Asia can absorb diverted barrels faster than Europe can replace them.
That list is not clever. It is hygiene. People lose money when they fall in love with a single Saturday sound bite.
A Personal Read On The Escort Narrative
I’ll be honest. A billion barrels is good messaging. It is also a stock figure, not a flow figure. Stocks can be impressive while flows remain broken. If you escorted a billion barrels over a couple of months, you still need to ask what the daily rate was, what share would have moved anyway, and what share only moved because a destroyer was nearby.
In my view, the escort program is necessary and insufficient. Necessary because commercial captains will not keep steaming into projectile risk for a thin freight rate. Insufficient because the pre-conflict baseline is still a long way off and because one political decision can put those same escorts into a hotter fight.
There is a human layer too. Crews on those tankers are not abstractions. Neither are the people who will pay more to heat a flat in northern Europe if diesel stays scarce. Markets talk in barrels. Households talk in invoices. Both are real.
Sanctions, Customers, And The Next Turn Of The Screw
If diplomacy fails, pressure often shifts from water to paperwork. Expanded sanctions can target not only the producer but the biggest buyer of its barrels. That kind of step changes the trade map. It also leaks into tanker finance, port access, and the willingness of refiners to touch certain grades even at a discount.
I have watched “secondary” pressure campaigns before. They work slowly, then all at once, when a bank or a shipowner decides the legal risk is no longer worth the margin. You will not see that on a Saturday military brief. You will see it in a sudden drop in fixtures and a jump in the discount on a particular crude.
Kharg Island sits in the background of every serious scenario note. It is the load point that makes Iranian export math work. Talk of securing or neutralizing that node is a different order of escalation from escorting third-country tankers. Markets hear the difference even when television treats every headline as equal noise.
What Resilience Really Means In This Market
Strategy notes have called Middle East exports unexpectedly resilient. That word is doing a lot of work. Resilient compared with a total shutdown? Yes. Resilient compared with last summer’s easy twenty-million-plus barrel days? Not even close. Resilience here means the system found detours. Detours have tolls.
Higher Saudi and Iraqi loadings are the bright line in the recent data. They show producers will push barrels when the water looks briefly safer. They do not show that buyers have replaced every lost Iranian cargo or every delayed westbound parcel. Substitution is messy. Grades differ. Freight differs. Timing differs.
Working market sketch:
  Escorted volume: large stock talking point
  Weekly flow vs old normal: still deeply short
  Diesel crack: the honest stress gauge
  Politics: a fat tail that can reprice everything
  Winter: the deadline that does not slip
If that sketch feels blunt, good. Soft language is how people talk themselves into being underhedged.
Questions Worth Asking Before You Trust The Dip
Is the two-day fourteen-million-barrel print repeatable without another military surge? Can European refiners live with a loading halt next month if the pipeline stays lame? Will Asia keep swallowing extra Oman-linked barrels without crowding out other grades? Does a wide diesel crack mean the next rally starts in products, not in the crude benchmark?
And the uncomfortable one: if a “big decision” goes kinetic after a diplomatic photo line, how many of those two thousand escorted ships still want the voyage?
I do not have a crystal ball. I do have a bias. When officials advertise a billion barrels moved and the weekly flow is still short by more than eight million a day, I treat the advertisement as context, not as a green light. Context is useful. It is not a full tank.
The Winter Clock Is Already Running
Northern Hemisphere winter does not care about talking points. Heating demand arrives on a calendar. Refinery maintenance windows arrive on a calendar. Election calendars and summit calendars sit on top of those, which is a fancy way of saying the next six weeks are crowded.
If flows grind back toward the old twenty-million-barrel world, the crack can ease and Brent can drift without drama. If flows stall near twelve and another vessel gets hit, the market will remember that the escort program was a bridge, not a destination. Bridges are great until someone shells the span.
For now, crude looks less frightening than diesel. Escorts look impressive on a briefing slide. The deficit on the water still looks large enough to matter. That combination is unstable. Unstable markets make for long articles and short nights. They also make for the kind of period where a single sentence from a president, or a single flash from a deck, can undo a week of gentle selling.
So yes, a billion barrels got out. Remember the other number too. More than eight million barrels a day are still missing from the old path. Until those two figures meet in the middle, I would not confuse a calmer Friday settle with a solved energy shock. The ships are moving. The risk is moving with them.