
I keep a small notebook of supply-chain stories that sound technical until they suddenly are not. Last week one of them landed harder than usual. A friend who watches industrial orders, not headlines, mentioned that certain commercial aircraft components bound for China were taking longer to clear. Not banned. Just slower. Quantities trimmed. The kind of friction that does not make a speech and still rearranges a factory calendar. If you have ever waited on a single missing seal while an entire assembly line sat idle, you already know why that matters.
The timing is the part that stuck with me. Weeks after a high-profile leaders meeting in Washington that was supposed to cool the minerals fight, the paperwork on jet parts started to drag. People briefed on the licensing process describe a deliberate pace: fewer approvals, tighter quantities, and fresh interest in rules that would cover hydraulic fluid, landing gear, and other pieces a planemaker cannot simply print overnight. On the other side of the table, export checks on gallium, germanium, tungsten, and related materials have not loosened. Call it a standoff if you like. I would call it two governments discovering that the other one also knows where the narrow doors are.
Why Aircraft Parts Became a Bargaining Chip
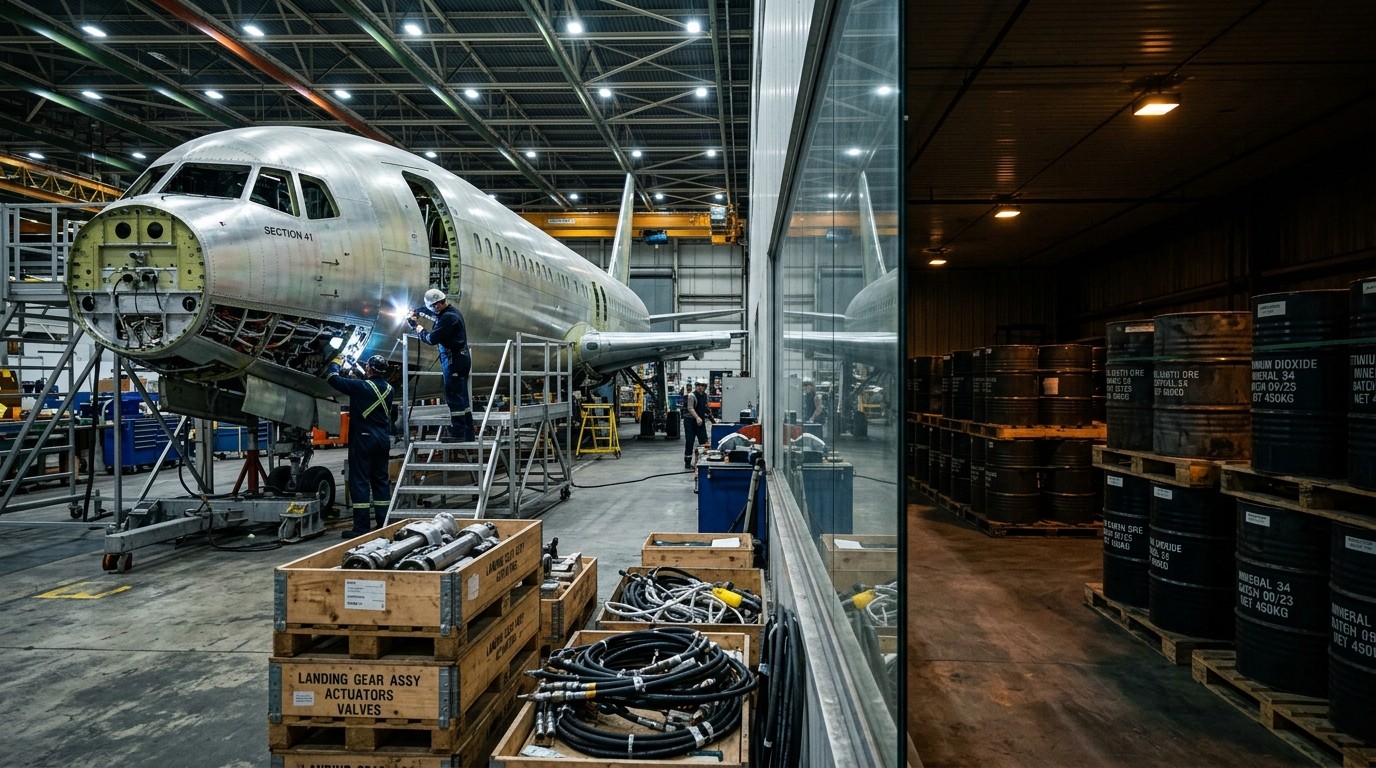
Commercial aviation looks global until you open a bill of materials. A single narrow-body jet is a stack of certified systems: actuators, pumps, seals, avionics boxes, landing-gear forgings, fluids that have to meet a spec written years ago. Many of those items still move under export licenses when the destination is a state-owned manufacturer. Slow the license, and you do not ground a fleet tomorrow. You do something quieter. You stop the buyer from building a quiet stockpile.
That stockpile point is the one officials appear most focused on. People familiar with the licensing desk say approvals for parts headed to China’s state planemaker have been limited in number, specifically so the company cannot sit on a cushion of American-origin components while negotiations drag. I have found that stockpiles are where trade fights get honest. A public statement can be walked back. A warehouse full of actuators cannot.
Officials have also looked at a broader rule that would make it easier to restrict landing gear and related assemblies, and at a draft licensing requirement for aviation hydraulic fluid shipped by large US suppliers. Hydraulic fluid is a dull product until it is the thing you cannot fly without. Put a license on it and you have created a dial, not a wall. Dials are useful in talks. Walls end them.
A license delayed is not the same as a ban. In industrial diplomacy, the delay is often the message.
– Trade desk observation shared with industry contacts
Perhaps the most interesting aspect is how ordinary the tools are. No one needs a new statute with a dramatic name. Export administration already lets a commerce department decide how fast a form moves, how many units a license covers, and which end users get the benefit of the doubt. Stretch that process over several weeks and a production plan written in optimistic ink starts to look fragile.
What the Slowdown Actually Looks Like
From what several people close to the process have described, the squeeze has more than one face. Licensing for airplane parts bound for China has been slowed in recent weeks. Interest has been voiced in an export regulation that would simplify future limits on landing gear and other aircraft parts. A draft has included a new licensing requirement on aviation hydraulic fluid. And the number of parts cleared for the state planemaker has been capped to discourage hoarding.
None of that is a shutdown of civil aviation between the two economies. Airlines still need spares. Lessors still move metal. The target, as described, is narrower: the industrial ramp of a domestic jet program that would rather not depend on foreign certificates forever. That distinction matters if you invest in suppliers. A fleet grounded is a crisis. A program that cannot stockpile is a negotiation.
- Slower export licenses for commercial airplane parts headed to China
- Talk of rules that would make landing-gear limits easier to impose
- A draft licensing idea covering aviation hydraulic fluid
- Quantity caps meant to stop a state planemaker from building inventory
- No public claim, so far, of a full civil-aviation embargo
Short version: friction, not rupture. The long version is where portfolios live.
Why a Planemaker Feels This First
Building a certified commercial jet is a patience sport. You do not swap a landing-gear supplier the way a kitchen swaps a blender. The part has to meet a design spec, survive fatigue tests, carry a paper trail that regulators will actually read, and arrive on a schedule that matches a wing join months away. A state-owned planemaker trying to prove it can deliver on time is exposed in a very specific way. Miss a batch of licensed components and the delay shows up in delivery slots, not in a press release about sovereignty.
I have watched similar squeezes in other industries. The public story is always about strategy. The private story is about a buyer who planned for six months of cover and now has three. Purchasing teams start calling second sources that were “nice to have” last year. Some of those second sources are European. Some are domestic and not yet certified for the exact dash number. Certification is the moat. It is also the delay.
There is a human rhythm to this that spreadsheets miss. Engineers hate redesigning a qualified part in the middle of a ramp. Finance hates paying expedite fees. Sales hates explaining a slipped handover to an airline that already printed the route map. Stack those irritations and you get leverage, even if nobody uses that word in the room.
The Minerals Side of the Same Argument
Jet parts did not appear in a vacuum. They showed up after months of tighter Chinese controls on critical material exports, and after a leaders meeting that, by most accounts from people following the talks, failed to settle the rare earth question. Beijing has spent the past year treating processing capacity as a policy tool. Gallium, germanium, tungsten, and a cluster of related inputs sit inside magnets, semiconductors, optics, and a long list of defense articles. Restrict the export license, ask for end-use detail, slow the customs stamp, and a Western buyer feels it in lead times before the price chart fully catches up.
Resource nationalism is an old habit with a new vocabulary. Countries that dig or refine something scarce have always been tempted to use it when talks get stuck. What feels different now is the overlap. The same decade that is trying to rearm also needs more magnets, more specialty alloys, more sensor materials. A shortage that would have been a niche purchasing problem in a quiet year becomes a program risk when ammunition lines, drone output, and ship schedules are all asking for the same basket of inputs.
In my experience, investors underestimate how lumpy these markets are. Gallium is not copper. You cannot assume a deep exchange inventory will smooth a political decision. A refinery that pauses shipments to one set of buyers can leave a specialty chemical plant short even while the global “market balance” still looks fine on a yearly chart. Yearly charts are a comfort. Weekly melt shops are the reality.
Owning the ore is useful. Owning the step everyone else skipped is better.
That is the quiet theme running under the jet-parts story. One side is probing whether it can slow a civil aircraft ramp. The other is reminding everyone that separation, refining, and magnet-making were outsourced for a reason, and that reason was cost. Cost advantages become bargaining chips the moment the customer cannot wait.
What the Leaders Meeting Failed to Close
High-level meetings are good at producing photographs and bad at producing spare pumps. The session in Washington last month was billed, in the usual way, as a chance to steady the relationship. People who track the minerals file say the rare earth dispute was not resolved. What followed was not a thaw. It was a tighter grip on critical material exports from the Chinese side, and a more visible willingness on the US side to use aviation licensing as a counterweight.
Does that mean the meeting failed? Not entirely. Channels stayed open. Nobody announced a blanket cutoff. But if you were hoping for a schedule that restored predictable shipments of both minerals and parts, you did not get one. Predictability is the product both industrial bases actually buy. Everything else is commentary.
I keep coming back to a simple test. After the handshake, did a purchasing manager sleep better? On the minerals desk, the answer from several buyers I have heard from is no. On the aircraft-parts desk, Chinese planners now have a new variable in the license queue. Both sides can claim they are only enforcing rules that already existed. Both are also teaching the other how those rules bend.
A Bottleneck Map, Not a Morality Play
It is tempting to narrate this as a duel of principles. I think that flattens it. The practical map is a set of narrow industrial steps, each with a dominant processor, a certification habit, or a license form attached.
| Pressure point | Who feels it first | How fast it bites |
| Aircraft part licenses | State planemaker and its suppliers | Weeks to a quarter, via inventory |
| Hydraulic fluid rules | Maintenance and assembly shops | Fast if stocks were thin |
| Landing-gear restrictions | New-build programs | Slow, then sudden at join-up |
| Gallium and germanium checks | Chip, optic, and sensor lines | Lead-time shock, price later |
| Tungsten controls | Tooling, alloys, defense articles | Medium, sticky substitutions |
| Crude access routes | Refiners and freight planners | Depends on the corridor |
Read that table as a menu of delays, not a scoreboard. Some delays are reversible with a signature. Others require a new qualified source, which is a multi-year errand. The side that can impose the reversible delay while sitting on the multi-year choke has the better week. Neither side owns every choke. That is why the fight keeps mutating instead of ending.
Oil Routes Sit in the Background
Minerals and jet parts are the loud items this month. Energy access has been the quieter campaign. Over the past year, US policy has aimed at narrowing China’s path to discounted crude, whether cargoes linked to Cuba, barrels associated with Venezuela, or flows that would rely on a tense Strait of Hormuz. I am not going to pretend every tanker story is a grand strategy. Shipping is messy, insurance is messier, and gray markets have a talent for rerouting. Still, the intent described by officials has been consistent: raise the cost and the hassle of cheap barrels, and let that cost show up in someone’s refining margin.
Why mention crude in an article about actuators? Because leverage stacks. A planemaker worried about landing gear and a refiner worried about feedstock are not the same company, but they sit inside the same political system. When several narrow doors close at once, the incentive to trade one concession for another goes up. Or the incentive to dig in goes up. Both outcomes are plausible. Anyone selling certainty here is selling something they do not have.
Perhaps that is the adult version of trade war. Not a single dramatic embargo. A handful of administrative habits, applied where the other side is thin.
Defense Rearmament Makes Every Gram Louder
Peacetime purchasing can absorb a late shipment. A rearmament cycle cannot, or at least it hates to. Governments across the West are trying to rebuild stocks of munitions, sensors, and platforms after years of drawing them down. Those programs eat specialty metals the way a busy kitchen eats butter. Tungsten shows up in penetrators and tooling. Gallium and germanium show up in compound semiconductors and infrared gear. Rare-earth oxides sit inside the magnets that turn electric motors and actuators. Tell a program manager the oxide will arrive “when the license clears” and watch the Gantt chart flinch.
This is where the phrase own the bottlenecks stops being a slogan and starts being a research agenda. The question is not which country has a flag on a mine. The question is which step, if paused, forces everyone else to wait. Separation plants. Magnet sintering. Certified forgings. Hydraulic formulations with an aviation pedigree. A license stamp. I have found that the unglamorous step is usually the one that matters, which is exactly why it was allowed to concentrate in the first place. Nobody throws a parade for a solvent extraction line.
- Map the certified step, not just the ore body
- Ask how many months of cover a real buyer holds
- Separate reversible license delays from multi-year qualifications
- Watch end-use paperwork, because that is where policy hides
- Price the substitute only after a regulator has signed it
That list is less exciting than a geopolitical thesis. It is also how you avoid buying a story that photographs well and delivers late.
How Suppliers Are Likely to React
American component makers are in an awkward spot, and it is worth sitting with that awkwardness instead of skipping past it. A slower license is not their idea. They still have Chinese customers, after-sales obligations, and shareholders who like smooth quarters. They also have a government that can make the form take longer. The rational response is boring: build a little more inventory at home, document end use until the file is dull, and quietly qualify a second ship-to path that does not depend on one program.
European suppliers will get phone calls. Some will be able to help. Some will discover that their own export offices have questions once volumes jump. A surge in “friendly” orders is how secondary controls spread. I would not assume a European stamp is a free pass. I would assume it is a different queue.
On the Chinese side, the industrial response is the one planners have rehearsed for years: localize, dual-source, and complain about unfair rules while doing both. Localization of a landing-gear system is not a press-conference project. It is metallurgy, machining tolerance, and a regulator who will not sign early to make a speech land better. Progress is real. It is also slower than slogans. The license squeeze is designed to exploit exactly that gap.
What Airlines and Lessors Should Watch
If you lease metal or sell tickets, the near-term question is whether this stays inside a manufacturer’s build schedule or leaks into the spare-parts pool that keeps existing jets flying. So far, the descriptions I have heard point at new-build licensing and stockpile control, not at a broad cutoff of airline maintenance. That can change. Maintenance is full of small certified parts, and small parts are easy to sweep into a wider rule once the lawyers are already in the draft.
A practical watchlist, if you run a fleet into or out of the region:
- Lead times on actuators, pumps, and landing-gear piece parts
- Any new end-use affidavit asked of a hydraulic-fluid order
- Whether a lessor’s heavy check starts slipping for paperwork rather than hangar space
- Quiet warnings from OEMs about “allocation” instead of outright refusal
Allocation is the polite word for a queue. Queues are where policy becomes a departure board.
Markets Will Price the Story in Pieces
Public markets are clumsy with this kind of news. A headline about rare earths spikes a basket of miners that may not refine anything. A headline about jet parts nudges aerospace suppliers that may not even ship the licensed item. The cleaner read is narrower. Who sells certified commercial components into a Chinese final-assembly line? Who processes gallium or germanium outside the dominant chain? Who machines tungsten and already has Western aerospace or defense qualifications? Who merely owns a deposit and a slide deck?
I have a bias here, and I should admit it. I would rather own the qualified processor with a boring contract than the explorer with a brilliant jurisdiction story. Qualification is slow, which is another way of saying the customer cannot leave quickly. In a licensing fight, customers who cannot leave are the ones writing the urgent emails. Urgent emails are not a business model. They are a hint about pricing power.
There is a second bias worth naming. Inventory builds in front of a feared restriction can look like demand. They are not. If buyers are pulling forward actuators or oxides because they distrust next quarter’s license, the shipment print flatters the seller and empties the cupboard. When the license either arrives or the program slips, the order book goes quiet. Traders who only watch revenue miss that handoff. Purchasing managers do not.
A simple filter I keep using:
  Is the product certified for flight or fight?
  Can the buyer switch inside twelve months?
  Does a license, not a price, set the delivery date?
  If yes, yes, and yes, the headline is not noise.
Apply that filter and a lot of “critical minerals” equity pitches fall out. The ones that remain are fewer, duller, and more interesting.
Substitution Is a Slide, Not a Schedule
Every restriction produces a deck about alternatives. Alternative magnets with less heavy rare earth content. Alternative landing-gear steels. Alternative fluids. Some of those alternatives are genuine engineering. Some are a hope with a footnote. The difference shows up in testing hours. An airline will not accept a fluid because a white paper says the viscosity is close. A missile program will not accept a magnet because a startup sintered a puck. Close is not certified.
That lag is the whole game. If substitution took a month, export controls would be a nuisance. Because it often takes years, controls become a calendar. Calendars are what negotiators trade. I suspect both capitals understand this better than the commentary does. The commentary wants a winner by Friday. The test lab wants another cycle.
There is room for real progress anyway. Friend-shoring of separation capacity, recycling of magnet scrap, and long-term offtakes have all moved from panel talk to actual capex in the last two years. None of it replaces a dominant processor this quarter. All of it changes the threat in five years, which is why the side with today’s bottleneck has a reason to use it before the window narrows. Use it too hard, and you fund the other side’s plant. That is the trap inside the leverage.
A Note on Rhetoric and Reality
You will hear both governments describe their moves as defensive. One will say it is protecting civil technology from diversion. The other will say it is protecting strategic resources from unfair containment. Both sentences can be true in a lawyer’s sense and still function as pressure. I do not find the rhetoric very useful for positioning. I find the forms useful. A new license line on hydraulic fluid is a fact a buyer can plan around. A speech about win-win cooperation is not.
Recent policy tracking by export specialists, rather than any single dramatic announcement, is what supports the picture of a slower parts pipeline and continued mineral tightness. Treat unnamed official interest as interest, not as enacted rule. Drafts get rewritten. Quantity caps get adjusted after a phone call. The direction, though, has been consistent enough that a planner who ignores it is choosing hope over schedule.
Hope is not a lead time.
That line sounds glib until you have eaten a missed delivery. Then it sounds like operations.
Scenarios Worth Actually Holding
I am wary of three-scenario slides because the middle one is usually where the author hides. Still, the next two quarters probably rhyme with one of these paths.
A managed thaw. Licenses speed back up. Mineral export approvals become predictable again, with more paperwork but fewer surprises. Both sides claim they defended their interests. Suppliers ship the backlog and investors get bored, which is a kind of victory. I would not bet the farm here, but I would not price it at zero. Meetings that fail once sometimes succeed on the second pass, especially if a domestic industry starts complaining loudly enough.
A grinding stalemate. This is my base case, and I say that with the usual humility. Parts keep moving, just not in the volumes a planemaker would like for inventory. Minerals keep moving, just not on the old timetable. Everyone adapts badly and then adapts a little better. Equity reactions fade. Operating friction does not. The money is made by companies that can live inside friction without rewriting their whole plant.
A wider sweep. Hydraulic fluid, landing gear, and a longer list of civil components fall under tighter rules. Mineral controls expand to more downstream products. Energy corridors get messier. This is the tail, not the center. It is also the tail that breaks models, because so many “diversified” supply chains still meet in two or three rooms.
If you only prepare for the tail, you will overtrade every rumor. If you only prepare for the thaw, you will be the person explaining a slipped quarter. The stalemate is the annoying adult outcome. It is also the one that rewards people who read license notes.
What a Careful Reader Should Do This Month
No article can hand you a trade. It can hand you a cleaner set of questions. Ask which of your holdings actually ship a licensed aerospace part, as opposed to owning a supplier two tiers away that might feel a breeze. Ask which miners in the portfolio separate or refine, and which ones only drill. Ask whether a “critical minerals” ETF is a magnet story, a lithium story, or a marketing story. Those are different weather systems.
Then ask a ruder question. If the license queue stays slow for six months, who runs out of cover first: the planemaker, the fluid distributor, or the sensor line waiting on germanium? The first to run out is where price and politics meet. The others are spectators until they are not.
I have found that writing the question down changes the way you read the next headline. You stop collecting drama. You start collecting dates.
Friction test: license delay + thin inventory + slow substitute = real exposurePin that somewhere unsentimental. It will outlast the week’s vocabulary.
The Industrial Mood, Without the Slogan
Walk a shop floor that depends on a foreign certificate and the mood is not ideological. It is tired. People want the part, the fluid, the powder, on the day the traveler said it would arrive. They will tolerate politics if the box still shows up. They get sharp when the box becomes a theory. That sharpness is now visible on both ends of this particular argument. Chinese assembly planners do not want their ramp held hostage to a commerce form. Western magnet and sensor buyers do not want their quarter held hostage to an export stamp. Each is being asked to live with the other’s form.
There is a temptation, in write-ups like this, to declare a winner. I am not going to. A country that refines the mineral and a country that certifies the actuator can hurt each other without either one “winning” the decade. Winning, if the word belongs here at all, looks like building the missing step at home before the other side needs the concession. That project is underway in pieces. It is not finished. Until it is finished, administrative friction will keep getting drafted into service.
So the notebook stays open. Jet parts this month. Maybe a fluid rule next. Maybe a quieter mineral license the month after. The story will keep changing costume. The wardrobe is small: a form, a quota, a qualified part, a refinery that everyone else skipped because it was dull. Dull is having a very loud year.
Reading the Next Rumor Without Getting Spun
When the next item drops, a few habits help. Separate what a source says officials have explored from what has been published as a rule. Explored is a conversation. Published is a constraint. Check whether the affected product is a production part or a spare. Check whether the buyer named is a planemaker, an airline, or a trading house stocking for either. And give yourself an afternoon before you let a price move tell you what the policy was. Price moves are opinions with leverage. Policy is a PDF, eventually.
One more habit, and then I will stop lecturing. Talk to someone who buys the thing. Not an analyst who models the thing. A buyer. Buyers will tell you whether the license is actually slower, whether the distributor is allocating, whether the Chinese counterpart just asked for a longer firm window. That conversation is worth more than a thread of hot takes. It is also harder to get, which is why most commentary skips it and still sounds sure.
I am not sure. I am watching a licensing tempo and a mineral tempo move in opposite directions after a meeting that was supposed to sync them. That is enough to take seriously. It is not enough to pretend the ending has been printed.
The Longer Arc Under the Weekly Noise
Step back from this week’s forms and a larger pattern shows. For twenty years, commercial aerospace and specialty materials both optimized for cost and scale. Final assembly could sit in one country, certified parts in another, separation chemistry in a third. The optimization worked. Tickets got cheaper. Magnets got cheaper. Defense ministries got used to buying from catalogs that assumed the catalog would always be there.
The catalog assumption is what is breaking, not the physics. Aluminum still flies. Rare-earth oxides still make strong magnets. Hydraulic fluid still pushes a ram. What changed is the willingness of governments to put a clerk between the purchase order and the loading dock. Once both sides have proved they will use the clerk, every long-term supply contract needs a political appendix. Most contracts do not have one yet. Lawyers will add them. Premiums will follow, quietly, inside lead times rather than inside list prices.
That premium is the investment story I trust more than any single ticker. Companies that can document origin, carry qualified inventory, and speak both engineering and export administration will charge for the inconvenience. Companies that only offer the lowest ex-works price will discover that lowest is no longer the bid that wins. I have seen this shift in energy equipment and in semiconductor tools. Aerospace parts and critical minerals are late to the same party, not exempt from it.
Will it last? Administrative fights can cool as fast as they heat, especially when a domestic champion misses a delivery and calls its own capital. Durability depends on whether voters and factories feel the cost. A delayed business jet program is abstract. A delayed defense delivery is less abstract. A spike in a specialty metal that shows up inside a consumer device is how the abstract becomes a hearing. Hearings produce either a deal or a subsidy. Sometimes both, in the same week, from people who do not admit the contradiction.
Where This Leaves a Patient Investor
Patience is an overused word in market writing. Here it has a specific meaning. The qualified alternative to a Chinese separated oxide, or to an American certified actuator in a Chinese jet program, will not be online because a column demanded it. It will be online when a plant works, a regulator signs, and a customer places a second order without being begged. Until those three things happen, the bottleneck owner keeps the option to tighten.
So the practical posture is unheroic. Prefer balance sheets that can fund a slow qualification. Prefer management teams that talk about permits and customer audits more than they talk about total addressable market. Treat sudden export “bans” in headlines as a prompt to read the actual scope. And keep a little skepticism about anyone, including me, who sounds too tidy. Supply chains are full of workarounds. Workarounds fail at the worst time. Both sentences are true, which is why this beat never quite resolves.
If the notebook entry from last week is right, the next chapters are already drafted in some licensing office: fewer parts per approval, a fluid rule on someone’s desk, mineral stamps that still take longer than a buyer budgeted. None of that needs a new nickname. It needs a calendar and a warehouse count. Bring those, and the showdown looks less like theater and more like industry. Industry, inconveniently, is where the money is made and lost.
I will leave it there, with the box either on the dock or still in the queue. That is the only scoreboard that has ever mattered to the people turning the wrenches.