
Have you ever watched a market day unfold where the numbers just refuse to match the feeling in your gut? Thursday felt exactly like that. The fear gauge on Wall Street leaped higher than it has in months, yet plenty of people who live inside the tape still think the move barely scratched the surface of the tension underneath. I have spent enough time around these swings to know that when the official measure of anxiety lags the actual chaos on screens, something interesting—and often uncomfortable—tends to follow.
Decoding the Latest Market Jolt
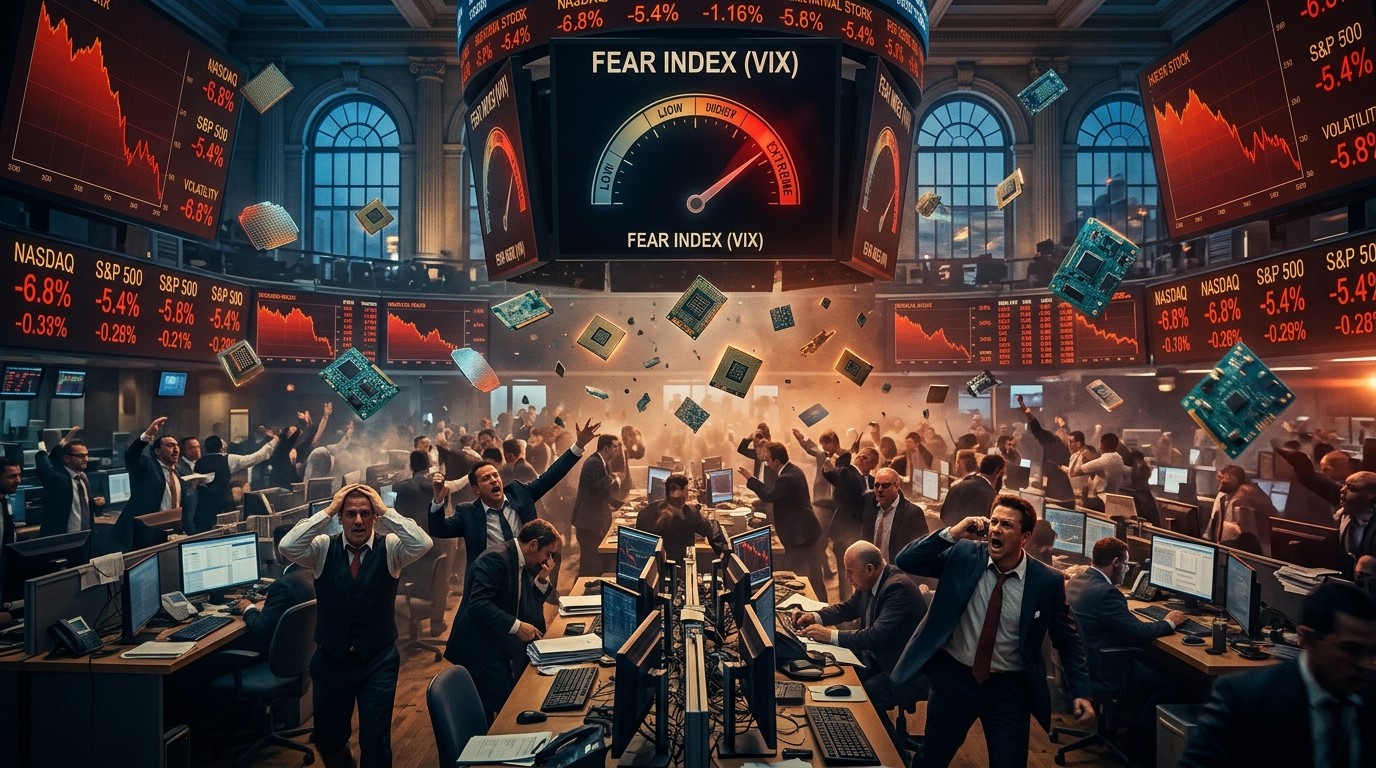
From its low to its high on Thursday the gauge traveled more than eleven points. That kind of single-session expansion last appeared in early April, right around the period when broader indexes were still digesting an earlier bout of selling. The index itself closed the session well above the mid-twenties, a zone that historically signals traders are pricing in larger daily swings than they were just days earlier. Meanwhile the broader market was on track for its worst single-day drop since the spring of the previous year. A rough rule many desks still use is that sixteen points on the gauge roughly corresponds to a one-percent daily move in the main index. By that yardstick the decline we saw should have produced an even larger reading. The gap between what the math suggested and what actually printed is exactly what has people talking.
Perhaps the most interesting aspect is how little the usual suspects moved. Energy prices stayed relatively quiet. Longer-term interest rates barely budged. Those two factors often drive the biggest volatility spikes when they shift sharply. Their absence forces attention onto something more structural inside the equity market itself. One trader I have followed for years put it bluntly: the tape looked like a liquidation. That single word carries weight. Liquidations are not orderly rebalancing exercises. They are forced sales that can cascade once leverage starts to unwind.
What the Numbers Actually Show
The gauge opened the day already elevated and then accelerated after the opening bell. Within roughly ninety minutes it had added several full points and pushed into territory not seen since the final day of March. That earlier peak coincided with a period of heightened geopolitical concern, yet the subsequent market recovery proved relatively quick once the immediate headlines faded. This time the backdrop feels different. The selling has been concentrated in a single high-profile sector that had enjoyed an extended run earlier in the year. When a group that accounts for a large slice of overall index weight begins to reverse, the rest of the market often feels the weight even if other areas remain stable.
Call volume on the gauge itself exploded. Nearly eight hundred thousand contracts changed hands by midday, roughly three and a half times the recent thirty-day average. That kind of activity tells you two things at once. First, traders are actively buying protection or betting on further expansion in expected volatility. Second, the demand is arriving after the move has already begun, which sometimes means the real positioning adjustments are still ahead rather than behind us. In my experience these volume surges can act as a delayed confirmation that the market has finally recognized a risk that was building under the surface for weeks.
My data says to de-risk, but my gut says this is a blowout that could create a dip-buying opportunity. I do not see macro stuff causing this, like oil or rates. Those things are relatively unchanged. The tape looks like a liquidation.
– Veteran market participant
The Semiconductor Wrinkle
Wednesday already offered a strange preview. A major semiconductor exchange-traded fund dropped three percent, yet the fear gauge itself fell more than four points on the same session. According to data tracked by market statisticians, that combination had never occurred before. The next day the same group continued lower and the gauge finally responded. The delayed reaction is what has some observers convinced the current reading still understates the pressure. When a sector that had been the primary engine of gains for months begins to correct, the psychological impact often exceeds the pure mathematical impact on the index.
Semiconductor shares had reached their peak in June. From that point a slow erosion set in, interrupted by occasional rebounds that failed to reclaim the highs. Thursday’s action simply accelerated a process that had already been underway. Whether the catalyst was a referendum on upcoming political events or simply the continuation of that longer downtrend remains open to debate. What is clearer is that few participants had positioned for the speed of the latest leg lower. That lack of preparation is visible in the options market, where demand for upside calls on the fear gauge itself surged.
- Semiconductor ETF down sharply on consecutive sessions
- First-ever instance of large VIX decline alongside semiconductor drop
- Subsequent session produced the opposite and larger move
- Call volume on the gauge ran multiple times normal levels
Why Many Still Expect Higher Readings
The disconnect between price action and the fear gauge is not new, but the size of the gap on Thursday stood out. When the main index falls three percent, history suggests the gauge should have stretched further. Some desks are therefore treating the current level as a temporary floor rather than a ceiling. They argue that once leveraged positions begin to exit in size, the feedback loop can push expected volatility higher even if the underlying index stabilizes. Others point to the concentration of selling. When one sector dominates the decline, the rest of the market can appear calmer than it actually is. That calm can vanish quickly if the selling broadens.
I have found that these moments often separate two types of participants. The first group looks at the absolute level of the gauge and decides the worst is already priced in. The second group looks at the rate of change and the volume behind it and concludes the adjustment is only beginning. Both can be right at different time horizons. The short-term tape can remain disorderly while longer-term valuation arguments slowly reassert themselves. Right now the short-term tape is winning the argument.
Historical Context and Parallels
The last time the gauge posted a comparable one-day expansion was in early April. That episode followed a sharp sell-off that had already driven the main index to a local low the previous day. Once the immediate pressure eased, volatility contracted and prices recovered. The current episode shares the speed of the move but lacks the same clear external catalyst. Geopolitical headlines were relatively quiet. Macro data did not deliver a major surprise. The absence of an obvious external driver is what makes some observers more cautious. Internal market mechanics—positioning, leverage, sector concentration—can be harder to reverse than a single news event.
Looking further back, similar gaps between realized and implied volatility have appeared during periods of sector rotation. When leadership changes hands, the transition rarely happens smoothly. The old leaders must be sold and the new ones accumulated. That process itself generates volatility even if the overall index does not collapse. Thursday’s action may simply be the latest chapter in a rotation that began months earlier. The question is whether the rotation stays orderly or whether forced selling accelerates it.
| Period | VIX Move | Index Decline | Primary Driver |
| Early April | Largest daily expansion until Thursday | Sharp multi-day drop | Geopolitical tension |
| Late March | Peak reading near current levels | Local low then rebound | Regional conflict fears |
| Current Thursday | More than eleven points low-to-high | Approaching three percent | Sector liquidation |
Options Market Signals
The surge in call activity on the gauge is worth examining more closely. Traders do not buy thousands of calls on a volatility product unless they expect further expansion or need protection against it. The fact that volume ran several times the recent average suggests the demand is broad rather than the work of one or two large desks. At the same time, the fact that the volume arrived after the gauge had already risen implies some participants were caught offside. That pattern often precedes additional volatility as those participants adjust.
One subtle detail stands out. The same day the semiconductor group sold off hard on Wednesday, the gauge itself declined. That combination is rare enough that it has never been recorded before in the available data set. The market was essentially saying the drop was contained and did not require higher protection. Twenty-four hours later the opposite message arrived. Markets can change their mind quickly when the selling persists. The options market is now pricing a higher probability of continued disorder.
Possible Drivers Beyond the Obvious
Several explanations are circulating. One centers on upcoming political events and the possibility that investors are beginning to price a wider range of outcomes. Another points simply to the long-term chart of the semiconductor group. Once a multi-month downtrend reasserts itself, technical selling can feed on itself. A third explanation, the one that keeps coming up in conversations, is forced liquidation by leveraged players. When a hedge fund or similar vehicle faces redemptions or margin pressure, the sales are not discretionary. They continue until the pressure is relieved, regardless of short-term price levels.
I tend to put more weight on the third explanation right now. Macro variables were quiet. The political calendar has been known for months. What changed on Thursday was the intensity of the selling in a concentrated group of names. That intensity is consistent with someone needing to reduce exposure quickly. Whether that someone is a single large fund or a cluster of smaller ones is almost beside the point. The market feels the aggregate flow.
- Quiet macro backdrop reduces the chance of an external shock narrative
- Semiconductor downtrend dates back to the June peak
- Volume and price action consistent with forced rather than voluntary selling
- Options demand arrived after the initial spike, suggesting reactive positioning
Implications for Different Types of Investors
For short-term traders the message is straightforward. Elevated and still-rising expected volatility means wider daily ranges and a higher chance of sharp reversals. Stops need to be wider or positions smaller. For longer-term investors the picture is more nuanced. A three-percent decline in the main index is uncomfortable but not historically extreme. The key variable is whether the selling remains concentrated or begins to spread. If it remains concentrated, the rest of the market can continue to offer relative stability. If it spreads, the current reading on the gauge will look low in hindsight.
From what I have observed over multiple cycles, these concentrated liquidations often create the best entry points in the names that were not the primary source of the selling. The difficulty is distinguishing between a temporary liquidity event and the start of a broader re-pricing. Thursday’s action still looks more like the former, but the volume in volatility products suggests the market is not yet convinced. That tension is what makes the next few sessions important.
Reading the Tape Going Forward
Several things are worth watching. First, does the semiconductor group stabilize or continue lower? A stabilization would reduce the most obvious source of pressure. Second, does the fear gauge hold its gains or begin to contract even if prices remain soft? A contraction would suggest the worst of the positioning adjustment is complete. Third, does selling begin to appear in other sectors that had been relatively quiet? Broadening would be the clearest signal that the current reading is too low.
Markets rarely move in straight lines. Even during periods of elevated fear, sharp counter-trend bounces are common. Those bounces can be violent precisely because so many participants are positioned for further weakness. The trader whose data said “de-risk” while his gut said “dip-buying opportunity” was expressing exactly that tension. Both instincts can be correct depending on the time frame. The data may correctly identify elevated risk in the near term while the gut correctly senses that the longer-term opportunity is improving as prices fall.
Practical Considerations for Positioning
Anyone managing risk right now faces a familiar trade-off. Reducing exposure protects against further downside but also locks in the current discomfort and reduces the chance of participating in any rebound. Maintaining exposure preserves the upside but leaves the portfolio vulnerable if the liquidation continues. There is no universal answer. The correct response depends on time horizon, existing risk budget, and how concentrated the portfolio already is in the areas under pressure.
One approach that has worked for some is to reduce exposure selectively rather than across the board. Trimming the names or sectors that have already shown the most weakness while holding or even adding to areas that have remained stable can improve the risk profile without abandoning the market entirely. Others prefer to use options to define their downside while keeping the underlying positions. The elevated call volume on the gauge itself shows that many professionals are already doing something similar. They are paying up for protection rather than simply exiting.
Simple Risk Checklist:
  Review concentration in recent leaders
  Check leverage and margin levels
  Note options demand on volatility products
  Watch breadth outside the weakest sector
  Distinguish forced versus voluntary selling
The Psychology of the Moment
Fear gauges exist because human psychology is not linear. A two-percent decline feels manageable. A three-percent decline can feel like the start of something larger, especially when it arrives quickly and concentrates in familiar names. The official measure tries to quantify that shift in feeling. When the measure lags the feeling, as it appeared to on Thursday, participants often become more aggressive in their hedging. That aggression can become self-reinforcing for a time.
At the same time, markets have a long history of overshooting. The same liquidation that pushes the gauge higher can also push prices to levels that later look attractive. The difficulty is that the overshoot is only obvious in retrospect. In real time it simply feels like more of the same. That is why experienced participants often describe these periods as uncomfortable even when they ultimately prove profitable. The discomfort is the price of staying engaged while others are forced to leave.
Broader Market Structure Observations
The concentration of market leadership in a relatively small number of names has been a feature for an extended period. When that leadership reverses, the impact on indexes is outsized relative to the number of companies involved. Thursday illustrated the point clearly. A sharp move in one sector was enough to drag the broader index lower and to finally lift the fear gauge. This structure is not new, but it does mean that volatility events can appear more suddenly than they would in a more evenly balanced market.
Some observers have argued for months that the narrowness itself was a source of latent risk. The argument is simple: if a handful of stocks account for most of the gains, then any sustained weakness in those stocks will have an amplified effect. Thursday did not prove the argument correct in a lasting way, but it did provide a live demonstration of the mechanism. Whether the demonstration remains a one-day event or becomes a multi-week process is the open question.
Looking at Similar Episodes
Past periods of sector-specific liquidation have produced a range of outcomes. In some cases the selling stayed contained, the rest of the market held up, and the fear gauge peaked within days. In other cases the initial sector move was the first step in a broader reallocation that lasted weeks or months. The difference often came down to whether leverage was involved and whether other sectors began to show their own signs of stress. So far the evidence points more toward a contained event, but the options market is not yet treating it that way.
One pattern that has repeated is the tendency for volatility to remain elevated for several sessions after the initial spike, even if prices stabilize. Traders who sold protection too early have often been forced to cover at worse levels. Those who waited for clearer signs of stabilization have sometimes been able to add exposure at better prices. The current setup contains elements of both possibilities. The speed of the move argues for caution. The lack of a clear macro catalyst argues that the pressure may not last indefinitely.
What Would Change the Picture
A clear stabilization in the semiconductor group would be the most direct positive development. If those shares simply stop falling, the most visible source of selling pressure disappears. A contraction in the fear gauge while the index remains near current levels would be another constructive sign. It would suggest that the demand for protection is being satisfied and that forced sellers are nearing the end of their activity. Conversely, any broadening of the decline into previously stable sectors would confirm the more cautious view and likely push the gauge higher still.
External developments could also shift the narrative quickly. A sudden move in rates or energy prices, even if they were quiet on Thursday, would give the market a new variable to price. So far those variables have remained in the background. Their continued quiet would keep attention on the internal dynamics of positioning and sector rotation. Those dynamics can resolve themselves without outside help, but they can also persist longer than many expect.
Final Thoughts on the Current Setup
Thursday delivered a clear message that the market’s tolerance for further weakness in its recent leaders is limited. The fear gauge responded, volume in related options surged, and the broader index recorded a decline that stood out against recent experience. At the same time, the absence of major moves in rates or commodities keeps the episode from looking like a classic macro-driven event. It looks more like an internal adjustment, possibly accelerated by leverage.
Whether the gauge has already captured the full extent of that adjustment is the debate. The rule-of-thumb relationship between index moves and expected volatility suggests room for a higher reading. The historical rarity of the previous day’s combination of semiconductor weakness and a falling gauge adds to the sense that the market was slow to recognize the risk. Slow recognition is often followed by a catch-up period. That catch-up may already be underway, or it may still have further to run.
In the end these moments test both analysis and temperament. The numbers provide one set of signals. The feel of the tape provides another. When they diverge, as they did on Thursday, the most useful response is usually to respect both rather than to insist that one must be wrong. The data may correctly flag elevated near-term risk. The possibility of a buying opportunity may also be real once the forced selling runs its course. Holding both ideas at once is uncomfortable. It is also, more often than not, the most accurate description of what the market is actually doing.
Markets will continue to produce days like this. The participants who navigate them best tend to be the ones who can distinguish between a temporary liquidity event and a lasting change in the underlying trend, and who size their responses accordingly. Thursday gave everyone fresh information. How that information is used over the next several sessions will determine whether the current reading on the fear gauge was too low, just right, or already the peak of this particular episode.