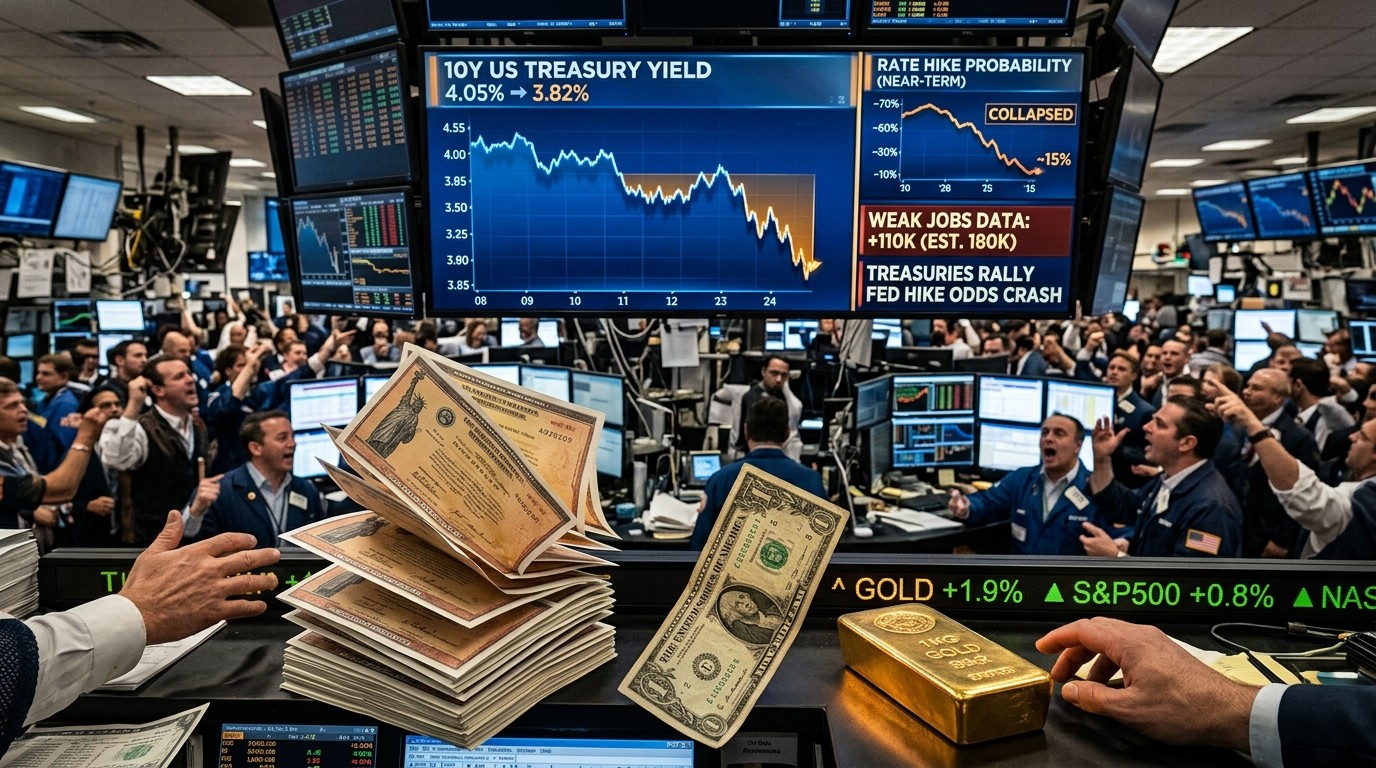

I was halfway through a second coffee when the number landed, and the tape did not wait for anyone to finish reading the footnote. A payrolls print that slipped under even the gloomiest desk forecast is the kind of surprise that rearranges a morning. Not because one month of hiring decides the economy, but because positioning was already leaning so hard the other way. Yields fell. Odds of another near-term hike dropped like a stone. Stocks jumped, the dollar softened, and gold found a bid. Crypto joined the party. If you only watched the headline, you missed the real story: a crowded short in global bonds finally had a reason to run for the exit.
Perhaps the most interesting aspect is how little drama the labor market needed to produce a loud market reaction. The miss was ugly. The revisions made it uglier. Together they handed systematic sellers a problem they had been ignoring on the way in. I have found that the violent moves rarely come from the data alone. They come from the gap between what funds were paid to believe and what the print forces them to mark.
Why A Soft Jobs Print Turned Into A Bond Squeeze
Heading into the release, trend-following books were not mildly underweight duration. Desk models described them as extremely short global bonds, on the order of hundreds of billions in notional. The long end of the Treasury curve sat near the top of historical short extremes. The ten-year complex was described as almost fully maxed out on the short side. The thirty-year looked fully there. That is not a subtle lean. That is a crowd standing on the same side of a narrow door.
A weak print, or even a jobless rate that refuses to cool, is exactly the kind of spark those models are built to respect. When the signal flips, the same rules that piled into the short start buying back. Price rises. Stops get tagged. The next model sees the momentum and joins. That loop is what traders mean by a bond short squeeze. It feels mechanical because, for a large slice of the flow, it is.
Crowded shorts do not need a recession to unwind. They need a reason the model can read, and a morning when nobody wants to be last through the door.
Rates desk observation
In my experience, people over-explain these sessions with narratives about the Fed’s soul. The cleaner read is plumbing. If you are short a market that gaps against you, you cover. If your risk system cuts exposure when volatility jumps, you cover faster. The dovish story arrives afterward, tidy and quotable, once the screens have already done the work.
What The Payroll Miss Actually Said
The headline hiring figure came in below the weakest published forecast. That alone is rare. Forecast ranges are built to look wide. Missing the entire band tells you the consensus was not merely optimistic. It was anchored to a labor market that had already started to cool under the surface.
Revisions did the quieter damage. July and August together were marked down by about 60,000 jobs versus the earlier prints. Sixty thousand is not a collapse. It is enough, though, to change the slope of the last quarter. A market that had been trading “still firm” suddenly had to trade “softer than we printed, twice.”
Wage growth also looked less threatening. That matters more than casual readers admit. Policymakers who treat inflation as the supreme concern still watch pay, because pay is the channel that can keep prices sticky. Lower wage pressure plus a less rosy jobs picture does not end the inflation debate. It does reduce the urgency to tighten again in the very next meeting.
- Headline hiring missed the entire analyst range, not just the median.
- Two prior months were revised down by a combined 60,000.
- Pay growth eased, which softens the case for an immediate follow-up hike.
- The unemployment rate remained high enough to keep doves patient.
None of that is a victory lap for anyone who wants a weak economy. A cooler labor market is a mixed gift. Households feel it before bond traders do. The point, for markets, is narrower: the data no longer supported the hike path that had been priced only days earlier.
How Hike Odds Fell Off A Cliff
A week or so before the print, odds of an October hike had climbed above roughly three in four. That is a market talking itself into action. After the number, October was effectively priced out. Not trimmed. Priced out. The whole front of the curve did the talking.
Further out, the path shrank too. Less than one full hike, something like 22.5 basis points in total, sat in the 2026 strip. Only a couple more were left in 2027. Compare that with the “successive quarter-point moves” story some economists had been carrying, and you see the break. The market did not abolish tightening forever. It removed the idea that the next meeting was a live event.
I’ve found that these probability swings look more scientific than they are. Fed funds futures are a crowd poll with leverage attached. When the poll flips, commentary rushes in to explain character and courage at the central bank. Sometimes the officials really did change their minds. Often they had not spoken at all. The futures just stopped believing the old script.
| Piece of the path | Before the print | After the print |
| October hike odds | Above roughly 75 percent | Effectively priced out |
| 2026 total hikes | A firmer tightening bias | Under one full move, near 22.5 bps |
| 2027 residual hikes | Still open-ended | Only about two left in the strip |
| Short-end yields | Supported by hike risk | Led the decline |
Read that table as a mood, not a promise. Futures can reprice again on the next inflation print, the next speech, or a revision that swings the other way. What they cannot do is pretend the October meeting still looks the way it did seven days ago.
The Short End Did The Heavy Lifting
Yields fell across the curve, and the front led. That is the signature of a policy repricing rather than a pure growth scare. When investors fear a recession in the classic sense, the long end often collapses harder, because the market is buying insurance against a long slump. When they are mostly marking down the next hike or two, two-year and five-year notes do the sprinting.
Both things can be true at once. A softer labor market is a growth input. A cancelled October hike is a policy input. This session looked more like the second, with a garnish of the first. Short-dated yields dropped because the cost of being wrong on the next meeting suddenly mattered. Longer bonds rallied too, helped by the squeeze in an already extreme short, but they were not the only story.
Think of the curve as a conversation between “what happens next month” and “what the economy looks like in five years.” Friday’s print interrupted the first conversation. The second one is still arguing.
Systematic Shorts And The Door They Share
Trend followers do not debate speeches. They follow price, volatility, and a set of signals that can be written on a whiteboard. When those signals say global bonds are in a downtrend, the book gets short. When the short gets large enough, the book becomes the market’s problem as well as the manager’s.
Models circulating before the print put that global bond short near $390 billion in notional. You do not need to treat the figure as sacred. You need to treat the direction as real. A notional that size does not exit through a keyhole. It exits by lifting offers, then lifting the next offers, then discovering that the offers were other shorts trying to do the same thing.
US ten-year positioning was described as about 99 percent of maximum short. Thirty-year positioning sat at 100 percent. Those percentiles are model outputs, not census data. Still. When a widely watched framework says the trade is pinned to the ceiling, a weak catalyst does not have to be perfect. It only has to be weak enough to flip the sign.
- Signals build a large short while yields are rising and hike odds are firm.
- A data surprise hits the signal, or simply hits the pain threshold.
- Covers start, price rises, and other rules-based books join.
- Discretionary traders who were also short decide the asymmetry has flipped.
- The rally feeds itself until the short is smaller or a new catalyst appears.
Step four is where it gets human. A portfolio manager can override a model. Many will not, on a Friday, with the short already hurting. Career risk is a quiet input. Missing a squeeze looks worse in the Monday meeting than having been early on a view that “labor is fine.”
Stocks Took The Dovish Translation
Equities did what equities often do when the discount rate blinks. They rose. The leadership was not random. Smaller companies, which live closer to floating-rate debt and domestic demand, led. Long-duration technology, the stuff whose cash flows sit far in the future, joined them. Rate-sensitive is not a slogan here. It is a balance-sheet fact.
A lower expected policy rate is a gift to anything valued on a long stream of earnings. It is also a gift, at least on day one, to borrowers who were staring at another quarter-point on their interest bill. That is why small caps can outperform mega-cap indexes on a day when the macro news is, strictly speaking, worse hiring. The market is not celebrating unemployment. It is celebrating a cheaper cost of money.
I would not romanticize it. A jobs miss that keeps getting revised down eventually stops being a duration trade and starts being an earnings trade. Margins, credit, and consumer spending do not care that the ten-year yield had a good afternoon. If hiring keeps fading, the same small caps that rallied on the rate story can give it back on the growth story. Timing that handoff is the whole uncomfortable game.
Day one belongs to the discount rate. Day twenty belongs to whether the paycheck still clears.
Dollar Down, Gold Up, Crypto In The Slipstream
The dollar dipped as hike odds fell. That is the usual pairing. A currency that had been supported by a higher-for-longer rate story loses a prop when the story thins out. It does not have to collapse. It only has to stop attracting the marginal buyer who was there for the carry.
Gold rose into that dip. You can explain gold as a real-rate asset, a dollar inverse, a chaos hedge, or a fashion. On this morning it mostly behaved like an asset that likes easier policy and a softer greenback. No mystery required. When the front end rallies and the dollar eases, bullion often does not need a speech.
Crypto moved higher alongside it. I treat that as liquidity mood more than as a labor-market opinion. Digital assets do not hire workers. They do respond when the market decides financial conditions just got a shade looser, and when the dollar is no longer the only trade in town. If you want a single sentence: risk assets took the dovish translation, hard assets took the dollar translation, and bonds took both.
Session sketch, not a forecast:
  Bonds: squeeze plus policy repricing
  Stocks: duration and small-cap leadership
  Dollar: softer on fewer hikes
  Gold and crypto: bid as the dollar eased
The Nail In The Coffin, Or Just A Pause
One chief economist called the payroll number the nail in the coffin for an October hike. The line travels because it is blunt. The reasoning under it is plainer. Successive quarter-point moves had been the base case in that shop. After the miss, the officials who want more time before another increase look more likely to win the room.
Another economist pushed the other way, and I think that tension is the useful part. Inflation, in that view, remains the supreme concern. One soft labor print does not rewrite the whole calculus. It does lower the urgency. Wages are cooler. The jobs picture is less rosy. October becomes easier to skip without anyone having to declare a new regime.
Both can sit in the same afternoon. October can be off the table without the hiking cycle being declared dead. That is roughly where the futures landed: no October, a thin residue of tightening later, and a market that will re-litigate all of it the next time prices or pay surprise.
Officials already associated with a hold-and-wait stance had cover before this print. The number handed them more. Proximity to midterm elections is the sort of thing traders mutter about and officials deny. You do not need a conspiracy to explain patience. You need a labor market that just revised itself weaker and a committee that was split on urgency to begin with.
Revisions, And The Data You Wish You Had
The combined 60,000 downward revision is the part I keep coming back to. Markets trade the first print because that is what hits the wire. Policymakers, if they are honest, know the first print is a draft. Two months later the draft has often moved. Sometimes a lot.
It makes you wonder how firm any recent hike decision would have looked with cleaner data in the folder. That is not an accusation. It is a limitation of the statistical system. Survey response rates wander. Seasonal factors argue with reality. A number that moves policy by a quarter point can be revised by more than the policy move was meant to answer.
For traders, the practical lesson is uncomfortable. You cannot wait for the final revision. The squeeze happens on the first headline. By the time the statisticians settle the argument, the short covering is history and a new position has replaced it. Respect the print. Do not marry it.
Inflation Still Sits At The Head Of The Table
Anyone declaring a pivot on one payrolls report is getting ahead of the committee. Several voices were clear that prices remain the binding constraint. A jobs miss changes the speed. It does not, by itself, change the destination if inflation re-accelerates.
That is why the bond rally can be both justified and fragile. Justified, because the October hike was over-priced relative to a labor market that is no longer surprising to the upside. Fragile, because the next consumer-price release can put the hike back on the table before the short has fully covered. Squeeze rallies hate a second catalyst that points the other way.
I keep a simple split in my notes. Labor data argues about urgency. Inflation data argues about permission. Urgency just fell. Permission has not been withdrawn. If you blur those two, you will misread the next speech as a conversion when it was only a delay.
Who Was Actually Short, And Why It Mattered
Not every bond seller is a trend follower. Some are macro funds expressing a higher-for-longer view. Some are asset managers who shortened duration because clients were tired of losses. Some are dealers hedging issuance. The squeeze does not ask for a biography. It asks who has to buy.
Systematic books are the cleanest fuel because their rules are public enough to model. If a widely used trend framework is max short, a large set of copycat signals is max short too. Correlation of method is its own risk. You can be “diversified” across managers and still be one trade.
Discretionary shorts are messier. Some will add on the dip in yields, calling the rally a gift. Others will cut because the October meeting, their actual catalyst, just died. The mix of those two choices decides whether Friday’s move extends on Monday or mean-reverts by lunch.
- Rules-based shorts cover when the signal breaks, not when the narrative feels complete.
- Macro shorts may fade the rally if they still believe inflation wins.
- Real-money accounts often move slower, which can extend a squeeze over days rather than minutes.
- Dealers caught short gamma can amplify whatever direction shows up first.
Small Caps, Duration, And The Rate-Sensitive Tape
The equity response deserves a slower look, because it will be misremembered as “stocks loved a bad jobs number.” They loved a cheaper policy path. The distinction saves you from the next false lesson.
Smaller firms carry more floating-rate debt, thinner cash buffers, and a customer base that is domestic. A skipped hike is immediate relief in that world, even if the relief is only psychological for a week. Long-duration growth stocks care about the discount rate on cash flows that may not arrive until the back half of the decade. Both groups can rally for different arithmetic and still look like one green screen.
Defensive sectors had less to say. If the market were truly frightened about jobs, you would expect staples and utilities to lead, and cyclicals to lag. Leadership in small caps and long tech is a rates tape wearing a labor headline. File that away. It tells you what will break the rally: either a renewed hike scare, or evidence that earnings estimates need to come down.
A Practical Way To Read The Next Few Sessions
I am not in the business of telling anyone what to buy. I am interested in what would confirm the squeeze and what would kill it. Confirmation looks like follows-through buying in the front end even after the first rush of covers, a dollar that stays heavy, and equity leadership that remains rate-sensitive rather than collapsing into pure defensives. A kill looks like a hot inflation print, a hawkish speech that puts October back in play, or a jobs revision narrative that the market decides was a one-off.
Watch the two-year note more than the headline indexes. If the two-year gives back the whole move, the dovish translation failed. If it holds while stocks chop, the bond market is still doing the thinking and equities are waiting for permission. That split shows up more often than the highlight reels admit.
Also watch whether the extreme short percentile actually falls. A rally that happens while models still show managers max short is unfinished business. A rally that happens after the percentile has already dropped is a different animal. The first can extend. The second needs a new buyer.
Squeeze checklist: short percentile down + front-end holding + dollar heavy = follow-through still possibleWhat Patience Looks Like Inside The Committee
Patience is an unfashionable word in a market that prices meetings in basis points. It is still the word several officials have been using. More time. More data. Less need to pre-commit to a cadence of hikes that the labor market may not justify.
The payroll miss makes that language easier to defend. You can sound cautious without sounding dovish in the old sense. You are not promising cuts. You are refusing to hike into a hiring trend that just undershot every forecast and then revised the prior months lower. That is a narrower claim, and narrower claims survive contact with the next data point.
Critics will say delay is itself a choice, and that inflation does not pause because the committee wants another round of evidence. Fair. The counter is that hiking on a number you already suspect is wrong has its own cost. The revisions are a reminder of that cost. A committee that has been burned by stale data tends to slow down. Whether that instinct is wisdom or lag is something only the next year of prices will settle.
The Midterm Shadow, Without The Spy Novel
Traders like to mention the election calendar whenever a hike gets shelved. Sometimes they are pattern-matching. Sometimes they are bored. The cleaner point is political sensitivity around household conditions, not a secret instruction. A labor market that looks softer is a harder backdrop for an aggressive move, whatever anyone claims about independence.
You do not need that layer to explain Friday. The futures market removed October because the data and the positioning said so. Elections might affect tone in speeches. They are a poor explanation for a 75-point swing in implied odds inside an hour. Positioning explains the speed. The print explains the direction.
Gold’s Bid And What It Is Not Saying
A rising gold price on a weak jobs day gets drafted into every grand theory available. Debasement. Distrust. A new monetary order. Maybe later. On this tape, gold rose while the dollar dipped and real-rate expectations eased at the front. That is a sufficient story. Adding three more does not make it truer.
If the dollar rebound arrives with a fresh hike scare, gold’s afternoon bid can fade without any of the grand theories being resolved. If the front end keeps rallying and the dollar stays offered, the bid can stick for reasons that remain boring. Boring is useful. It keeps you from turning a rates session into a worldview.
Crypto As A Liquidity Echo
Digital assets moved up with the rest of the risk complex. I read that as an echo of easier financial conditions, not as a verdict on payroll methodology. When hike odds fall and the dollar softens, speculative assets often catch a bid because the opportunity cost of holding them drops and the short-dollar crowd has a green light.
The echo cuts both ways. A squeeze in bonds that reverses on Monday can take the crypto bid with it. These markets are fast cousins, not causal twins. Treating a Friday pop as a new regime is how accounts get chopped up on the following Tuesday.
How Forecasters Got Boxed In
Missing the entire forecast range is a professional embarrassment, and it should be. Ranges exist so that surprises have a home. When the print falls outside the house, either the survey was herding or the economy moved faster than the models. Both happen. Herding is more common than economists admit, because being close to the median feels safer than being alone and early.
The market does not grade the economists. It grades the position. A herding miss is still a miss if you were short bonds on the consensus. That is the quiet cruelty of these mornings. The people who were “right” in the sense of doubting the labor glow still had to be positioned for it. Doubt without duration is just a conversation.
What A Massive Short Squeeze Does To Psychology
Squeezes change what people are willing to say out loud. Before the print, higher yields and another hike were the respectable view. After it, patience is respectable. The data moved. So did the permission structure. You will hear more talk of “optionality” and “two-sided risk” in the next week, some of it genuine, some of it cover for a stop that already fired.
I have sat through enough of these to distrust the first coherent narrative. The coherent narrative is usually written by the side that just made money. The losing side goes quiet, then returns with a longer horizon. “Still higher for longer, just not in October” is the sentence that lets a short survive the weekend. Sometimes that sentence is right. Sometimes it is a way to avoid admitting the percentile was the problem.
Scenarios Worth Keeping On One Page
Three paths seem honest from here. None of them requires a heroic forecast.
First, the squeeze extends. Covers are incomplete, the front end holds, and October stays dead. Stocks chop higher with rate-sensitive leadership. The dollar stays soft. This path dies if inflation re-accelerates.
Second, a partial give-back. Fast money covers, then macro shorts reload because they do not trust one labor print against sticky prices. Yields retrace part of the drop. Equities keep some of the gain but lose the frantic tone. This is the boring base case, and boring is often where money hides.
Third, the growth scare arrives late. Revisions keep coming in soft, hiring fades again, and the rally in bonds stops being about a skipped hike and starts being about earnings risk. Small caps would be the tell. They led on the way up. They would lag if the story flips from rates to revenue.
| Path | Bond tell | Equity tell |
| Squeeze extends | Front end holds the rally | Small caps and duration lead |
| Partial fade | Yields retrace, curve steadies | Gains stick, leadership widens |
| Growth scare | Long end outperforms later | Cyclicals and small caps lag |
You can trade all three badly. The use of the table is humility. Friday did not pick the ending. It picked the starting position for the next argument.
Where Households Fit In A Bond Story
It is easy, from a rates desk, to treat payrolls as a catalyst. For households it is rent, groceries, and whether the offer letter arrives. A miss under every forecast means somebody’s hiring plan slipped. The 60,000 revision means some of last month’s optimism was on paper. Markets can squeeze higher while that reality sits there, unpriced in human terms.
The link back to portfolios is still real. Consumer spending feeds earnings. Earnings feed the equity half of the dovish trade. If the labor cooling stays mild, the rate relief can dominate. If it steepens, the same portfolios that cheered Friday will have to reprice the cash-flow side. I do not think we know which one this is. I think pretending we do is how the next squeeze, in the other direction, gets built.
Issuance, Dealers, And The Other Side Of The Bid
Treasury supply does not pause because a jobs number missed. Auction calendars keep arriving. Dealers who got lifted out of inventory during the squeeze may be less eager to lean short into the next sale, or more eager if they think the rally overshot. That micro plumbing rarely makes the first headline. It often decides whether a squeeze has a second day.
A market that is short can rally through an auction. A market that has already covered can struggle with the same auction. If you only watch the payroll story, you will miss that handoff. The catalyst opens the door. Supply and dealer balance sheets decide how wide it stays.
Volatility Is The Toll
Squeezes are not free information. They raise realized volatility, which raises the cost of holding the next view, which forces more mechanical cutting. That feedback is why a “small” miss can produce a “massive” move. The miss was the match. The short interest and the vol target were the dry grass.
After the grass burns, vol often settles and the range looks silly in hindsight. Do not let hindsight tidy it up too fast. The range was the market discovering how many people needed the other side at the same time. That discovery is the point of watching positioning before the number, not after the recap.
A Note On Language Around The Fed
Words like “nail in the coffin” are memorable and slightly too final. Committees do not seal coffins on Fridays. They skip meetings, revise dots, and argue. The useful translation of that phrase is simpler: an October hike went from likely in the futures market to unlikely. Anything grander is commentary trying to outrun the strip.
The opposing line, that the broader calculus barely moved because inflation still rules, is the necessary brake. Hold both. October can be off the table while the hiking bias for later years only thins, rather than reverses. That is exactly what a strip with less than one hike in 2026 and a couple left in 2027 is trying to say. Thin. Not gone.
What I Will Be Watching Next
First, whether the short-end rally survives the first full session after the emotion fades. Second, whether small-cap leadership holds or was a one-day duration spasm. Third, the next inflation release, because that is the permission slip. Fourth, any fresh revision chatter that makes traders treat labor data as a moving target rather than a fact.
I will also watch the tone of officials who were already in the wait-and-see camp. If they sound vindicated, October stays buried. If they sound worried that markets over-read a single print, the strip can put some of those basis points back. Speeches are not data. They are still the way a skipped meeting gets confirmed in public.
None of this is a call to lever up into bonds because a model once said the short was extreme. Extremes can stay extreme. The edge, if there is one, was in noticing the asymmetry before the print: max short, a live hike priced, and a labor report that only had to disappoint a little. That asymmetry already paid. The next one has not been written.
Putting The Morning Back Together
So here is the session without the slogans. Hiring missed every forecast that mattered. Prior months were revised down by 60,000 combined. Wage pressure looked less hot. A bond market that systematic models had pinned near a maximum short squeezed higher, led by the front end. October hike odds, recently above 75 percent, were priced out. The leftover path showed less than one hike across 2026 and only a couple further out in 2027. Stocks rose, with small caps and long-duration tech in front. The dollar eased. Gold and crypto caught a bid.
Economists split in a way that actually helps. One camp called it the end of an October move and a reason to slow a cadence of quarter-point hikes. Another camp said the broader decision still hinges on inflation, while granting that urgency dropped. Officials already inclined to wait gained air cover. Midterms hovered in the background chatter and were not required to explain the move.
If you remember one mechanism, remember the door. Hundreds of billions of notional, pointed the same way, do not turn around politely. They turn around all at once, and the price is the bruise. The payroll miss was the excuse. The short was the fuel. Everything else, the equity pop, the softer dollar, the bid in gold, was the market translating a cancelled hike into the assets that care about it.
Would the last policy step have looked different with today’s revisions in hand? Maybe. The data process does not offer do-overs, and neither does a squeeze. You get the print you get, the position you brought, and a few hours in which those two discover each other. Friday was that discovery. The argument about what it means for the next meeting is already underway, and it will not be settled by the first coherent paragraph anyone writes about it. Including this one.