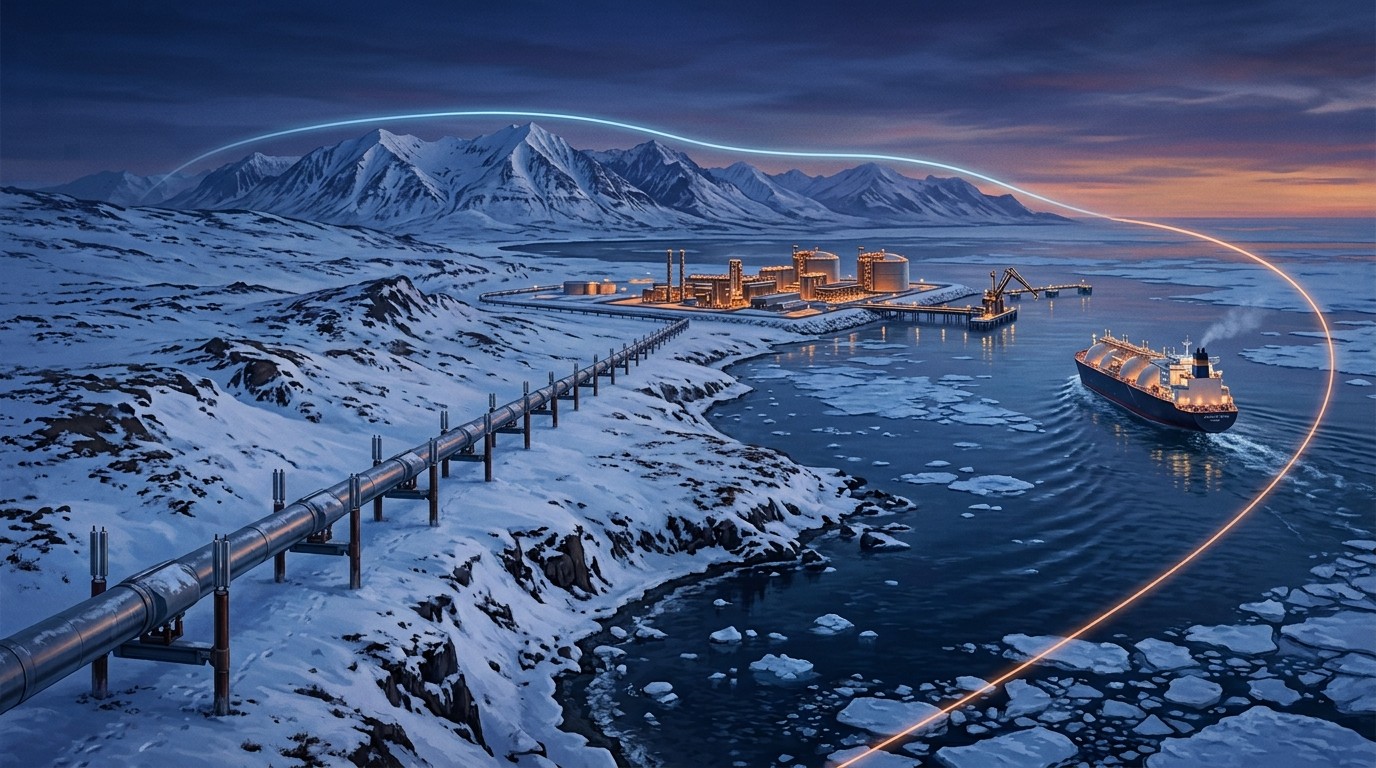

I kept coming back to a number that looks almost too tidy. Seven to nine days on the water from a southern Alaskan terminal to a South Korean port, versus something closer to three or four weeks out of the U.S. Gulf. If energy deals were decided by a map and a stopwatch, this one would already be signed. They are not. The catch sits inland, buried in permafrost, river crossings, and a price tag that can swallow the shipping savings before a single cargo leaves the dock.
That tension is why Seoul is walking, not running, toward Alaska LNG. Washington has framed the project as part of a much larger energy investment story, on the order of $200 billion across nuclear plants, a Texas power facility, and this northern gas export venture. The integrated scheme itself is commonly pitched near $50 billion, with analyst ranges running from roughly $44.5 billion to $54.5 billion. South Korea’s leadership has been plain about the filter: financial viability first, legal compliance next. Friendly politics do not cancel a bad landed price.
The Map Looks Brilliant Until You Price The Pipe
Alaska LNG is not a simple export terminal bolted onto an existing grid of pipes. The concept is an integrated chain. Gas would move from the North Slope, around Prudhoe Bay, through a pipeline on the order of 800 miles, or about 1,300 kilometers, down to a liquefaction site near Nikiski. Nameplate output is often described at 20 million metric tons a year. That is a serious volume. It is also a serious construction problem.
I have found that people outside the gas trade fixate on the voyage and forget the middle. The middle is the project. Building that line across remote terrain, then financing it, then keeping it on schedule, is what decides whether Korean buyers see a bargain or a burden. One Asia-Pacific market specialist put the comparison bluntly: the capital cost can look like enough to build three Gulf Coast projects. Shorter sailing does not automatically win that fight.
A shorter voyage is a real advantage. It is not a free pass on capital cost.
– Energy market analyst, paraphrased
Perhaps the most interesting aspect is how clean the geopolitical pitch sounds next to the commercial one. Cargoes from Nikiski would avoid the Strait of Hormuz. They would also sit outside some of the longer Pacific loops that Gulf molecules have to tolerate. For a country that imports nearly all of its gas, route diversity is not a slogan. It is inventory insurance. Still, insurance has a premium. If that premium is a pipeline whose overrun risk sits with buyers through a twenty-year contract, the policy starts to look expensive.
What The Shorter Route Actually Buys
Shipping time is not just a curiosity for logistics managers. Days at sea show up in boil-off, charter costs, fleet utilization, and the number of ships you need to keep a contract whole. A seven-to-nine-day haul can shrink the fleet required for a given annual volume compared with a twenty-to-thirty-day Gulf run. That is real money. It also reduces exposure to canal delays, weather windows on longer arcs, and the odd political flare-up along a distant choke point.
There is a second, quieter benefit. Shorter routes make scheduling less brittle. A buyer trying to balance winter power burn against industrial offtake likes cargoes that can be retimed without a month of slack. In my experience watching these negotiations from the outside, flexibility is the thing procurement teams brag about after the headline price is forgotten. Alaska could offer some of that. It cannot offer it for free.
- Voyage length of roughly seven to nine days versus twenty to thirty from the Gulf
- Lower exposure to the Strait of Hormuz and some longer Pacific routing risks
- Potentially fewer ships tied up per million tons of annual supply
- Tighter scheduling windows for winter power and industrial buyers
- A northern supply point that diversifies away from Australia, Qatar, and the Gulf
None of those bullets erase the capex. They only explain why the file stays open.
Why Cheaper Molecules Still Win Most Tender Sheets
Ask a Korean buyer what they actually optimize and the answer is rarely “fewest days at sea.” It is landed cost. Feedgas, pipeline tariff, liquefaction, financing, tax, and freight all land in the same cell of the spreadsheet. Analysts who track Asian cargoes have been consistent on the ranking: Australian supply, U.S. Gulf supply, and Qatari supply are widely expected to screen cheaper than Alaska on a full-cost basis. LNG Canada sits in the comparison set as well, with its own Pacific advantage and a very different capital story.
That ranking can move. Henry Hub, oil-linked slopes, freight spikes, and carbon rules all shove the deck around. A project that looks dear in a calm year can look clever in a panicked one. Seoul’s caution, as I read it, is about refusing to pay a structural premium on the hope that panic returns on schedule. Hope is not a procurement strategy.
| Supply option | Route trait | Commercial question for Seoul |
| Alaska LNG | Short sail, huge new pipe | Can shipping savings beat pipeline capex? |
| U.S. Gulf Coast | Longer sail, deeper project bench | Is the longer voyage still cheaper landed? |
| Australia | Established Pacific trade | Does proximity plus existing plants win? |
| Qatar | Scale and low upstream cost | Does volume discount outweigh route risk? |
| LNG Canada | Pacific outlet, different capex | Is this the cleaner northern alternative? |
The table is a sketch, not a tender model. It is enough to show why a presidential handshake does not close a price review.
Cost Overruns Are Not A Footnote In The Arctic
Large linear projects have a habit of eating their contingency. An 800-mile line through difficult country is the sort of job where weather windows, labor logistics, river crossings, and permitting appeals compound. Energy economists who have looked at the scheme point to a long construction timeline and tough terrain as the obvious places where the estimate drifts. Drift is not abstract. It shows up in the toll that offtakers are asked to underwrite.
I’ve found that sponsors talk about overrun risk as if it were a shared weather event. Buyers hear it as a transfer. If the tariff is sized to a hopeful budget and the budget slips, someone pays. On a take-or-pay contract that someone is often the importer, for twenty years or more. That is a long time to be polite about a number that moved.
South Korean firms are not naive about heavy industry. They build ships, steel, and plants for a living. Familiarity cuts both ways. They know what a delayed module costs. They also know that a non-binding letter is not the same thing as a check. One industrial name has been linked to a preliminary, non-binding outline covering about 1 million metric tons a year for twenty years, plus potential steel supply for the line. Useful signal. Not a government underwriting.
Demand Is Slowing Just As The Contract Would Lock
Here is the part that makes procurement teams squint. South Korea’s gas burn in the power sector is widely expected to ease as the generation mix shifts. Nuclear restarts, renewables, and efficiency all nibble at the same load that long-term LNG was meant to cover. Industrial demand does not vanish, and winter still arrives, but the direction of travel matters when you are asked to sign volume you might not want in year twelve.
Take-or-pay is the industry’s way of making a plant bankable. It is also the buyer’s way of getting stuck. If domestic demand softens and the contract does not, you are in the resale market, hoping Asian spot prices cooperate. Sometimes they do. Sometimes you are the motivated seller everyone else can smell. Analysts covering Korean buyers have noted exactly this selectivity. New long-term commitments are not refused on principle. They are refused when the volume does not match the curve.
Locking volume into a slowing power market is how a strategic cargo becomes a stranded obligation.
Would I sign a twenty-year pipe-backed contract if my own power plan pointed down? Only with a price, a flexibility clause, and an exit ramp I could explain to a board. That is not cynicism. It is the job.
Politics Can Open The Door And Still Not Pay The Bill
The strategic overlay is obvious. Seoul balances a security relationship with Washington against a commercial test it cannot fake. Saying the project is “under discussion” keeps the diplomatic channel warm. Saying participation depends on viability and legal compliance keeps the finance ministry in the room. Both sentences can be true on the same afternoon.
There is leverage in that posture, and it is worth naming. A buyer who has not committed can still ask for fiscal support, tax treatment, credit wraps, or a clearer permitting path. A buyer who has already signed away the option mostly asks for sympathy. Korean commentators close to the energy file have argued that holding the commercial line may be the cleanest way to invite extra U.S. support rather than absorb the gap alone.
Legal compliance is not filler language either. Cross-border energy deals pick up export rules, sanctions screening, environmental review, and procurement law. A project that looks financeable on a slide can stall in a permit docket. Seoul flagging that early is less a rebuff than a refusal to inherit someone else’s unresolved file.
What Would Actually Move Seoul From Cautious To Committed
The test, stripped of ceremony, is the landed number after every layer is counted. Feedgas netback. Pipeline tariff. Liquefaction fee. Cost of capital. Tax. Shipping. If that stack beats, or at least matches, the alternatives a Korean utility can already see, the politics get much easier. If it does not, no amount of podium language will drag a credit committee across the line.
Greater certainty would help on five fronts that keep showing up in serious notes on the project.
- A fiscal framework that does not shift after financial close
- Financing that is identified, not imagined, including any public support
- A construction plan that prices terrain and schedule with adult contingency
- Permitting risk that is mapped, timed, and not waved away
- A role for Korean firms beyond the title of buyer
That last item is easy to underestimate. Selling steel for the line, engineering packages, equipment, and LNG shipping gives industrial constituencies a reason to stay in the room when the commodity price looks ordinary. A pure offtake deal asks the buyer to carry the strategic story alone. Mixed participation spreads the reason to care. It does not fix a bad tariff. It does change who argues for the file inside Seoul.
Buyers, Builders, And The Gap Between Them
Commercial involvement so far looks preliminary, and that word matters. A non-binding outline for a million tons a year plus steel is a scouting report. It is separate from any broader government investment pledge. Treating the two as the same document is how rumors outrun term sheets.
Korean yards and steelmakers know how to show up on a resource project when the scope is real. They also know how to step back when the offtake is soft. If U.S. support arrives as tax incentives or financing assistance, the industrial case strengthens. If support stays rhetorical, the case stays a press release. I would watch the equipment and shipping packages as closely as the volume. Those are the tells.
Rough decision stack for a Korean buyer:
  Landed price versus Australia, Gulf, Qatar, Canada
  Demand fit over 20 years, not just year one
  Overrun exposure inside the tariff
  Flexibility: divert, cancel, or price review
  Industrial workshare beyond offtake
  Legal and permitting path still open
None of this requires hostility toward the project. It requires arithmetic.
How The $200 Billion Frame Changes The Optics
Wrapping Alaska LNG inside a wider energy package changes the photograph more than the model. Nuclear plants and a Texas generation site give diplomats a portfolio to point at. Portfolio logic can hide a weak asset inside a strong relationship. It can also do the opposite: force every line item to justify itself so the package does not become a grab bag.
Seoul’s public line suggests the second reading. Viability is not a vibe. If the northern gas piece cannot stand up, it should not ride on the nuclear piece. Investors who blur those files will misread the news flow. A warm statement about “working on” the project is not a final investment decision. It is an invitation to keep modeling.
There is a fair counterpoint. Strategic buyers sometimes pay a small premium for route diversity, the way a household pays for a second insurer. A modest premium is negotiable. A premium large enough to fund an entire extra pipeline is a different conversation. The argument in Seoul, as far as public comments go, is that the market has not yet shown the premium is modest.
What Gulf Coast Abundance Does To The Negotiation
The U.S. Gulf is not standing still. A deep bench of liquefaction projects, existing pipes, and a liquid Henry Hub marker gives buyers alternatives that did not exist a decade ago. Competition is Seoul’s friend. It is also Alaska’s problem. When a buyer can point at another U.S. molecule with a longer sail but a shorter capex story, the northern project has to win on something other than the flag.
That something could be schedule certainty, a negotiated tariff, or a shipping advantage that survives a freight spike. It is unlikely to be patriotism. Commercial teams are paid to ignore patriotism once the term sheet is open. Perhaps that sounds blunt. It is also why these deals take years.
Qatar’s scale and Australia’s proximity do the same work from other directions. Alaska is asking to join a club that already has cheap, delivered members. Joining is possible. Dues are not optional.
Financing Is The Quiet Veto
Even a lovely cost curve dies in a credit committee if the capital stack is fog. Projects in this size range live or die on who takes construction risk, who wraps the debt, and what happens if the first cargo slips by eighteen months. Public support can lower the cost of capital enough to change the landed price. Absent that support, equity has to be paid like equity, and equity is not cheap on a remote pipeline.
Tax incentives matter for the same reason. They are not decorations. They are line items. A clearer fiscal framework lets lenders stop padding the model for political surprise. Surprise is what Korean buyers say they are trying not to import.
I keep a simple rule for files like this. If the sponsors cannot name the capital, the buyers should not name the volume. Preliminary agreements exist precisely so that rule can be respected without a diplomatic incident.
Permits, Terrain, And The Calendar Nobody Prints
Construction risk and permitting risk rhyme. Both steal years. An Arctic-to-coast pipeline crosses land, water, and jurisdictions that do not share a single calendar. Environmental review, community process, and right-of-way work can be done well and still take time. Done badly, they take longer and cost more.
Buyers do not need to become permitting lawyers. They do need a dated path. “We expect approvals” is not a date. A date with a contingency is. Until that exists, a twenty-year sales contract is a promise tied to a moving start. Korean demand planning does not enjoy moving starts. Power auctions and nuclear schedules are already full of them.
Terrain deserves its own sentence. Permafrost, rivers, and winter construction windows are not marketing copy. They are productivity assumptions. If those assumptions are heroic, the tariff is fiction. Serious counterparties will ask to see the productivity case. They should.
A Practical Reading For Investors Watching The File
If you follow gas equities, shippers, or Korean industrials, the useful question is not whether leaders smiled in a photo. It is which milestone would actually change cash flow odds. A binding offtake at a price that clears Korean alternatives would be one. A financed pipe with identified public support would be another. Steel and module awards with Korean names on them would be a third, smaller, but tradable.
Until those show up, treat headline investment totals as a diplomatic envelope. Envelopes are real. They are not invoices. The spread between the two is where cautious language lives, and Seoul has chosen that spread on purpose.
- Separate government rhetoric from binding offtake
- Track landed-cost claims against Gulf, Australia, Qatar, and Canada
- Watch whether Korean industry wins work, not just volume talk
- Discount schedules that skip permitting and winter productivity
- Treat demand softness in Korean power as a contract-design issue
That list will age better than any single press line.
The Contract Clauses That Would Make Caution Soften
Price is the headline. Clauses are the fine print that decide whether a cautious buyer can live with it. Destination flexibility, price review windows, a credible cancellation option, and a sharing mechanism for capex overrun would all change the feel of a twenty-year promise. None of them are exotic. They are how sophisticated importers keep optionalty when the demand curve is no longer a straight line up.
Volume shape matters too. A flat million tons every year is easy to model and hard to love if power burn fades. Seasonal shape, or a ramp that matches nuclear and renewable buildout, would fit the Korean system better. Sponsors prefer flat because lenders prefer flat. The negotiation is often exactly that argument.
Could Alaska accept a less lender-friendly shape if public credit fills the gap? Maybe. That is one reason U.S. support keeps appearing in the serious commentary. Support is not only about making equity happier. It is about buying room for contract terms a slowing market can actually sign.
Shipping Advantage, Stress-Tested
Let us pressure the seven-day story, because it is the project’s best postcard. In a normal freight year, days saved are worth a defined amount per million British thermal units. In a spiked freight year, days saved are worth more. In a crashed freight year, they are worth less, and the pipeline tariff does not crash with them. Structural costs and cyclical savings do not move together. That mismatch is the heart of Seoul’s hesitation.
Avoiding Hormuz is similarly state-dependent. In a quiet Gulf, the insurance value is small. In a noisy Gulf, it is the whole conversation. Paying for that option every year, through capex, is rational only if you believe noise is frequent enough. Some security planners do. Some commercial planners want the option priced, not assumed.
I do not think either camp is unserious. I think they are optimizing different loss functions. The commercial loss function is currently winning the public statements out of Seoul. That can change if the security loss function gets more expensive. It has not, on the evidence of the caution, changed enough.
Industrial Participation Is A Bridge, Not A Subsidy
Steel for an 800-mile line is not a rounding error. Pipe mills care. So do engineering houses and shipowners who might carry the LNG. Offering those roles is smart diplomacy and smart procurement. It creates domestic winners who can explain the project in industrial terms rather than alliance terms.
Still, workshare is not a price. A yard can love a hull order and a utility can hate the cargo price at the same time. Governments sometimes pretend those interests are identical. They are related. They are not identical. The cleanest outcome is a tariff that stands on its own, plus industrial packages that stand on their own. Bundling them to hide a weak tariff is how projects earn a reputation.
The preliminary steel-and-volume outline already hints at this bridge. Keeping it non-binding is the correct stage. Binding it before the landed cost is known would be the incorrect stage. Sequence is a strategy.
Where Legal Compliance Stops Being Boilerplate
Cross-border gas is a thicket. Export authorizations, environmental conditions, local content arguments, and financing covenants all have to point the same direction before a board signs. When Korean officials mention legal compliance, read it as a request for a clean file, not a rhetorical dodge. A clean file is financeable. A messy file becomes someone else’s political problem, usually the offtaker’s.
There is also the quieter issue of how any public money is structured. Support that looks like a subsidy to one side can look like a trade irritant to another. Designing assistance so it survives scrutiny is part of making the project real. Skipping that design is part of how announcements age badly.
None of this is unique to Alaska. It is simply more visible because the capex is large and the buyer is cautious in public. Visibility is useful. It forces the stack of costs into daylight.
A Scenario Sketch, Not A Forecast
Three paths seem more plausible than a binary yes or no. First, the project gathers enough fiscal and financing certainty that a Korean buyer takes a slice, not the whole book, at a price close to competing Pacific supply. Second, the commercial gap stays wide, industrial talks continue, and the diplomatic language stays warm while capital stays home. Third, a freight or security shock reprices the shipping advantage so sharply that yesterday’s expensive pipe looks like insurance everyone wishes they had bought.
I lean toward the second path as the base case, with pieces of the first if support is concrete. The third is a tail. Tails happen. You do not underwrite a $50 billion system on a tail unless someone else is holding a large share of the downside. That, again, is the financing question in different clothes.
Notice what is missing. A scenario where Seoul signs because a press event felt historic. That scenario is popular on timelines. It is rare in credit files.
How To Read The Next Headline Without Getting Spun
When the next statement lands, sort the verbs. “Explore,” “work on,” and “welcome” are not “commit,” “finance,” or “offtake.” Sort the volumes. A million tons is not 20 million. Sort the binding language. Non-binding is a scout. Binding is a position. Sort the price silence. If nobody will quote a landed range, the range is probably the problem.
Also sort who is speaking. A commerce official and a utility treasurer do not carry the same signature authority. Confusing them is how markets gap on air. The cautious line from Seoul has been remarkably consistent with the treasurer’s job, even when the diplomatic photo suggested otherwise. Consistency is information.
Headline filter: verb + volume + binding status + price silence = real or ceremonialUse it. It will save you a few false starts.
The Buyer’s Dilemma In Plain Language
Imagine you run gas supply for a system whose power demand is easing, whose alternative cargoes are plentiful, and whose board remembers the last contract that outlived the need. A partner offers a shorter sail, a giant new pipe, and a place inside a larger investment story. You are not against the partner. You are against paying pipeline rent for a sail you can already approximate with other Pacific tons.
You ask for a number. You ask who eats the overrun. You ask whether your steelmakers and yards get work. You ask whether the law is settled. You ask whether the volume can flex if reactors and renewables do what the plan says. Until those answers land, caution is not timidity. It is sequence.
That is the whole dispute, once the flags are folded. Alaska LNG can still become a Korean supply point. It has a geographic argument that deserves a model. It does not yet have a commercial argument that has survived contact with cheaper tons and a softer demand curve. Seoul is waiting for that contact. Waiting, in this case, is the position.
What A Fair Deal Would Probably Look Like
If I were sketching a version that could actually close, it would be smaller than the podium version and sharper than the rumor version. A defined slice of the 20 million tons, not a symbolic nation-sized pledge. A tariff with a cap on buyer exposure to overrun. A review clause tied to competing Pacific benchmarks. Industrial packages awarded on competitive terms, not as a sweetener taped to a weak price. Financing that names its public and private pieces before the signing photo.
That package would not thrill everyone. Sponsors want more volume and fewer caps. Buyers want more caps and less volume. The overlap is the deal. Outside the overlap there is only a press release with a very round number attached.
Round numbers are having a moment. $200 billion packages and $50 billion projects photograph well. They also hide the only figure a cargo buyer can use, which is dollars per unit delivered in winter to a specific terminal. Until that figure is on the table, Seoul’s caution is the most honest sentence in the file.
Geography starts the conversation. Landed cost ends it.
The route from Nikiski will keep looking elegant on a map. The pipe from the North Slope will keep looking expensive in a model. South Korea can hold both thoughts at once. That is not mixed messaging. That is the job of anyone who has to pay the invoice after the announcement lights go off. If the invoice shrinks, through financing, tax treatment, or a harder look at what the pipe really costs, the elegant route gets a second hearing. If it does not shrink, other cargoes will keep winning the tender, seven days or not.
I suspect the next useful update will not be another joint statement. It will be a tariff range, a financing term, or a binding volume with a price review attached. Any of those would tell you more than a week of podium language. Until then, treat Alaska LNG as a live option with a heavy premium, and treat Seoul’s caution as the premium being marked to market in public. Markets are better when someone is willing to do that marking out loud.