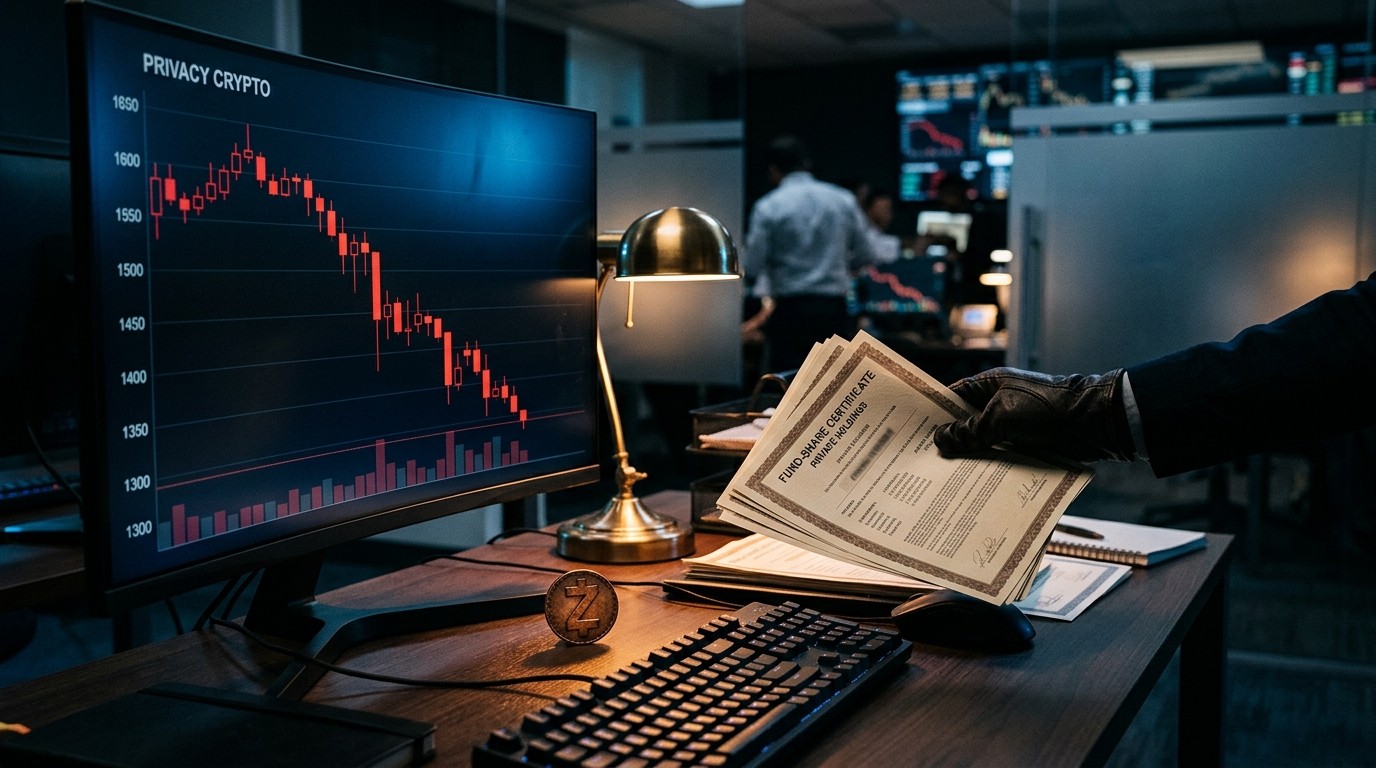

I kept refreshing the weekly flow print because the number looked wrong the first time. A fund that had been swallowing fresh money through September, the same fund that had just crossed the billion-dollar asset line on the back of a roaring privacy-coin rally, finished the week ended October 2 with $93.56 million walking out the door. ZEC, meanwhile, closed October 3 near $1,304, a long way from the late-September print above $1,650. That is roughly a 21 to 23 percent giveback, depending on which high you pin the tape to. Fast money leaves fast. The slower question is whether the wrapper itself changed the way people hold the coin.
What a $93.6 Million Week Actually Tells You
Flow weeks are blunt instruments. They do not tell you who sold, why they sold, or whether the coins that left the fund stayed in the market at all. They do tell you the direction of marginal demand through the regulated pipe. For Grayscale’s Zcash product, ticker ZCSH, that direction flipped. ETF flow trackers put the weekly net outflow at $93.56 million, the first negative week since the end of August. Total net assets settled near $751 million. Cumulative net inflows were still positive, around $212.56 million. The fund is not empty. It is smaller, and smaller in a hurry.
I’ve found that the first red week after a launch-month honeymoon is where the story usually gets honest. Creations are easy to celebrate. Redemptions force a conversation about who the real holder is. Was September a structural bid for privacy exposure inside a brokerage account, or a momentum trade that used the new listing as a convenient on-ramp? Both can be true in the same week. They are not true in the same proportion once the price stops climbing.
The Daily Prints That Built the Weekly Hole
The damage was not spread like butter. It clustered. Flow data showed about $30.25 million leaving on September 30, then another $26.93 million on October 2. Add the quieter sessions and you land on that $93.56 million weekly figure. Two sessions did most of the work. That pattern matters. A slow bleed looks like rebalancing. A pair of heavy days looks like someone, or several someones, deciding the trade was done.
Context keeps the number from floating in space. By mid-September the fund had pulled in roughly $271 million of cumulative net inflows, including a strongest week near $98.2 million. So a single bad week clawed back something on the order of a third of the mid-month cumulative haul, and it nearly matched the size of the best creation week. Not a collapse of the product. A sharp reversal of the marginal bid.
A redemption week does not prove the thesis died. It proves the easy part of the thesis just got tested.
Perhaps the most interesting aspect is how quickly the narrative flipped in public chatter. A month earlier the talking point was access: a long-running trust converted into an exchange-listed product on August 25, trading on NYSE Arca, so a brokerage account could hold ZEC exposure without a wallet. That access story did not vanish. It just stopped being the only story. Access cuts both ways. The same pipe that filled the fund can empty it before lunch.
Assets Fell for Two Reasons, Not One
This is the part people skip, and it is the part that changes the math. ZCSH holds ZEC. When the token price drops, the dollar value of the fund drops even if nobody redeems a share. When people redeem, assets drop even if the token price is flat. September and early October delivered both. Treating the slide from above $1 billion in late September to about $751 million as a pure outflow story overstates the redemptions and understates the mark-to-market hit.
Rough path, from public market reports around the launch: the converted product opened with something like $304 million in assets, pushed past $400 million as ZEC cleared $1,000, then crossed $1 billion late in September as price and creations rose together. That climb was a duet. The descent is a duet too. If you only listen to one instrument, you will mishear the song.
- Weekly net outflow: about $93.56 million, first negative week since late August.
- Heaviest sessions: roughly $30.25 million on September 30 and $26.93 million on October 2.
- Net assets after the week: near $751 million.
- Cumulative net inflows still positive: around $212.56 million.
- Mid-September cumulative inflows had been near $271 million, with a peak week around $98.2 million.
None of those figures is a forecast. They are a receipt. The receipt says demand through the listed product cooled hard, right as the underlying coin was already slipping. Correlation is not a culprit. It is a timing clue.
How the Product Got Here in the First Place
A little history keeps the week from looking like it arrived from nowhere. Grayscale had run a Zcash trust for years. On August 25 that trust became ZCSH, an exchange-traded product investors could buy and sell through a normal brokerage ticket. No seed phrase. No shielded-pool homework. For a coin whose whole identity is privacy, that is an odd kind of convenience, and a powerful one. A lot of capital never touches self-custody. If you want that capital, you meet it where it already sits.
The first weeks did exactly what sponsors hope for. Assets stepped up with the token. ZEC itself had a violent September, up roughly 102 percent over the month leading into the late-September highs, trading near $1,535 on September 26. A listed product plus a doubling coin is a feedback loop. Price pulls in creations. Creations, if they require the sponsor or an authorized participant to source coins, can lean on spot. Spot strength feeds the chart. Then the chart feeds the next creation. Loops feel permanent until they reverse. They are not permanent.
The Price Path Under the Flow Print
Market data sketched a clean staircase down, not a cliff. ZEC closed September 26 at $1,653.12. September 28: $1,483.24. September 30: $1,438.21. October 2: $1,301.16. October 3: $1,304.32. From the September 26 close to the October 3 close is a decline of roughly 21 percent. Headlines rounding that move to 23 percent are in the same neighborhood, especially if you measure from an intraday peak above $1,650 rather than the official close. Either way, the token gave back a fifth of a late-month high inside about a week.
September had started below four figures. So even after the pullback, ZEC was still well above where the month opened. That nuance gets lost when every headline leads with the red number. A coin can be down hard from the high and still up hard from the base. Both statements fit the tape. Traders who bought the breakout feel the first one. Holders who sat through the summer feel the second. The fund sits in between, marking assets in dollars every day.
| Session | ZEC close, approx. | What else was happening |
| September 26 | $1,653.12 | Late-rally peak area, fund assets had crossed $1 billion |
| September 28 | $1,483.24 | Leverage already coming out of perpetuals |
| September 30 | $1,438.21 | About $30.25 million left the ETF; three-for-one split |
| October 2 | $1,301.16 | About $26.93 million left the ETF; upgrade candidate released |
| October 3 | $1,304.32 | Weekly outflow tally settled near $93.56 million |
Look at the dates side by side and the overlap is obvious. Selling pressure in the token showed up before the fund posted its first negative week. By the time the big redemption days hit, ZEC had already lost the $1,500 area and was trading closer to $1,400, with a relative-strength reading that had cooled to about 53. That is not a washed-out oscillator. It is a market that stopped being overbought and had not yet become obviously oversold. Awkward middle ground. Awkward markets redeem.
Leverage Left Before the Fund Did
One venue told the story early. Perpetual open interest on a major derivatives platform fell from about $236.8 million on September 18 to about $165 million on September 28. Traders were cutting leveraged ZEC exposure while the spot price was already retreating. I pay more attention to that kind of shrinkage than to a single red candle. Open interest dropping with price usually means positions are being closed, not just marked down. Someone is choosing to be smaller.
Does that cause an ETF outflow? Not directly. A perpetual trader and an ETF shareholder are often different animals. One is borrowing time. The other is renting a brokerage line. Still, they watch the same chart. When leverage comes out, volatility often follows, stops get tagged, and the discretionary money that chased the September melt-up starts asking whether the next hundred dollars is up or down. Some of that discretionary money lives inside the fund. The timing fits a profit-taking tape better than a sudden loss of faith in the protocol.
Available data does not establish that the withdrawals caused the entire ZEC decline. Falling leverage, profit-taking after a doubling month, and a cooler spot bid were all in the room. The ETF was a loud guest, not the only one. If you need a villain, you will invent one. If you need a read, you keep the guests separate.
A Three-for-One Split on the Heaviest Day
September 30 did double duty. It was the session with the $30.25 million outflow, and it was the day Grayscale completed a three-for-one forward share split on ZCSH. A filing around that date put shares outstanding at 7,989,300 before the split, with net asset value of $111.41 per share. After the adjustment the share count rose to 23,967,900 and NAV per share fell to $37.14. Same pie. Smaller slices.
Shareholders of record on September 28 received two additional shares for each share they already held. The ticker did not change. The exchange did not change. The economic claim on the underlying ZEC did not change, aside from whatever the market and the flows did that day. Splits are cosmetic in theory and psychological in practice. A $37 quote feels different from a $111 quote even when your position value is identical. Retail tickets sometimes prefer the lower print. That is a habit, not a theorem.
Was the split the reason for the outflow? I doubt it. Splits do not force selling. They can coincide with selling because sponsors often pick a moment when the share price has run, and moments when the share price has run are also moments when holders take profits. Coincidence with a cause wearing a similar jacket. Worth separating in your notes, not worth building a theory on.
Split snapshot, September 30
  Shares before: 7,989,300
  NAV before: $111.41
  Shares after: 23,967,900
  NAV after: $37.14
  Investor value: unchanged by the split itself
The Sponsor-Family Check That Landed Earlier
A separate filing showed Digital Currency Group putting roughly $100 million into ZCSH on September 8. The route was an authorized participant, or a designee, in exchange for about 85,705.33 ZEC. The shares DCG received were described as economically the same as other ZCSH shares, with no special preference. That is a large related-party creation, not a secret class of stock.
Related-party creations cut two ways in a young product. They can seed liquidity and signal that the sponsor ecosystem is willing to wear the exposure. They can also inflate the early inflow story if readers treat every creation as unaffiliated demand. A hundred million dollars is not a rounding error against a fund that later sat near three-quarters of a billion. It is also not the whole September bid. The clean reading is simple: insider capital showed up early, outside capital showed up after, and some of the outside capital left in the first week of October. No scandal required. Just a cap table that moved.
Insider money can open the door. It cannot make the crowd stay once the chart turns.
Market notebook, early October
Reading Creations and Redemptions Without the Folklore
Authorized participants sit between the listed share and the coin. In a plain creation, they deliver assets, or cash that gets converted, and receive shares. In a redemption, they return shares and take assets out. The plumbing is boring on purpose. Boring plumbing still moves real coins. When a week shows net redemptions, some quantity of ZEC is, in principle, leaving the fund’s custody and re-entering someone’s inventory. What that someone does next is the variable nobody’s spreadsheet owns.
Three possibilities, none of them exclusive:
- The redeemed coins get sold into spot, adding supply just as price is weak.
- The coins get parked, hedged, or moved into another vehicle, so the fund shrinks without a matching spot dump.
- The redemption is a switch: an investor leaves the wrapper and holds ZEC directly, which changes the holder, not the float.
Public flow prints do not label which door was used. That is why a confident “ETF selling crashed ZEC” line overreaches. It might be partly true on the heavy days. It is not something the weekly total proves. I would rather sit with the ambiguity than decorate it.
Why Privacy Coins Make the Wrapper Feel Strange
Zcash is not a generic altcoin with a logo swap. Its pitch is shielded transactions, a split between transparent and private activity, and a community that argues about how much of the chain should be visible at all. Dropping that asset into a fully visible fund structure is a cultural mismatch even when it is a financial fit. The shareholder can see the product. The product can see its coins. The coin, in its shielded form, is built so outsiders cannot see the transfer. Layers of visibility stacked on a tool designed to reduce visibility. Odd, and also the point of a brokerage product: you outsource the weird part.
Does the ETF holder care about shielded pools? Some do. Many do not. They care that the line item in the account moves with ZEC, that the expense ratio is what the prospectus says, and that they can exit during market hours. That last feature is exactly what September 30 and October 2 demonstrated. Liquidity in the wrapper is a feature on the way in and a feature on the way out. Calling the outflow a failure of liquidity would be backwards. The outflow is liquidity working.
There is a second-order effect worth watching, though. If a growing slice of ZEC sits inside funds, transparent treasuries, and exchange inventories, the visible float gets louder relative to the shielded one. Price discovery then leans even harder on the part of the market that is easiest to track. Privacy maximalists will hate that sentence. Market structure does not take a vote.
The Upgrade Sitting on the Other Side of the Tape
While shareholders were redeeming, developers were shipping. On October 2 the Zcash Foundation put out Zebra 7.0.0-rc.0, the first release candidate for the NU7 upgrade. Testnet activation was expected around October 6 at block height 4,465,026. A final call on the mainnet activation height was scheduled for October 20, after the testnet run, with a roadmap that pointed at November 5 for mainnet. Operators on mainnet were told they did not need to update yet, because the activation height was not final. Testnet operators were asked to install before the October 6 window if they wanted to stay on the NU7 test network.
The design goals are concrete. NU7 aims to cut the target block time from 75 seconds to 25 seconds. Faster blocks change how quickly transactions confirm and how often fees and rewards get sampled. The release also introduces a Network Sustainability Mechanism that redirects a portion of transaction fees toward future block rewards, plus limits meant to keep spam from clogging shielded transactions. Faster blocks, a fee path into future rewards, and spam caps. That is a protocol week, not a marketing week.
Should ETF holders care? Only if they think the coin’s long-run fee and security budget matters to the thing they own. A fund share is a claim on coins, and coins are a claim on a network that has to pay someone to order transactions. If block rewards lean more on a redirected fee stream, the sustainability story shifts from pure issuance toward usage. Usage is not guaranteed by a release candidate. A release candidate is a promise that the code is ready to be argued with in public. Arguments on testnet are cheaper than arguments on mainnet. That is the whole point of the October 6 window.
- Release candidate: Zebra 7.0.0-rc.0, published October 2.
- Testnet target: around October 6, block 4,465,026.
- Block-time goal: 75 seconds down to 25 seconds.
- New piece: a fee redirect toward future block rewards, plus shielded spam limits.
- Mainnet decision window: October 20, with November 5 as the roadmap target.
I would not trade the upgrade as a one-day catalyst. Protocol calendars slip, testnets find bugs, and activation heights move. I would keep it on the same page as the flow story, because a network event landing while a new fund is finding its holder base is how narratives get tangled. A green testnet does not refill an ETF. A delayed mainnet does not force another redemption. People will stitch those sentences together anyway.
What the September Rally Was Actually Pricing
Before the outflow week, ZEC had done something privacy coins do not do every quarter. It doubled over roughly a month and traded, briefly, like a momentum asset rather than a niche tool. Part of that was the listing effect. New wrappers pull in accounts that could not or would not hold the coin directly. Part of it was a broader bid for assets outside the two giants, the usual rotation when large-cap crypto stalls and traders go hunting. Part of it was simply a thin book meeting a sudden bid. Thin books overshoot. They also mean-revert with very little notice.
A fair question, the one I keep coming back to: how much of the September price was the ETF, and how much was the ETF a passenger? The fund launched into a coin already moving, then grew as the coin kept moving, then shrank as the coin fell. That sequence is compatible with the product amplifying a move it did not start. It is also compatible with the product being the move. You would need creation-day coin sourcing, spot volume shares, and a clean counterfactual to separate them. We do not have the counterfactual. We have the sequence. Sequences are allowed to be suggestive without being proof.
From a holder’s chair, the practical split is simpler. If you bought ZCSH because you wanted brokerage access to a privacy coin and you still want that, a 21 percent pullback is a price, not a thesis break. If you bought it because the chart was vertical and the inflow tweets were loud, the first red week is the exit signal you were always going to obey. Products do not know which holder they have. The flow print is the average of those holders changing their minds.
A Worked Example on Position Size
Say you held the pre-split share at a $111.41 NAV on the morning of the split. After the three-for-one, you held three shares at $37.14. Same dollars, before fees and before the day’s market move. Now put a 21 percent token decline under that position from the September 26 area to October 3, and remember that fund assets also reflect flows. Your share does not fall 21 percent solely because the token did, and it does not fall by the outflow percentage either. It falls by the change in NAV, which is mostly the coin, minus expenses, plus or minus any premium or discount the market assigns to the share versus NAV.
Premiums and discounts are the quiet risk in young crypto funds. If the share trades rich to the coins inside, a new buyer is paying extra for convenience. If it trades cheap, a seller is giving convenience away. I have watched plenty of converted trusts spend their first months oscillating around NAV as arbitrage desks learn the creation basket. A heavy redemption week can tighten that arb or stress it, depending on how fast authorized participants can move coins. The $93.56 million figure says they moved. It does not say the spread was calm while they did.
Rough holder checklist:
  1. Separate token move from fund flow.
  2. Check NAV versus share price, not just the headline assets.
  3. Remember the split changed the quote, not the claim.
  4. Treat one red week as a data point, not a regime.
Who the Marginal Seller Might Be
Guessing the seller is a parlor game, so I will label it as one. Fast money that bought the post-listing ramp had a clean profit by late September. A three-for-one split gave them a lower quote and a reason to rebalance position size in share count. A token that had doubled invited exactly the profit-taking that derivatives open interest already hinted at. Advisors who added a small privacy sleeve for clients may have hit an internal risk limit once the position swelled with the rally. Any of those can produce a $30 million day without a manifesto.
The seller I would not assume is the long-term privacy user. That person often holds coins, not fund shares, and often holds them shielded. They did not need August 25 to express the view. The fund’s holder base skews toward people who wanted the view without the operational burden. When that base trims, it says something about convenience capital, not about the shielded pool’s convictions. Conflating the two is how commentary gets loud and wrong.
What Would Make the Outflow a Regime, Not a Week
One negative week is a weather report. A regime is several reports in a row. I would want to see whether creations return on the next green ZEC week, whether assets stabilize near the mid-hundreds of millions or keep stepping down, and whether the cumulative inflow number, still positive near $212 million after this hit, starts a real slide toward zero. A product that gives back its launch inflows and cannot refill them is a different animal from a product that hiccups after a vertical month.
Other tells, none of them magic:
- Redemption days that keep clustering above $20 million without a matching price crash, which would imply holder fatigue rather than pure mark-to-market.
- A persistent discount to NAV, which would imply the arb is slow or the share is unwanted.
- Open interest rebuilding on leverage while the fund keeps shrinking, a split tape between traders and holders.
- Mainnet upgrade slippage that becomes the excuse for a second wave of selling.
- A fresh creation week that absorbs the October hole, which would mark this as digestion.
Until those show up, the honest caption is narrower. ZCSH had its first outflow week since late August. The coin had already been falling. The split was a non-event for value and a real event for the quote. A related party had put in about $100 million three weeks earlier. An upgrade candidate hit the same day as the second heavy redemption session. That is a crowded notebook. Crowded notebooks reward people who refuse to pick a single cause.
Fees, Spreads, and the Cost of Leaving
Leaving a fund is not free in the way a tweet makes it look. You pay the trading spread on the share, you may pay a commission depending on the account, and you wear whatever gap exists between the share price and the value of the coins. If you then buy ZEC directly, you pay that spread too, plus withdrawal friction if you move coins off an exchange. The $93.56 million is a gross flow, not a net economic gain for the people who exited. Some of them locked in September profits large enough that friction did not matter. Some of them paid friction to feel smaller. Both are rational. They are not the same trade.
On the way in, the cost stack was the sales pitch’s unspoken twin. Brokerage convenience has a price: the fund’s expense ratio, the possible premium, the inability to shield the position yourself. September’s buyers accepted that stack because the coin was running. October’s sellers decided the stack was no longer worth it at that price. Markets are a long argument about whether convenience is expensive. This week, a slice of holders voted yes.
Comparing the Week With the Launch Base
Put the bookends on one line. Launch assets were reported around $304 million. Late September assets cleared $1 billion. After the outflow week, assets sat near $751 million. Even after a $93.56 million redemption week and a sharp token drop, the fund was still more than double its opening size. That is not how a failed listing looks. It is how a listing looks after the first real shakeout. Shakeouts are part of the product finding a holder who can sit still.
Cumulative net inflows remaining positive, near $212.56 million, says the same thing in flow language rather than asset language. More money has entered than has left, life to date, even after the worst week. Asset value and cumulative flows diverge whenever the coin moves, which is why both numbers belong in the same paragraph. Quote one and hide the other, and you can argue anything.
| Checkpoint | Approximate figure | Read |
| August 25 conversion | ~$304 million assets | Starting line for the listed product |
| ZEC above $1,000 | Assets past $400 million | Price and creations rising together |
| Mid-September | ~$271 million cumulative inflows | Best stretch of demand |
| Late September | Assets over $1 billion | Peak combination of price and flows |
| Week ended October 2 | $93.56 million out; ~$751 million assets | First red week since late August |
| Life-to-date flows | ~$212.56 million net in | Still a net creation story, smaller |
A Note on Headlines That Round to 23 Percent
Percentages are where market writing gets slippery. From $1,653.12 to $1,304.32 is a drop of $348.80, which is about 21.1 percent. A headline that says 23 percent is either using a higher intraday peak, a different close, or a rounded fear number. I do not think the gap changes the story. I do think you should know which peak you are mourning. Traders who sold $1,600 and traders who sold $1,650 did not have the same week, even if they share a chart.
The same caution applies to “toward $1,300.” October 2 closed at $1,301.16 and October 3 at $1,304.32. Toward $1,300 is fair. Through $1,300, as of those closes, had not stuck. Levels are magnets in commentary and speed bumps in actual books. Treat them as areas.
How I Would Talk About This Without Overclaiming
If I were writing the note for a desk, it would be short. Listed Zcash exposure saw its first net outflow week since late August, $93.56 million, with two sessions doing most of the work. Assets fell to about $751 million, helped lower by the token as well as by redemptions. ZEC retraced roughly a fifth from the September 26 close after a month in which it had about doubled. Leverage had already been leaving. A three-for-one split changed the share count and the NAV print, not the claim. A sponsor affiliate had created about $100 million of shares on September 8. An upgrade candidate aimed at faster blocks and a fee-to-reward redirect is on a testnet clock, with a mainnet decision later in October. None of that is a buy signal or a sell signal. It is the furniture.
The opinion I will actually own is smaller. Convenience products accelerate whatever mood the coin is already in. They did it on the way up in September. They did it on the way down into October. If you hold the share, decide whether you are paying for access or paying for momentum. Those are different jobs. Only one of them survives a quiet month.
Access is a tool. Momentum is a mood. The fund will sell you both until you notice the difference.
The Network Bill That Still Has to Be Paid
Strip the ticker off for a minute. Zcash still has to produce blocks, still has to price fees, still has to decide how much of each transaction the outside world can see. NU7’s sustainability mechanism is an attempt to point some fee income at future rewards so the security budget does not depend only on issuance declining on a schedule. Whether that works depends on people actually paying fees, which depends on people actually using the chain. An ETF does not use the chain. It warehouses the coin. Warehousing can support price. It does not, by itself, produce fee flow.
That gap is easy to ignore while assets are rising and painful to ignore when they are not. A fund at $751 million is a large holder relative to daily on-chain activity for a privacy coin. Large holders who do not transact do not feed the fee redirect. They sit. Sitting is allowed. It is just not the same thing as adoption, and adoption is what a sustainability mechanism quietly assumes. I like the honesty of building the mechanism anyway. Hope is not a fee schedule, but neither is pretending issuance lasts forever.
Shielded Spam Limits Are a Quiet Part of the Upgrade
Faster blocks are the headline. The spam limits on shielded transactions are the part operators will feel if they are wrong. Privacy systems are expensive to verify. An attacker who can cheaply stuff the shielded pool can raise costs for everyone else without stealing funds. Caps and pricing are how networks push that cost back onto the sender. Getting the cap wrong means either a clogged pool or a pool nobody can afford to use. Testnet is where that argument is supposed to happen, in the open, before November.
Fund shareholders will not vote on the cap. Miners, validators in the relevant sense, wallet teams, and the people who actually send shielded transactions will live with it. The share price may still twitch on the headlines. Twitching is not governance. If you own the wrapper, you are outsourcing that argument to strangers and hoping they land it. That is fine if you know you are outsourcing it. It is less fine if you thought the ticker was the protocol.
A Practical Way to Watch the Next Two Weeks
You do not need a terminal farm. Four checks cover the live questions.
- Daily net flow on the Zcash product, especially whether another $20 million-plus redemption day appears without a fresh price break.
- ZEC versus the $1,300 area and the broken $1,500 area, as zones rather than as prophecy.
- Whether perpetual open interest stabilizes near the mid-September shrinkage or rebuilds on the bounce.
- Testnet behavior after the October 6 target, then whatever the October 20 activation decision actually says.
If flows stabilize and the upgrade clock holds, this week becomes a footnote under a rally that got ahead of itself. If flows keep leaking and the upgrade slips, the footnote becomes the chapter. I cannot tell you which, and anyone who can is selling something. What I can tell you is that the furniture is now visible. The first red week has a number. The split has a filing. The upgrade has a block height. Use those, not the mood of the last screenshot.
Where the Reasonable Disagreement Lives
Reasonable people can read the same $93.56 million and land in different places. One camp sees a healthy washout after a doubling, a fund that is still far larger than at conversion, and a protocol week that might matter more than a redemption week. Another camp sees hot money that used a new listing as a trading vehicle, a sponsor-family creation that flattered September, and a coin that could not hold $1,500 once leverage left. I lean toward the first camp on the product and the second camp on the September price. The product did its job. The price did what vertical prices do.
You can disagree without inventing a conspiracy. No special share class was granted to the September 8 creation. The split did not skim value. The outflow did not, on the public numbers, erase the life-to-date inflow. The token did fall hard from the high. All of that can sit in one paragraph if you let it. The urge to pick a hero and a villain is the urge that makes market writing worse. Resist it for one cycle and the chart gets easier to see.
What Holders Can Control, and What They Cannot
You cannot control the next creation basket. You cannot control whether an authorized participant sells redeemed coins or warehouses them. You cannot control the October 20 activation vote, or whether testnet finds a bug that pushes November. You can control whether your position size assumed September would repeat. You can control whether you know your cost basis in post-split shares, because three-for-one arithmetic trips people who track lots by share count instead of by dollars. You can control whether you are staring at the fund’s asset headline or at the coin you actually have a claim on.
A small operational point that bites after splits: alerts set at the old price are now nonsense. A $100 alert on a share that now trades in the thirties will never fire, or it will fire for the wrong reason if you forgot to adjust. Reset the levels. Reset the position size in shares. Leave the thesis, if you still have one, in dollars and in coins. The quote is a costume.
Tax lots are the other costume. A split is generally not a sale, but redemptions and open-market exits are. Anyone who used the heavy days to leave has a realized event, win or loss, that the weekly flow print does not itemize. That is between the holder and their records. The fund does not know your basis. The chart does not either.
The Longer Arc Under a Single Red Week
Step back and the week is one tile. Privacy coins spent years outside the brokerage mainstream. A converted trust on a major exchange is a real change in who can hold the exposure, even if the first holders turn out to be flighty. Flightiness is information. It says the early base includes tourists. Tourists leave. Sometimes a resident base remains, smaller and less exciting, which is how a lot of listed products actually survive. Sometimes the tourists were the base, and assets drift toward the coin’s pre-listing reality. October does not decide that. A quarter of flow data might.
I keep a soft bias here, and I will label it. Products that exist only because a rally made them look brilliant tend to shrink to the size of the non-rally demand. Products that exist because a real account segment wanted the exposure tend to find a floor above the launch print. ZCSH has already shown it can clear $1 billion in a hot tape and hold roughly $751 million after a cold week. The floor, if there is one, is somewhere under that second number and above the $304 million open. Finding it will be dull. Dull is where position sizing gets easier.
Between here and that floor, the protocol still has to ship NU7 or explain why it did not. Faster blocks and a fee redirect will not refill an ETF. They might change the reason a long-term holder gives for staying. Reasons matter less than flows on a Tuesday. Over a year they are the flows. That is the only timescale on which a sustainability mechanism and a brokerage product are even talking about the same asset.
A Clean Close Without a Prediction
So the week ended October 2 did what first red weeks do. It punctured the idea that inflows are a feature of the product rather than a feature of the tape. ZCSH recorded $93.56 million in net outflows, assets landed near $751 million, and cumulative net inflows stayed positive around $212.56 million. ZEC closed the next session near $1,304 after a slide of about a fifth from the September 26 close. The share split on September 30 tripled the share count and cut NAV per share from $111.41 to $37.14 without changing what a holder owned. A roughly $100 million related creation from early September remained part of the backdrop, not a hidden preference. And a network upgrade aimed at 25-second blocks moved onto a testnet calendar while all of this was happening.
If you need a single sentence for the group chat, use this one. The pipe that filled the Zcash fund in September proved it can empty just as quickly, and the coin was already on its way down before the biggest redemption days printed. Everything else is detail. Useful detail, if you are still in the trade. Noise, if you were only there for the vertical part.
I will be watching the next creation print more closely than the next price target. Price tells you how the week felt. Flows tell you whether the new holders meant it. After a $93.6 million exit, that distinction is the whole game.