
Have you ever watched a factory floor go quiet, then suddenly roar back to life because a political meeting is on the calendar? That is roughly what happened in China this month. American buyers did not wait for a handshake photo. They placed orders first. I have covered trade cycles long enough to know that companies rarely get sentimental about summits. They get tactical. And this time the tactic was simple: lock in Chinese goods while the window still looks open.
Why US Orders Jumped Before The Leaders Met
A private survey of more than a thousand Chinese firms picked up something odd in early September. Orders from the United States flipped from weak to clearly positive. Not a gentle bounce. A swing. The gauge that tracks how many companies saw more US demand versus fewer US demand jumped into double digits after sitting near the floor a year earlier. Month to month, the same measure also improved. That combination is rare. Usually one of those two readings lags.
Here is the part that matters for anyone watching global markets. Overall Chinese orders, both domestic and export, were still softer than last year. New orders even cooled compared with August. So this was not a broad boom. It was a targeted rush from American importers. In my experience, that pattern shows up when buyers fear a policy change more than they fear inventory. They would rather sit on extra boxes than get caught on the wrong side of a tariff headline.
Companies do not order from a press conference. They order from a risk calendar.
The timing was not subtle. The two presidents were due in Washington for a high-profile visit, the first state-level trip of its kind in more than a decade. Markets had already priced a decent chance that both sides would avoid another escalation. That expectation, messy as it is, is enough to move a purchase order. A container ship does not care about speeches. It cares about the fee at the dock and the duty at customs.
What The Survey Number Actually Means
Diffusion indexes can look abstract. Think of them as a show of hands. Ask a room of factory managers whether US orders rose or fell. Subtract the bears from the bulls. When the result goes from negative to plus thirteen, you are not looking at one lucky exporter. You are looking at a shift in mood across a wide sample. The firms were questioned through most of September, which is exactly the stretch when logistics teams lock holiday and first-quarter inventory.
Still, I would not call this a renaissance. Domestic demand inside China did not suddenly heal. Other export destinations did not all light up at once. The United States was the outlier. That is useful. It tells you the driver was bilateral, not a global restocking wave. If Europe, Southeast Asia, and Latin America had moved in lockstep, I would be talking about a different story. They did not.
Perhaps the most interesting aspect is how quickly relative tariff math can change behavior. When buyers believe China’s position versus other suppliers has improved, even a little, they pull demand forward. They do not need a permanent deal. They need ninety days of predictability. That is a short leash. It is also how modern supply chains actually work.
The Trade Truce That Bought Breathing Room
Both governments agreed to stretch an existing pause by two months, into January. Tariffs stay lower than the threatened peak. Limits on certain strategic mineral shipments stay on hold. Extra port charges on vessels stay in the freezer. None of that is a peace treaty. It is a stay of execution. Markets treated it as such, which is why the order books moved before the cameras started rolling.
Washington also appeared ready to delay another tariff package tied to industrial overcapacity until after the meeting. That delay, even if temporary, reduces the odds of a surprise levy landing on a container already at sea. Importers hate mid-voyage policy. Factories hate it more. A two-month extension is not elegant diplomacy. It is usable diplomacy.
- Lower-than-threatened duties remain in place for now
- Export controls on key minerals stay paused
- Higher port fees on ships stay suspended
- A further tariff wave tied to overcapacity looks delayed
Do not get romantic about the effective rate. Duties on Chinese goods still sit far above what the United States charges most other large partners. Around the low twenties in percentage terms is not free trade. It is managed friction. Companies can live with managed friction. They struggle with surprise friction. That distinction explains almost every restocking spike of the past few years.
Ports Told The Same Story Before The Speeches
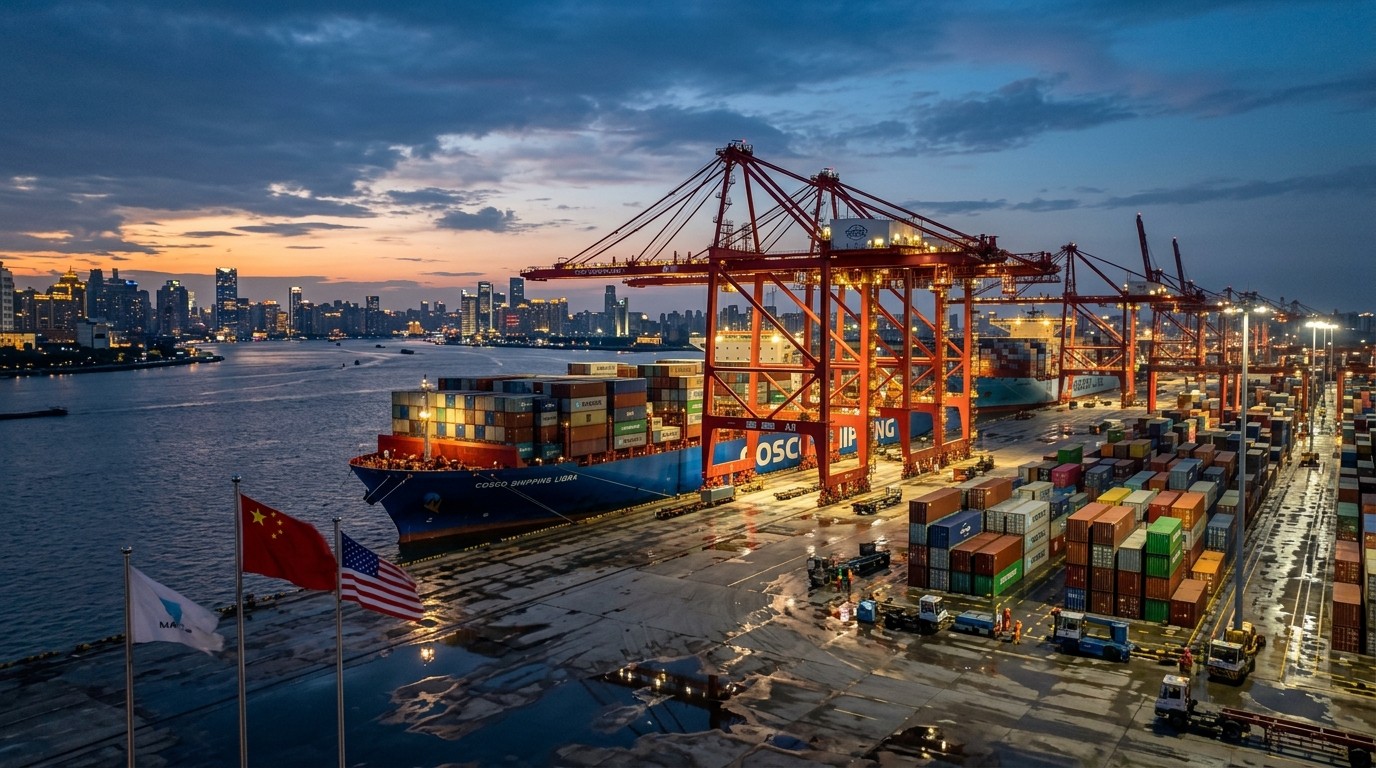
Official traffic data lined up with the private survey. Chinese ports logged one of their busiest weeks on record in the run-up to the talks. You can argue about survey design. You cannot easily argue with crane hours and berth occupancy. When yards fill and ships stack outside the channel, somebody is shipping product. A lot of it was pointed at the Pacific.
I have found that port prints often lead the official customs numbers by a few weeks. Customs is tidy. Ports are messy and immediate. If you only wait for the monthly trade balance, you miss the scramble. This scramble had a political timestamp on it. That does not make the goods imaginary. It makes the timing political.
Is some of this pull-forward demand that will vanish in October? Probably. Buyers who feared a breakdown in talks will sit on inventory if the relationship holds. That is the quiet risk under the bullish chart. A surprise jump today can become a hole in the order book later. Trade data is lumpy for a reason.
Why Stability Odds Rose After The Extension
Political risk shops lifted their probability of continued calm in the bilateral relationship to the highest reading since the current US administration returned. That is a mouthful. Translated into plain language: fewer people in the forecasting business expect an immediate blow-up. The extension was shorter than some hoped. Even so, analysts argued it was unlikely to restart a spiral on its own.
Neither government has an obvious incentive to light the fuse again in the next few weeks.
That line is doing a lot of work. Incentives change. Elections, factory layoffs, and security incidents can rewrite the script overnight. For now, both capitals appear to prefer a tense ceasefire over a fresh round of tit-for-tat measures. I tend to agree with that read, with one caveat. A ceasefire that lasts into January still leaves a cliff. Markets love cliffs until they have to walk up to one.
Washington will likely press for faster licensing of mineral shipments that US manufacturers actually need. It will also want larger purchases of American farm goods. Beijing, for its part, will want the current pause on certain security-related sales across the Taiwan Strait to remain in place. None of those asks is new. The packaging is what changes after a summit.
What Each Side Is Quietly Asking For
Trade talks always look like one ledger. They are usually two or three ledgers stacked together. Goods, technology, and security sit in different columns and still get traded against each other. That is uncomfortable for purists. It is normal for practitioners.
- US buyers and officials want predictable access to critical minerals
- Farm states want purchase commitments that show up in actual shipments
- Chinese exporters want the tariff pause to survive the next news cycle
- Beijing wants fewer surprises on security sales and port charges
If those four items stay in rough balance, the order rebound can persist for a quarter. If one item breaks, the rebound becomes a one-month spike. I wish the mapping were cleaner. It is not. Anyone selling a simple scorecard for this relationship is selling comfort, not analysis.
The Calendar After Washington
The two leaders are expected to cross paths again at a regional gathering in Shenzhen in November. There is also talk of a possible sideline meeting when a major leaders forum takes place in Miami in December. Nothing after this week is locked. That uncertainty is not a footnote. It is the operating environment.
Companies that booked extra freight in September will watch those dates the way traders watch payroll Friday. A confirmed follow-up meeting supports the idea that both sides want a process, not a rupture. A cancelled encounter would tell a different story. Process is dull. Process is also how tariffs stay paused.
I’ve found that markets overreact to the first handshake and underreact to the scheduling of the second. The first event is theater. The second event is logistics. If you care about factory utilization in Guangdong or inventory at a Midwest warehouse, logistics wins.
Tariffs Are Still High, And That Shapes Every Decision
It is easy to celebrate a jump in orders and forget the baseline. Chinese goods entering the United States still face an effective levy far above the average applied to other major partners. That gap changes sourcing math. Some categories cannot leave China quickly. Electronics components, certain machinery, and a long list of consumer goods still run through Chinese plants because the alternative is slower, costlier, or both.
Other categories have already moved. Footwear, some furniture, and assorted low-margin items shifted years ago toward neighbors. The September rebound does not reverse that shift. It tells you the remaining China-centric categories are sensitive to political weather. When the weather looks milder, orders return. When it looks stormy, they vanish or reroute.
| Signal | What It Showed | How Durable |
| US order gauge | Sharp swing into positive territory | Medium if truce holds |
| Overall China orders | Still below last year | Weak backdrop |
| Port activity | Record-busy week before talks | May fade after pull-forward |
| Tariff pause | Extended into January | Political, not structural |
| Effective US duty | Still well above peer average | High and sticky |
Read that table twice. The bullish cells sit next to cautious ones on purpose. A serious reader should hold both ideas at once. Demand from America improved. The broader Chinese order book did not heal. Policy bought time. Policy did not rewrite the tariff schedule.
How Importers Actually Behaved In September
Talk to enough purchasing managers and you hear the same sequence. First they hedge with earlier bookings. Then they split orders across two ports. Then they add a small buffer of safety stock. None of that requires a forecast of eternal friendship. It requires a belief that November will not be worse than September.
Some firms also used the window to test whether Chinese suppliers would still prioritize US accounts after years of friction. Relationships on the factory side get strained when policy whipsaws. A burst of orders is one way to stay at the front of the production queue. That sounds cold. It is how long-term vendors keep capacity reserved.
Was every extra container a bet on peace? Of course not. Holiday shelves still need filling. Retail calendars do not pause for geopolitics. Mix the seasonal restock with a political option and you get a number that looks like a surprise. It is a surprise only if you ignored the calendar.
The Fragile Core Of Strategic Stability
Officials on both sides have started using a softer phrase: strategic stability. It is a polite way of saying we will compete without kicking over the table this quarter. I like the phrase more than I trust it. Stability that depends on personal chemistry between two leaders is not institutional stability. It is weather.
That said, weather can last a season. If licensing for mineral exports speeds up, US manufacturers in autos, electronics, and defense-adjacent supply chains get relief. If farm purchases rise in a measurable way, political support for the pause gets a little thicker in agricultural districts. Those are not grand bargains. They are ballast.
Ballast does not make a ship fast. It keeps the ship from rolling over in a swell.
Investors who treat every summit as a regime change will keep getting whipsawed. Investors who treat every summit as a chance to roll a three-month hedge will sleep better. I lean toward the second camp. Not because I am cynical. Because the last decade trained all of us to expect pauses, not endings.
What This Means For Factories Inside China
A jump in US tickets helps utilization. It does not fix weak local consumption. Many plants have been running below the pace they enjoyed before the latest tariff cycle. Export work from America can fill a line for a few weeks. It cannot replace a soft housing market or cautious households at home.
Exporters in the Pearl River Delta will take the orders anyway. Cash flow is cash flow. The smarter operators will avoid hiring as if the boom is permanent. Temporary labor, extra shifts, and subcontracted finishing work are the usual tools. That flexibility is one reason Chinese industry can still sprint when a political window opens.
There is a less comfortable implication. If the rebound is mostly American, then Chinese firms remain exposed to a single policy relationship. Diversification speeches are easy. Diversification of actual invoices is slow. September showed both the benefit and the concentration risk in one print.
What This Means For US Companies And Prices
American importers who moved early may enjoy slightly better availability and fewer last-minute air-freight panics. That can cap some goods inflation at the margin. It will not reverse a multi-year shift in landed costs. Tariffs are still sitting on the invoice. Freight rates can still jump if too many ships chase the same berth.
Retailers will talk about stability. Procurement teams will talk about dual sourcing. Both can be true. Dual sourcing is expensive. Stability is cheaper until it ends. The firms that look most adult right now are the ones that booked China volume and kept an alternative plant warm in another country. Redundant capacity feels wasteful in a calm month. It feels cheap in a crisis month.
In my view, the consumer will not notice this particular rebound unless it fails. Empty shelves make news. Full shelves do not. The market story is in the options, the freight futures, and the factory surveys. The household story is quieter, which is usually a good sign.
Risks That Could Wipe Out The September Bounce
Let us be blunt. Several things could turn this into a one-off.
- A sudden breakdown in mineral licensing
- A new tariff list aimed at sectors already running hot
- A security incident that forces both capitals to look tough
- A sharp drop in US retail demand after the holidays
- A decision to let the January deadline expire without a plan
Any one of those can freeze new orders even if ships already at sea keep moving. Trade is a flow. Policy is a gate. When the gate looks like it might close, the flow bunches up on the near side. That bunching is what you just saw. Bunching is not the same as a new trend.
Could the opposite happen? Sure. A clearer agricultural purchase plan plus smoother mineral licenses would encourage another restock in the fourth quarter. I would not bet the house on that path. I would not ignore it either. The distribution of outcomes is wider than the headline about a “surprise jump” suggests.
How To Read The Next Few Data Prints
Watch three things, in order. First, whether US-bound orders stay positive after the cameras leave. Second, whether port congestion fades or simply shifts to a different hub. Third, whether official customs figures confirm the survey with a lag. If all three stay constructive into November, the pull-forward story gets weaker and the demand story gets stronger.
If only the first month looks good, treat September as a positioning trade by corporate treasuries and procurement desks. That is still useful information. Positioning trades move currencies, freight, and selected industrial stocks. They just do not rebuild an entire export model.
Simple checklist for the next quarter:
  Confirm follow-up leader meetings
  Track mineral license speed
  Watch farm shipment volumes
  Compare US orders versus other destinations
  Revisit the January truce date before it arrives
None of that requires a secret model. It requires a calendar and a refusal to treat one survey as destiny. I wish more market notes worked that way. Many still prefer a single number and a dramatic verb.
A Note On Narrative Versus Freight
Summits generate narrative. Ports generate tonnage. When the two line up, commentators declare a turning point. Sometimes they are right. Often they are early. The healthier habit is to separate the photo from the bill of lading. The photo tells you the mood in the room. The bill of lading tells you whether a sofa, a server rack, or a pallet of auto parts actually moved.
This month, mood and tonnage moved together. That is why the survey felt surprising. It should not have been shocking to anyone who has watched importers race a deadline. People are pattern-seeking animals. Corporate buyers are deadline-seeking animals. Give them a political deadline and they will behave like students the night before an exam. They cram.
Will they cram again before January? If the extension remains the only bridge, yes. If a thicker set of working groups appears after the next regional meeting, maybe less so. Process reduces cramming. The absence of process guarantees it.
The Bigger Picture For Global Markets
For equity investors, a calmer bilateral channel supports risk appetite in trade-sensitive names. For credit investors, it reduces the odds of a sudden hit to exporter cash flow. For currency desks, it can take a little heat out of safe-haven demand. None of those effects is guaranteed. All of them are plausible if the pause holds through year-end.
The more interesting market angle is relative. If Chinese goods keep flowing to the United States while other destinations stay soft, you get a lopsided recovery. That lopsidedness shows up in shipping routes, in container lease rates on the trans-Pacific lane, and in the earnings mix of logistics firms. Watch the lane, not just the country.
I keep coming back to a simple idea. Policy uncertainty is a tax. A temporary truce is a rebate. Rebates change behavior quickly. Taxes, once baked into contracts, change behavior slowly. September was a rebate month. January will tell you whether the rebate gets renewed.
Practical Takeaways Without The Spin
If you run a supply chain, do not treat this bounce as permission to concentrate everything in one origin country. Use the window to rebuild buffer stock in the items that truly cannot move elsewhere. Keep the dual-source work going in parallel. The political weather can change faster than a tooling line.
If you invest, separate the trade-sensitive rally from the domestic China story. They are not the same trade. Export prints can look fine while local demand still limps. Mixing those two into one bullish paragraph is how people overpay.
If you simply follow the news, remember that “surprise” is often a function of inattention. The summit date was public. The truce clock was public. The incentive to ship early was obvious. The survey made the obvious measurable. That is still valuable. Measurement is not the same as magic.
And if you want a single sentence to carry out of this piece, use this one. American companies ordered more from China because they thought the next few months would be less hostile than the last few years, not because the structural fight disappeared. Hold that sentence when the next headline arrives. You will need it.
Where The Story Goes From Here
The next chapter is not another survey. It is whether working-level teams can turn a two-month pause into a set of boring, repeatable approvals. Licenses. Purchase schedules. Port rules that do not change on a Friday night. Boring is the bull case. Drama is the bear case. I know which one supply-chain managers prefer.
There will be another meeting, or there will not. There will be another extension, or there will be a lapse. In the gap between those outcomes, factories will keep doing what they did this month. They will watch the political calendar and they will ship when the calendar looks friendly. That is not ideology. That is inventory management with a passport.
So yes, the jump in US orders was real enough to show up in both a wide company sample and in crowded berths. No, it does not settle the contest between the world’s two largest economies. It tells you that when leaders schedule a conversation, companies schedule a sailing. Sometimes the most human detail in a geopolitical story is a purchase order with an earlier date than usual. That is the detail I will keep watching, long after the flags come down from the guest residence.