
Have you ever looked at a wind turbine, an electric motor, or a missile guidance system and wondered where the magnets actually come from? Most people never do. Then a company files paperwork in Greenland, a security pact hits the headlines, and suddenly the map of the Arctic looks less like a postcard and more like a procurement chart. That is the mood around Sarfartoq right now, and it is worth sitting with for a minute before the talking points take over.
Why This Greenland Filing Landed With Such Force
A few days after a security agreement involving the United States, Greenland, and Denmark, a North Carolina-based developer applied to enlarge its rare earth district in southwest Greenland. The existing ground covers about 74 square miles. The request would lift that footprint to roughly 175 square miles if regulators say yes. On paper that is a mapping exercise. In practice it is an attempt to treat one carbonatite complex as a whole district rather than a single pit with a hopeful satellite zone.
I have found that mining stories often get flattened into two slogans: either “the West is finally breaking free” or “nothing will ever move in the Arctic.” Reality sits in the slushy middle. Licenses can expand. Ore can stay in the ground. Processing can still sit thousands of miles away. All three can be true in the same quarter.
What The Company Says It Is Building
The project is aimed at neodymium and praseodymium, the pair that feeds high-performance permanent magnets. Those magnets show up in electric vehicles, many wind turbines, and a long list of defense systems that nobody wants to discuss in a press release and everybody still needs. Company language frames Sarfartoq as a district-scale build, not a boutique deposit. That phrasing matters. District scale is how you justify roads, power, a port plan, and years of drilling that would look reckless on a postage-stamp license.
This application is about building Sarfartoq at district scale.
– Company president, public statement
There is an open-pit concept and an underground concept on the same site. Early internal valuation talk has put material in the neighborhood of $2.05 billion. Treat that figure the way you treat any early number in a remote jurisdiction: useful as a headline, not as a bankable cash-flow model. Grades move. Recovery rates disappoint. Capex has a habit of growing in cold weather.
The China Problem Nobody Can Wish Away
Processors based in China still handle at least three quarters of the global market for rare earth elements as a group. That is the stubborn fact underneath every Western mine ribbon-cutting. You can dig rock in Greenland, Australia, or the United States and still send concentrate into a chemical maze that is concentrated in one country. Export curbs over the past year pushed prices around and reminded buyers that policy risk is not a footnote.
The developer argues the project could supply about one third of the world’s neodymium-praseodymium oxide refined outside China. If that lands, it is meaningful. If the oxide still needs Chinese separation capacity for part of the flow, the headline shrinks. In my experience, investors hear “outside China” and stop listening at the comma. The comma is where the project either becomes strategic or stays promotional.
- Magnet metals for motors and generators
- Defense-grade permanent magnets
- A claimed share of non-Chinese NdPr oxide
- A larger exploration box around known carbonatite
What The Security Agreement Changes On The Ground
The political wrapper is almost as important as the geology. After the pact, the U.S. side said no adversary should make sensitive investments in Greenland without express written approval. That is screening language. Screening does not pour concrete. It does change who can sit at the table when a deposit looks commercial.
Greenland holds some of the largest undeveloped rare earth packages in the Western world. That sentence has been true for years. What was missing was a clearer rule about rival capital. A framework that pushes adversarial money off the island makes those tonnes look more available to allied plants, at least on a slide deck. Whether local politics, environmental review, and infrastructure keep pace is another story, and it is usually the longer one.
Perhaps the most interesting aspect is timing. The license application arrived days after the security news, not months later after a quiet winter of mapping. Markets noticed. Critical metals names jumped on the deal chatter. Greenland-linked shares firmed when trading opened. That is not proof of a mine. It is proof that traders can draw a straight line from a communique to a ticker in under a session.
Sarfartoq On The Map, Not Just In A Release
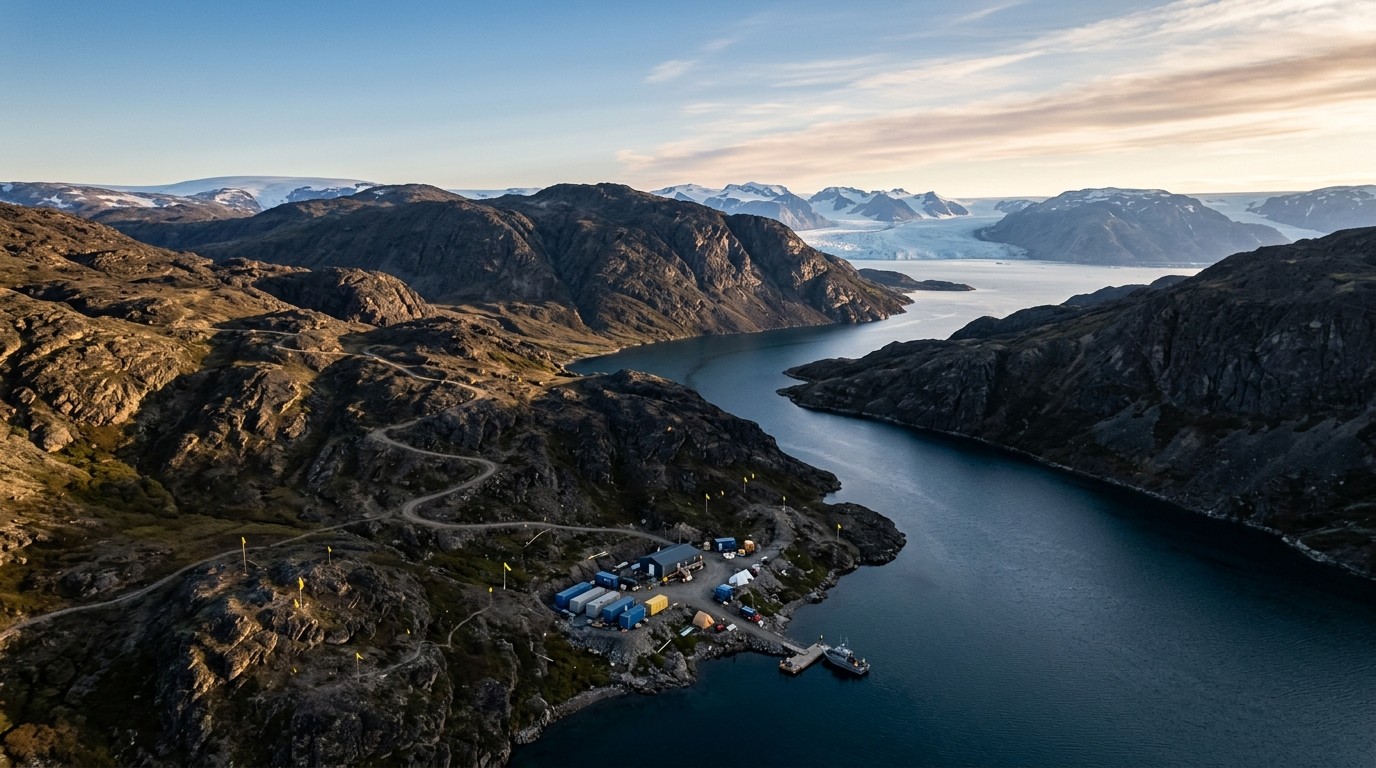
The current exploration license, often sketched in yellow on company maps, hosts the Sarfartoq Carbonatite Complex, the ST1 neodymium-praseodymium deposit, and several less-developed rare earth zones. The new eastern application is typically shown in red. If you have stared at enough junior maps, you know the color code: yellow is what you already have, red is what you want before the next financing.
Carbonatite systems can be generous and messy at the same time. They can host attractive NdPr ratios and still fight you on radioactive elements, waste rock, and water. Southwest Greenland is not a suburban industrial park. Weather windows are short. Logistics run through a thin set of ports and airfields. Labor is not infinite. Those constraints do not kill a project. They price it.
Other Bets On The Same Island
Sarfartoq is not the only name in the conversation. A privately held Texas firm, Greenland Energy, has rights tied to drilling on the Jameson oil and gas project in the Jameson Land Basin on the east coast. The group, formed in 2025, started moving drilling kit toward Greenland in late July. That is a different commodity and a different coastline, but it feeds the same narrative: the island is no longer treated as a frozen museum.
Critical Metals Corp. is advancing the Tanbreez rare earth project in southern Greenland. That deposit is frequently described as one of the world’s larger packages with a notable share of heavy rare earths. Heavy elements matter because they are scarcer in many light-rare-earth-dominant systems and they show up in specialized magnet and defense chemistries. The same company has talked about a Romanian plant expected to handle about 28,000 tons a year of rare earth and critical metal products, including some 26,000 tons of high-purity silicon dioxide powder used across food, pharma, paints, plastics, rubber, ceramics, and electronics.
See the pattern? Mines in Greenland, midstream somewhere in Europe or North America, end markets everywhere. The chain only works if each link is financed, permitted, and staffed. Miss one and the ore sits pretty in a resource table.
| Project | Focus | Stage Signal |
| Sarfartoq | NdPr magnet metals | License expansion filing |
| Tanbreez | Heavy rare earths | Development track |
| Jameson | Oil and gas | Equipment mobilization |
Why Magnet Metals Became A Policy File
Permanent magnets are small objects with outsized leverage. A traction motor does not care about your press conference. It cares about the alloy. Wind OEMs care about delivery dates. Defense buyers care about trusted origin. When one country dominates separation and metal-making, every other country discovers that geology was never the scarce input. Chemistry and industrial policy were.
Washington has spent recent years talking up domestic rare earth plants and offtakes. Fair enough. Plants still need feed. That is the gap Greenland developers keep pointing at. Ore first, then a Western crack in the midstream, then magnets that do not depend on a single customs regime. Easy to write. Hard to schedule.
I’ve watched similar cycles in lithium and nickel. The first wave is resource pride. The second wave is processing sticker shock. The third wave is a quieter argument about who actually owns the refinery. Rare earths are further along that path than casual readers think, and further behind than patriotic slideshows admit.
Prices, Restrictions, And The Mood In The Pit
Chinese export restrictions on rare earths helped lift prices over the past year. Higher prices make remote deposits look less crazy. They also invite more juniors onto the same stage, which dilutes attention and, sometimes, capital. A doubled license in Greenland will not, by itself, reset the price deck. It can, however, change how offtakers rank their optionality.
Think of offtake the way a relationship counselor might talk about exclusivity. You want a partner who shows up when the market is ugly, not only when the photo is flattering. Magnet makers and auto groups have learned that lesson the expensive way. A district-scale box in southwest Greenland is a way to say: we can be that partner if the permits hold.
Permits, People, And The Unromantic Work
Approval is not a ceremony. It is a stack of environmental studies, community consultation, and technical reviews. Greenland has every right to move slowly. The island lives with the aftermath of projects long after the commodity cycle has moved on. Anyone who treats local review as a nuisance has not spent time in a place where a mine can dominate a town’s entire labor market.
- Confirm the larger license outline and work program.
- Keep drilling the known zones and the eastern ground.
- Lock a realistic path from concentrate to separated oxide.
- Match infrastructure spend to a climate that does not forgive sloppy calendars.
None of that fits in a one-line alert. It is still the work that decides whether 175 square miles is an asset or a brochure.
How Markets Read An Arctic Headline
Monday’s bounce in critical metals names was classic event trading. A security pact plus a mine-expansion headline is catnip. The danger is confusing a rerating with a construction schedule. Shares can rally on optionality. Cash flow arrives, if it arrives, after years of studies, winter shutdowns, and procurement fights over mills and reagents.
If you follow these names, separate three clocks. The political clock runs in days. The exploration clock runs in seasons. The project-finance clock runs in years. Mix them up and you will overpay for a map and underweight a balance sheet.
Greenland hosts some of the largest known undeveloped rare earth deposits in the Western world, and a framework that screens adversary capital out of the island makes those deposits more clearly available to allied supply chains.
That is the bull case in one breath. The bear case is quieter: screening capital is not the same as attracting it, and attracting it is not the same as pouring a foundation in a place where darkness and ice set the work roster.
What “District Scale” Really Asks Of Investors
District scale sounds impressive because it is. It also implies a larger environmental footprint, more stakeholders, and a bigger check. You do not double ground because you are bored. You do it because the carbonatite and the satellite showings suggest a camp, and camps are how you keep a story alive through two financing winters.
Ask simple questions. What share of the value sits in ST1 versus the less-drilled zones? What is the radioactive penalty in the flowsheet? Who buys the oxide, in which currency, and under which origin rules? How much of the midstream is contracted rather than hoped for? Those questions are dull. They are also how you avoid owning a slogan.
Defense, Energy, And The Shared Shopping List
Electric vehicles and wind turbines get the consumer-facing ink. Defense systems sit in the same shopping cart more often than public debate admits. High-performance magnets do not change chemistry because the end user wears a different badge. That overlap is why a Greenland filing can move both clean-tech tickers and names that live in the security bucket.
It also explains the screening language. If an adversary can take a quiet stake in the ground under a magnet feed, the political problem shows up later as a procurement problem. Written approval is a blunt tool. Blunt tools are what governments reach for when supply maps look lopsided.
A Note On Hype Without The Eye Roll
I try not to sneer at Arctic optimism. Some of it is earned. The rock is real. The policy window is more open than it was a decade ago. Buyers are less naive about single-country midstream risk. That combination can support a mine. It cannot repeal physics or local consent.
So keep the enthusiasm, just put it on a leash. Celebrate a larger license application as a step. Do not file it under “problem solved.” The West still needs separated oxide, metal, alloy, and magnet plants that run when politics gets loud. Greenland can feed that chain. It cannot be the whole chain.
Practical Takeaways If You Follow The Sector
Watch the license decision more than the first-day tape. Watch drill meters in the new eastern ground. Watch any offtake that names a plant you can actually find on a map. Watch capex language for winter extras that were missing in the first brochure. And watch whether rival capital is truly boxed out, or merely asked to wear a different hat.
What moved the story:
  Security screening language
  A doubled exploration outline
  Magnet-metal scarcity outside one dominant midstream
What still has to move:
  Permits
  Processing contracts
  Arctic logistics that survive a bad season
Is this the week Western magnet supply got fixed? No. Is it a week when the map, the politics, and the ticker lined up in a way that is hard to ignore? Yes. Those two answers can live in the same paragraph. Grown-up coverage should let them.
The Long View From A Cold Coast
Stand back from the filing date and the story looks older than the headline. Resource nationalism, energy transition hardware, and defense industrial policy have been walking toward the same intersection for years. Greenland happens to sit on a pile of rock that matches the shopping list. A security pact makes the pile easier to discuss in allied conference rooms. A larger license makes the pile easier to drill as one camp instead of a scatter of hopes.
Whether that becomes tonnes of oxide is a slower plot. I would rather read that plot than another victory lap. The interesting part is not that a company asked for more ground. The interesting part is whether the next three winters turn that ground into feed a magnet plant can trust when the next restriction lands.
Until then, treat Sarfartoq as what it is today: a serious deposit in a serious place, wrapped in better political weather than it used to enjoy, still facing the same unglamorous work that every remote mine faces when the cameras leave. That is not a letdown. It is the job.