
I still remember the month a client of mine tried to close the books from a tangle of notes, email threads, and a spreadsheet that had more colors than a traffic light. Nothing was “wrong,” exactly. The business was simply bigger than the method. Revenue had crept up. Refunds showed up late. One contractor invoice sat unpaid because nobody could find the original quote. That is usually the moment people start hunting for free accounting software, not because they suddenly love bookkeeping, but because guessing at cash flow gets expensive.
Plenty of owners begin with pen and paper or a shared sheet. That can work when you have a handful of sales a month. It starts to wobble when customers pay on different timelines, expenses pile up in categories you never named, and tax season turns into a scavenger hunt. Free tools can bridge that gap if you know what they actually include. The catch is simple. Free rarely means unlimited. The useful question is not “Is there a no-cost option?” It is “Will this option still tell me the truth about my business six months from now?”
What Separates A Useful Free Plan From A Pretty Demo
In my experience, people get dazzled by a clean dashboard and forget to test the boring parts. Can you connect a bank? How many invoices can you send? What happens when a second person needs access? Those limits decide whether the software is a real system or a teaser. I would rather see a modest feature list that works every day than a long menu that locks the moment you need it.
Recent small-business surveys keep repeating the same pattern. More than half of owners still track money in spreadsheets. A sizable group still uses paper. Efficiency is the reason most of them eventually switch. That tracks with what I hear in conversations. Nobody wakes up craving another login. They want fewer mistakes and a faster answer to “Are we actually making money?”
If a free plan cannot show income, expenses, and outstanding invoices in one place, it is not accounting software. It is a form with a logo.
Income And Expense Tracking Comes First
Start here, because everything else hangs on it. You need a clear record of money in and money out, tagged in a way you will still understand in April. Look for simple categories, a way to split mixed charges, and a feed from at least one business bank account. Manual entry is fine for a quiet month. It becomes a liability when card swipes multiply.
Automatic import does not make you a better owner by magic. It just removes typing errors. I have found that even one linked account changes behavior. People stop “meaning to enter that later.” The transaction is already sitting there, waiting for a category. That small nudge is how messy books get cleaner without a lecture.
- Connect the account you actually use for the business, not a personal catch-all if you can avoid it.
- Review imported lines weekly, not at month-end when memory is gone.
- Keep category names short and consistent so reports stay readable.
- Flag transfers between your own accounts so they do not look like income.
A free plan that only lets you link one institution can still be enough for a solo shop. Just be honest about how you bank. If you bounce between two cards and a payment app, one connection will leave holes. Those holes show up later as mystery gaps in profit.
Invoicing And Getting Paid Without Chasing People All Week
Late payments are not a personality flaw in your clients. They are a process problem. If creating an invoice takes twenty minutes and the follow-up lives in your head, cash arrives late. Free software should let you send a clean invoice, see whether it was viewed or paid, and accept an online payment without building a separate checkout page.
Count the invoices. That sounds petty until you hit the cap on the 12th of the month. Some no-cost products allow one estimate and a couple of invoices. Others open the tap if you turn on their payment tool. Processing fees are the trade. Card and wallet payments often sit near three percent. Bank transfers usually cost less. Neither is “free money movement,” and pretending otherwise is how people get surprised.
Ask a blunt question. How many paying customers do you bill in a typical month? If the answer is already higher than the free cap, do not sign up hoping you will “send fewer invoices.” You will not. You will either upgrade or sneak work back into a document tool, which defeats the point.
| Need | Why it matters | Free-plan watch-out |
| Custom invoice | Looks professional and matches your terms | Logo or field limits |
| Payment link | Shortens the time from send to cash | Processing fees |
| Status tracking | Stops you from double-chasing | May be missing on tiny plans |
| Reminders | Recovers money without awkward texts | Often capped or manual |
I’ve seen owners treat invoicing as a design project. Fonts, colors, a clever footer. Fine. The report that actually pays rent is “who still owes me, and since when.” If the free product cannot answer that in two clicks, keep looking.
Reports You Can Trust When Someone Asks How The Shop Is Doing
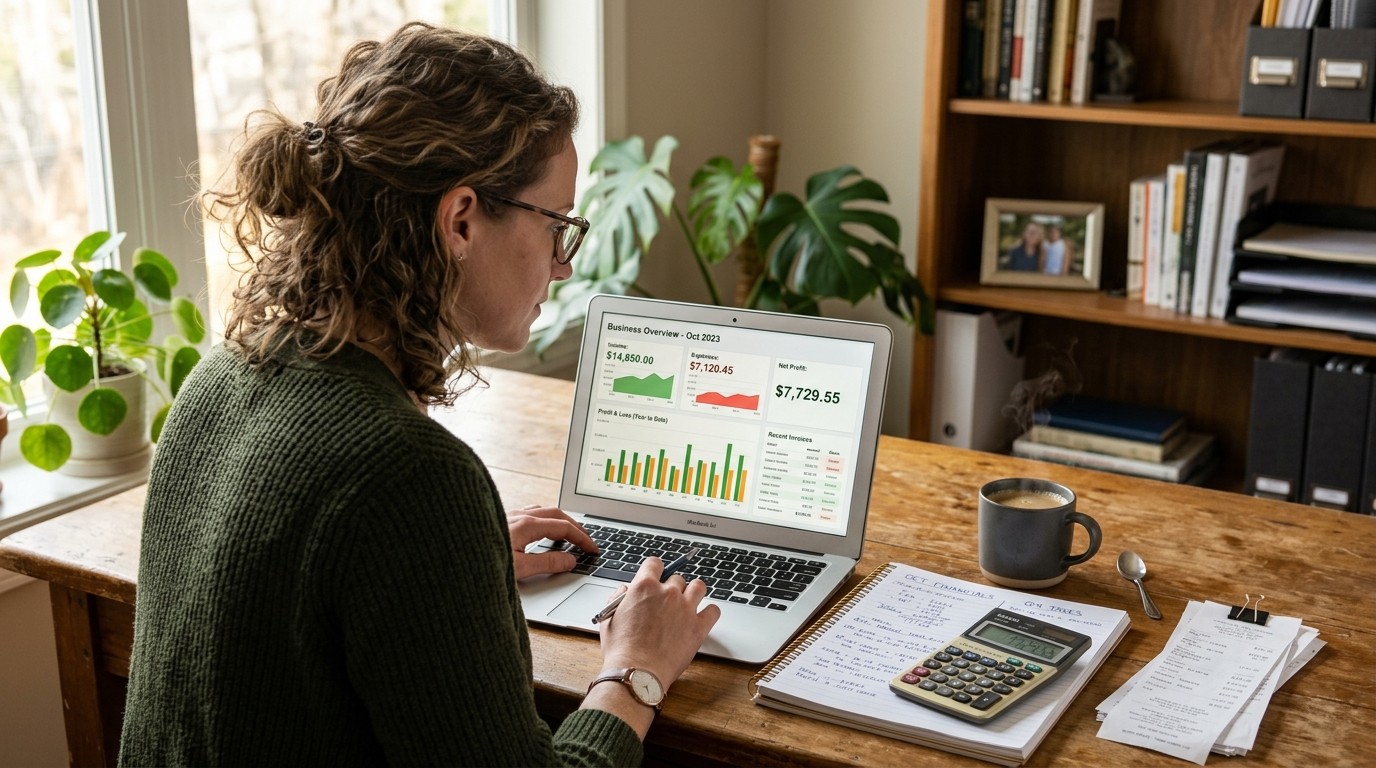
A bank balance is not a profit figure. It is a snapshot of cash after timing accidents. You need at least a profit and loss view, a simple balance sheet if assets and debts matter, and a quick activity report you can generate without building a pivot table. That last one is underrated. Sometimes you just want last week’s sales versus last week’s software spend. You should not need a weekend to get it.
Look at how reports are labeled. Vague charts that say “activity” without dates or categories are decoration. Useful reports let you filter by period, customer, or expense type. If tax time is coming, you want categories that map to the way you file, not cute names you invented at midnight.
- Generate a profit and loss for the last 30 days and the last 90 days.
- Check whether unpaid invoices inflate or hide the picture.
- Scan expenses for one category that is growing faster than sales.
- Export or print something you could hand to an advisor without apology.
Perhaps the most interesting part of free reporting is what it leaves out. Inventory valuation, job costing, budget versus actual, multi-user notes. You may not need those on day one. You will care the minute a project runs over and you cannot see why. That is a scalability issue, which we will get to. For now, confirm the basics exist and are not locked behind a “sample data only” wall.
Automation That Saves Time Instead Of Creating New Chores
Owners say they want digital tools for speed. Fair. Then they photograph every receipt with a ritual that takes longer than dropping the slip in a folder. Automation should cut repetition: bank rules, receipt snaps with monthly caps you can live with, mileage for a handful of trips, recurring invoice templates if your work is retainer-based.
Caps are not evil. They are a product decision. Two receipts and five trips a month might be plenty for a consultant who rarely drives and bills mostly from a laptop. It is useless for a tradesperson with a glove box full of supplier tickets. Match the cap to your week, not to a brochure.
Automation only helps if you trust the first pass and still glance at the second. Blind acceptance of categories is how “office supplies” swallows half your cost of goods.
I like tools that let you correct a category once and remember the vendor. That single memory feature is worth more than a dozen unused dashboards. If the free edition forces you to recategorize the same coffee shop every Monday, you will quit and go back to the sheet. Nobody should have to win an argument with software before breakfast.
Ease Of Use Is Not A Soft Extra
Free software that takes a Saturday to set up is not free. Your time has a price, even if you pretend it does not. A decent onboarding flow asks what you sell, where the money lives, and what you want to see first. Five minutes is a marketing line, sure. Still, if you cannot send a test invoice the same afternoon you sign up, the product is fighting you.
Mobile and web should agree with each other. Enter a mileage trip in the parking lot and see it on the laptop when you get home. That sounds basic. It is also where a lot of lightweight apps stumble. Sync delays create duplicate entries, and duplicate entries create fake expenses. Then you spend Sunday cleaning a mess the app created on Thursday.
Help resources matter more on a free plan because you probably do not have a dedicated bookkeeper on call. Articles, a community forum, and a search box that finds the right article are not glamorous. They are how you recover when a payment sits in limbo. I would rather have plain-language help than a chatbot that apologizes in circles.
Security Is Non-Negotiable Even When The Price Is Zero
Your books contain account numbers, customer emails, and a map of how the business survives. Treat that like sensitive material, because it is. Look for encryption in transit and at rest, multi-factor sign-in, read-only bank connections where possible, and automatic backups you did not have to configure like a hobby sysadmin.
“Bank-grade” is a phrase vendors love. Translate it. You want 256-bit encryption, session timeouts, and a vendor that does not email you a password in plain text. You also want to know who can see the file if you ever invite an accountant. One-user free plans are simpler to lock down. They also become awkward the day you need a second pair of eyes.
- Turn on multi-factor authentication the same day you create the account.
- Use a unique password, not the one from your store email.
- Prefer read-only bank links over full-access connections.
- Confirm that deleting the app from a phone does not leave files sitting in a public folder.
Cloud backups beat a USB stick in a kitchen drawer. Devices fail. People spill coffee. If the only copy of last year’s invoices lives on a laptop with a cracked screen, you do not have a system. You have a hope.
Transparency About Price, Caps, And The Credit Card Question
Some “free” products are trials with a calendar. Others are lasting free tiers with hard walls. Those are different animals. A trial that converts unless you cancel is a sales funnel. A forever-free plan with one user, one bank, and a monthly invoice ceiling is a product. Both can be honest. Only one stays free if you forget about it.
Read the limits in one sitting. Users. Bank connections. Invoices. Estimates. Receipt scans. Reports. Contractor forms. Payment processing. If any of those are fuzzy, assume the fuzzy item is the one you will need next month. I have a bias here. I would rather see a blunt list of caps than a cheerful page that says “everything you need” and hides the rest in a help article.
No credit card required is a good signal for a true free tier. It is not a moral victory. It just means you can test without a calendar reminder from a billing team. Still check the payment processor terms if you accept cards. Movement of money is regulated, and fees apply even when the bookkeeping seat is complimentary.
Quick honesty check before you click sign up:
  Is free forever or free for 30 days?
  Do I need to enter a card?
  How many invoices can I send?
  How many banks can I link?
  Who else can log in?
  What happens to my data if I upgrade later?
Scalability, Or What Happens When The Side Hustle Stops Being A Side Hustle
This is the part people skip because growth feels hypothetical. Then a second contractor appears. Inventory shows up. A bookkeeper wants access. Suddenly the free plan is a hallway that ends at a locked door. If the vendor also sells a fuller product in the same family, upgrading can carry your history forward. If the free tool is a dead-end island, you get to rebuild charts of accounts from scratch. That rebuild is miserable. I have done versions of it. Nobody frames those evenings as a fond memory.
Think about the next layer you might need: extra users, more banks, budgets, inventory counts, project profitability, payroll hooks, accountant access. You do not have to buy those today. You should know they exist on a path you can take without exporting twelve CSVs and praying the dates survive.
There is a quiet advantage to staying inside one ecosystem when the time comes. Categories stay familiar. Invoice numbering does not reset into chaos. Customers do not receive a strangely formatted bill from a brand-new tool you learned on a Tuesday. Familiarity is underrated in finance software. Panic is expensive.
A Practical Way To Compare Options Without Getting Lost
Write down your real month, not your ideal month. How many sales. How many bills. How many miles. How many people touch the books. Then score each free product against that list. Pretty interface gets a point. Matching your volume gets five.
- List last month’s invoices, expenses, and bank accounts.
- Mark which of those the free plan can handle without workarounds.
- Send one test invoice to yourself and pay it with a small amount if fees allow.
- Run a profit and loss and see if the numbers feel true.
- Read the upgrade page once, while you are calm, not after you hit a wall.
If two products tie on features, pick the one you will actually open on a tired Thursday. That sounds unserious. It is the most serious filter I know. Unused software produces the same result as no software: surprise tax packets and a stomach drop when a client asks for a statement.
Common Traps That Make Free Plans Feel Broken
Mixing personal and business spend in the only connected account is the classic mess. The software will dutifully import both. You will spend evenings marking burritos as personal. Open a dedicated account if you can. Even a basic one. Your future self will send a thank-you note.
Another trap is treating payment fees as optional trivia. They are a cost of goods for service businesses that bill by card. Build them into pricing or accept slimmer margins. Pretending a two-point-nine-nine percent fee is a rounding error is how profitable months turn average.
A third trap is ignoring contractors until January. If the free plan supports one 1099-style record, use it when you hire, not when the form is due. Waiting creates missing addresses and awkward texts in the first week of the year.
The software cannot be more organized than the habits you bring to it. A free plan with weekly reviews beats a premium suite you never open.
How Free Tools Change Tax Season Without Turning You Into An Accountant
Organized categories will not file for you. They will stop you from reconstructing a year from memory. That is the real gift. When income is tagged and expenses are not stuffed in a “misc” bucket the size of a garage, an advisor can work faster. Faster usually means cheaper, or at least less painful.
Keep a short monthly ritual. Fifteen minutes. Confirm new transactions. Match payments to invoices. Glance at profit. Note one number that looks odd. That is it. People who wait until December are not lazy. They are busy. The ritual is how busy people stay current without becoming bookkeepers.
If you sell across platforms or collect deposits, watch timing. Cash received is not always revenue earned. Free plans vary in how well they handle that nuance. When in doubt, add a note on the transaction. Notes survive upgrades. Memories do not.
Who A Free Plan Is Actually For
Solo operators with a simple service, a single bank, and a modest invoice volume are the sweet spot. Consultants, tutors, designers, small online sellers who are not yet wrestling inventory, local trades with a short customer list. If that is you, a no-cost platform can replace the spreadsheet and give you a path upward.
It is a weaker fit if you already have staff sharing books, several payment processors, stock on shelves, or a bookkeeper who needs simultaneous access. You can force a free tool into that shape. You will spend more energy on workarounds than on the work that pays.
I do not think every new business must pay for software on day one. I do think every new business should pick a system that can survive day ninety. That is a different standard than “it costs nothing this afternoon.”
A Realistic Bottom Line
Free accounting software can cover the essentials: track income and expenses, send a limited set of invoices, take payments with fees attached, produce basic reports, store a few receipts, and keep one person organized. That is not a small thing. For many owners it is the difference between flying blind and seeing the week clearly.
The limits are the product. Users, banks, invoices, scans, trips. Read them. Match them to your volume. Prefer a vendor that will let you graduate without starting over. Demand encryption and a second factor. Ignore the fantasy that a dashboard alone makes a company healthy. The habit of looking at the numbers still belongs to you.
If you are staring at a colorful spreadsheet right now and feeling a little proud, good. It got you here. When the colors stop helping and the questions get sharper — what did we earn, what is late, what can we cut — that is the cue. Pick a free plan that answers those questions this month and still has a hallway to walk down when the business gets louder. That, more than any feature grid, is what to look for.