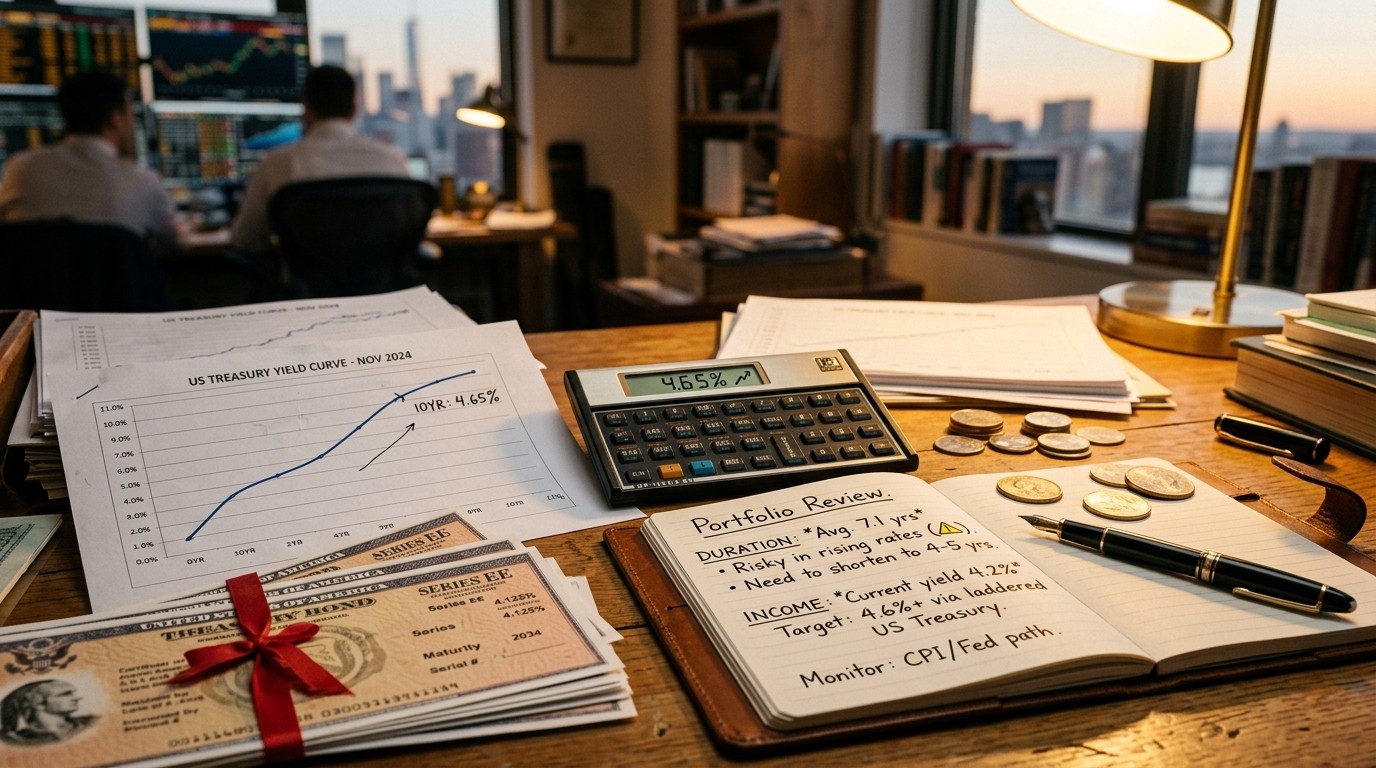

Have you noticed how every conversation about cash suddenly sounds different? A year ago, people chasing income were scraping for crumbs. Now the 10-year is sitting at levels that would have felt like a fantasy in the last cycle, and the 30-year has punched into territory last associated with a very different market. That shift is not just noise. For anyone who lives off coupons, dividends from bond funds, or a simple need for reliable cash flow, the starting yield finally matters again.
Why Higher Yields Change The Income Playbook
Bond prices and yields move in opposite directions. When yields climb, existing bonds lose market value. That part is old news. What is new is the quality of the income you can lock in today. I have found that investors often obsess over yesterday’s paper losses and miss the more useful question: what does the next dollar of capital actually earn from here?
The move higher has several engines running at once. Traders are wrestling with the size of government borrowing, oil that refuses to stay quiet, inflation that is sticky rather than gone, and an economy that still looks sturdy. The policy rate went up another quarter point recently, and markets are treating another hike as more likely than not. Whether that second move lands or not, the message is the same. Cash is no longer free, and duration is no longer a free lunch.
If you are coming to the market for income today, you are in a much better position than you were a year ago, because your starting yield is much better.
– Fixed income portfolio manager
That line is the whole thesis in one sentence. A higher starting yield does two quiet things. First, it pays you more while you wait. Second, it builds a cushion. If rates keep grinding higher, you do not slide into negative total return as quickly. In my experience, that cushion is what separates a calm income plan from a nervous one.
The Curve Is Not Treating Every Maturity The Same
Volatility is loudest farther out. Long-dated bonds carry more duration, which is just a fancy way of saying their prices swing harder when rates twitch. If you do not want that ride, you do not have to take it. Shorter paper, roughly out to five years, keeps rate risk contained without forcing you into a pure cash product that may lag once policy eventually pauses.
Treasury bills remain the cleanest claim. They are backed by the government and they reset quickly. Fine. But if you can tolerate a little credit risk, short investment-grade corporates often pay you for that extra step. The extra yield is not a miracle. It is compensation for company risk that, right now, still looks manageable across a lot of sectors.
Think of it this way. A money market fund is a parking lot. A short corporate bond is a short commute. You still get home. You just collect a bit more for the trip. That is the trade many income investors should be studying before they stretch into 20- and 30-year paper because a headline yield looks pretty.
Floating Rate Credit When Coupons Need To Keep Up
Fixed coupons feel comforting until the market reprices overnight. That is why money has been leaving static coupons for notes that reset. Floating-rate investment-grade corporates in the one- to three-year neighborhood are doing a simple job well. The stated maturity is short. The coupon is not glued to last year’s rate. Interest-rate risk stays small. Credit risk, if you stay in higher quality names, stays contained.
I like this sleeve when an investor says, “I want yield that can walk uphill with the market, but I do not want to bet the ranch on a 30-year duration call.” You are not trying to be a hero. You are trying to keep purchasing power from leaking while policymakers finish their work.
There is a more aggressive cousin of this idea: floating-rate bank loans. Those sit below investment grade. Yields in some pockets have pushed north of 7 percent, which is the point where a lot of income seekers start saying the risk is finally priced. Maybe. Perhaps the most interesting aspect is not the headline number. It is whether you are being paid for liquidity risk, covenant quality, and what happens if growth stumbles. Compensation is not the same thing as a free pass.
- Stay in investment-grade floaters if capital preservation still sits at the top of the list.
- Use bank loans only as a satellite, not as the whole income engine.
- Watch reset frequency. A coupon that adjusts with market rates is the feature you are buying.
- Do not confuse a high current yield with a low-risk portfolio.
The Five To Seven Year Sweet Spot
Short paper solves the fear of rising rates. Intermediate paper solves the fear of being underpaid forever. Several allocators keep pointing to the five- to seven-year part of the curve as the place where income and volatility can share a table without starting a fight. These bonds are not as jumpy as the long end. They still offer a coupon that can compound in a meaningful way.
Investment-grade corporates are the usual guests in that room. Corporate balance sheets, across many sectors, still look reasonably solid. Fundamentals are not perfect. They rarely are. But they are not screaming distress either. That combination, plus a better starting yield, is why intermediate credit keeps coming up in serious conversations.
Corporate fundamentals are very strong and balance sheets are still fairly solid across most sectors.
– Asset management chief investment officer
Agency mortgage-backed securities sit in a similar conversation. You pick up spread over Treasuries without leaping into speculative credit. Prepayment behavior can be annoying. Rate volatility can still bruise prices. Even so, for a taxable income book that needs ballast and yield, the sector has earned another look.
On the short end of a barbell, some strategists still prefer Treasuries paired with higher-quality high yield rather than a messy middle. That is a taste question. I lean toward keeping the junk sleeve small and the quality bias obvious. Stretching for the last 50 basis points is how income plans get sloppy.
Build Positions In Pieces, Not In A Panic
Here is the part people skip because it is boring. Attractive yields do not require an all-in trade on a Thursday afternoon. Markets overshoot. Knee-jerk moves reverse. Strong growth and a hawkish policy path can already be inside the price. The next surprise can easily come from the other direction.
That is why incremental buying still beats a single dramatic allocation. These are not two-day trades. They are multi-year income holdings. You are trying to lock a high-quality coupon you can compound, with enough extra yield to absorb a future rate scare. If you dump the entire cash pile in one print, you own every timing error in the book.
- Decide the role of the money: spending cash, ballast, or long-horizon income.
- Match duration to that role instead of chasing the longest bond on the screen.
- Scale into credit in several tickets rather than one heroic ticket.
- Revisit the mix after each policy meeting instead of after every headline.
- Keep a Treasury sleeve so you can act if spreads widen for the right reasons.
I’ve found that investors who treat bonds like a lottery ticket end up disappointed. Investors who treat them like a paycheck tend to sleep. The difference is process, not prophecy.
How Duration Actually Shows Up In Real Life
Duration is not a classroom word. It is the speed of the bruise when yields jump. A bond with long duration can look generous on a yield screen and still wreck a quarterly statement. A short bond can look modest and still do the job you hired it to do.
Imagine two neighbors. One bought long Treasuries because the coupon looked historic. The other bought a ladder of two- to five-year investment-grade notes. If yields keep climbing, neighbor one stares at a red mark and starts questioning the whole plan. Neighbor two still cashes a coupon and can reinvest maturing pieces at the new, higher rate. Same news. Different experience.
That is why “avoid too much volatility” is not timid advice. It is arithmetic. You can always extend later if the path of rates becomes clearer. Extending first and hoping is how income portfolios become accidental total-return portfolios.
| Sleeve | Rate Sensitivity | Income Role |
| Treasury bills | Very low | Safety and optionality |
| Short investment-grade corporates | Low | Steady coupon with modest extra yield |
| Investment-grade floaters | Very low | Coupons that can reset higher |
| Five- to seven-year corporates | Moderate | Compounding income with a cushion |
| Long Treasuries and long corporates | High | Only if you explicitly want duration |
Credit Risk Is A Tool, Not A Personality Trait
Some investors treat credit like a badge. They want the extra yield because it feels like they are doing something. Others treat credit like poison. Both extremes miss the point. Credit is a tool for harvesting spread when balance sheets can support it.
Right now the case for investment-grade paper is straightforward. Issuers refinanced a lot of debt when money was cheap. Interest coverage in many sectors still looks decent. Defaults in high quality names are not the base case. That does not mean spreads cannot widen. It means you can own a measured amount of corporate risk without turning the portfolio into a distressed-debt fund.
High yield is a different animal. The extra coupon is real. So is the chance that a growth scare turns “being compensated” into “being stuck.” If you use high yield, keep the quality bias and the position size honest. A satellite can help income. A concentrated bet can hijack the plan.
What A Practical Income Mix Can Look Like
No two households need the same stack. Still, a workable sketch keeps showing up in real conversations. A core of short and intermediate high-quality bonds. A smaller sleeve of floaters so part of the book can reprice. A measured credit overlay. Cash or bills for near-term spending and dry powder. That is not clever. It is durable.
Sample income posture, not a prescription:
  30% short Treasuries and bills
  25% short investment-grade corporates
  20% five- to seven-year investment-grade credit
  15% investment-grade floating-rate notes
  10% higher-quality spread products, sized to sleep
Change the weights if your time horizon is longer or if you already have a pension that behaves like a bond. The point is the logic. You are buying a starting yield that can work even if the next year is messy. You are not making a single call on the terminal policy rate.
Inflation, Oil, And The Deficit Are Not Side Notes
Yields are not rising in a vacuum. Sticky inflation keeps real yields in the conversation. Higher oil feeds that stickiness. Heavy government issuance reminds the market that supply is not theoretical. A resilient economy tells the central bank it does not have to rush toward easy money.
Put those together and you get a market that can stay firmer for longer than a slogan about “pivots” would suggest. That environment is annoying if you own a pile of long-duration bonds bought at lower yields. It is useful if you are a fresh buyer. The same facts can be a headwind or a tailwind depending on when you showed up.
Does that mean yields only go one way from here? Of course not. A growth scare, a policy surprise, or a sudden drop in energy prices can pull the long end back down. That is exactly why scaling in still beats swinging for the fences. You want to own the coupon. You do not need to own the last tick.
Common Mistakes When Yields Look Exciting
The first mistake is treating the longest bond as the only “real” bond. Long paper is a duration instrument. Sometimes that is what you want. Often it is not. Income and duration are related. They are not identical.
The second mistake is confusing a money market rate with a plan. Cash is wonderful for optionality. It is less wonderful if you need a multi-year income stream and policy eventually eases. Short bonds and floaters sit in the gap between those two jobs.
The third mistake is all-or-nothing credit. Either people hide in Treasuries and complain about the yield, or they load the truck with speculative paper because a number starting with seven looks like freedom. There is a wide middle. Use it.
- Chasing yesterday’s peak yield without checking duration.
- Ignoring reinvestment risk because cash feels easy right now.
- Buying the whole high-yield market when only the better names fit the mandate.
- Waiting for a perfect entry that never arrives while coupons go to someone else.
Taxes, Compounding, And The Quiet Work Of Time
A higher coupon is only half the story. Where you hold the bond matters. Taxable accounts feel every coupon. Tax-advantaged accounts let compounding do more of the heavy lifting. That is not tax advice. It is a reminder that two investors can buy the same note and keep different amounts.
Compounding likes consistency more than drama. A 5 percent-plus starting yield on high-quality paper, reinvested with some discipline, does work that flashy trades rarely match. The cushion from that yield is also psychological. When the next scare hits, you are less likely to sell the income engine to soothe a statement.
I’ve sat with people who sold good bonds after a two-week drawdown and then watched the same yields look even better a month later. That pattern is expensive. A written rule about position size and time horizon beats a late-night decision almost every time.
What To Watch Next Without Getting Hypnotized
Policy meetings will keep stealing the spotlight. Fair enough. Also watch issuance calendars, energy prices, and whether inflation progress stalls. Those three can move the long end even when the policy rate sits still. Credit spreads deserve a glance too. If they blow out while Treasury yields are already high, that can be an opportunity rather than a verdict.
None of that requires you to live on a trading desk. A simple monthly review is enough for most income plans. Ask three questions. Did my duration still match my goal? Did credit quality drift? Did cash pile up because I froze? Answer those and you will already be ahead of the crowd that only reacts to the loudest yield on social media.
These are for longer-term horizons, where you can lock high-quality income that compounds and still leaves a cushion if rates rise again.
A Clearer Way To Think About The Opportunity
Rising yields hurt yesterday’s prices. They also raise tomorrow’s starting line. If you need income, that second fact should dominate the first. Stay shorter if you fear more tightening. Use floaters if you want coupons that can keep pace. Step into five- to seven-year investment-grade credit if you want a blend of yield and sanity. Add agency mortgages or selective high yield only when the extra spread is doing real work.
And please, build the position the way you would build a house. Frame by frame. Not with one weekend of adrenaline. The market has already priced a lot of strength and a lot of policy resolve. The risk is not only that yields go higher. The risk is that they whip around while you are still deciding whether you are an investor or a spectator.
Income investing got boring when rates sat on the floor. It is interesting again. That does not mean it is simple. It means the tools finally pay you for using them with a little care. Start with the yield you can actually keep. Respect duration. Let credit be a measured helper. Then give the coupon time to do what coupons are supposed to do.