

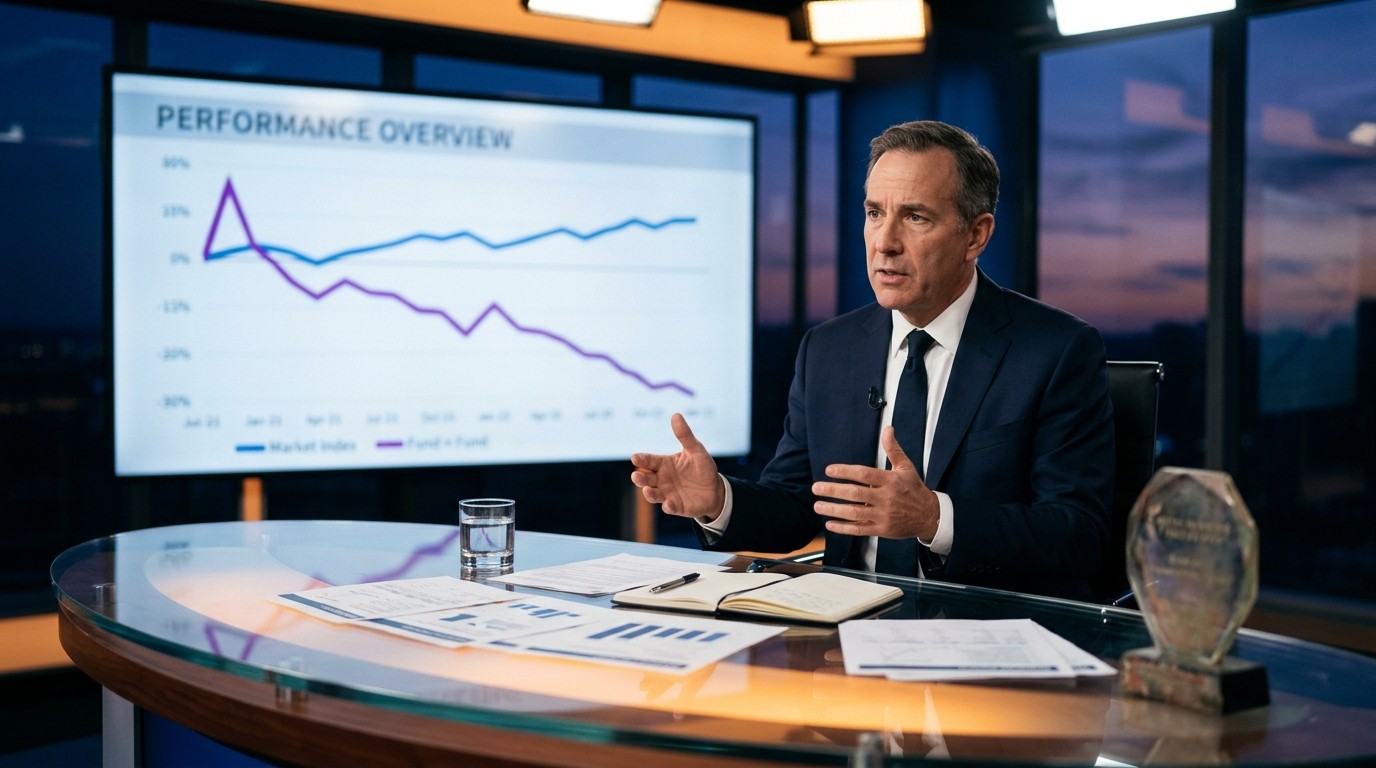

I still remember the first time a relative asked me, almost proudly, whether they should “just buy whatever she buys.” They were not talking about a private letter or a quiet research note. They meant a manager they had seen on television that morning, speaking with the calm certainty of someone who had already been right once in a very loud way. The chart on my screen told a colder story. A sharp spike, a long fade, and a benchmark that had kept climbing while the flagship fund did not. That mismatch is what stuck with me. Not the personality. The gap.
Fund underperformance is not rare. What is rare is a manager who stays famous after the numbers stop cooperating. Some of that fame is earned. A genuine early call on a disruptive company can mint a reputation that outlives the trade. The trouble starts when the reputation starts doing the work the portfolio no longer does. Investors hear vision. The account statement shows a trail. And somewhere between the two, a whole art form has grown up: the practiced habit of explaining away years of weak results without ever quite saying the results were weak.
Why A Brilliant Stretch Can Hide A Long Trail
Markets love a clean origin story. Someone was early. The crowd was late. The stock did something almost absurd, and the person who owned a lot of it looked, for a season, like they had seen around a corner the rest of us missed. I give that kind of call real credit when the numbers back it. Being early on a name that later multiplies is not luck dressed up as process. It is a result. It belongs on the record.
The record, though, does not end at the spike. Look past the highlight reel and the shape is familiar to anyone who has sat with active funds for more than one cycle. A concentrated bet works. Assets rush in. The same style stays concentrated. Then the market broadens, rates shift, or the story stocks simply stop being the only game in town. The fund that looked untouchable starts to lag the plain index it was supposed to beat. Not for a quarter. For years.
In one widely discussed innovation fund, the outperformance versus a major tech benchmark was real in the window running into the pandemic and just after. Then the line rolled over. From the start of 2019 through later years, the same flagship trailed that tech benchmark by a margin large enough to embarrass a marketing deck. Independent fund researchers later estimated that the complex had destroyed on the order of fourteen billion dollars of investor capital and placed the lead manager among the funds that had erased the most wealth over a decade. You do not need to love or hate the person to sit with that figure. Wealth destroyed is not a vibe. It is money that left accounts.
A great call is a data point. A decade is a verdict. Confusing the two is how investors stay loyal to a chart they would never buy if they saw it without the face attached.
Perhaps the most interesting part is how little the television calendar cared. Appearances continued. The oracle framing continued. Retail affection continued. I have found that media incentives and investor psychology rarely update on the same clock as a total-return line. A spike is a story. A slow bleed versus the index is a spreadsheet. Spreadsheets do not book themselves onto morning shows.
What The Chart Actually Said After The Spike
Strip the branding off and the pattern is simple. Between roughly 2020 and early 2022, the aggressive growth vehicle ran ahead of the broad tech index. That is the part people remember, because it was dramatic and because it lined up with a single name going up more than tenfold into the pandemic. Heading out of 2022, the same vehicle lagged hard. The index recovered and compounded. The fund did not keep pace. By the time you measure from the start of 2019, the relative gap is not a rounding error. It is the kind of shortfall that should force a conversation about process, fees, and whether the original edge still exists.
Relative underperformance of that size does not mean every holding was foolish. It means the package, after costs and after timing of flows, failed the job most buyers thought they were hiring. People do not put money into a high-fee active fund to match a nap. They put it there to beat a cheap benchmark they could have owned in an afternoon. When that does not happen for a long stretch, the honest sentence is short. The fund lagged. Everything after that sentence is commentary.
Commentary is where the art begins.
The Free Pass Is Not A Mystery
Charisma is a real asset. So is a relationship with producers who need a confident guest at 7:10 a.m. So is a retail following that treats a manager like a brand. None of those things are fake. They are just not returns. I have sat through enough interviews to notice the loop. A bold price target gets airtime because it is specific and a little wild. A miss gets reframed as the market being early, or rates being wrong, or the horizon being longer than the questioner thinks. The target moves. The camera stays.
There is also a selection effect. The managers who sound certain get invited back. The ones who say “I was wrong, here is what I changed” are rarer on air, even though that sentence is worth more to a client. Over time the audience learns the wrong lesson. Visibility starts to feel like validation. It is not. It is distribution.
The Excuse Catalog Investors Hear On Repeat
If you collect these interviews the way some people collect baseball cards, the phrases start to rhyme. They are not always dishonest. Sometimes the manager really does have a longer horizon than the quarter. Sometimes a factor really did punish a style. The art is in how those true fragments get stretched until they cover a hole they were never sized for.
- The horizon shift. Last year’s target becomes a five-year vision the moment it looks silly. The clock moves. The accountability does not.
- The misunderstood genius frame. Lagging is recast as the crowd being blind. Skepticism becomes proof the idea is early, not evidence it is wrong.
- The single-winner souvenir. One historic call is asked to cosign every later decision, including the ones that gave the gains back.
- The macro alibi. Rates, liquidity, or “the market” absorb the blame, even when peers in the same regime did fine.
- The innovation sermon. Disruption language fills the space where a benchmark comparison should sit. Themes are not returns.
- The fee silence. Costs rarely lead the segment. Over a decade they are not a footnote. They are a second manager you did not hire.
None of these lines are unique to one firm. I have heard versions from value managers in the 2010s, from commodity bulls after a spike, from income funds that reached for yield and then explained the drawdown as a temporary mark. The costume changes. The move is the same. Protect the story. Postpone the scoreboard.
Price Targets That Float Above The Tape
Bold targets are catnip. A number with many zeros attached to a familiar company will always travel farther than a paragraph about position sizing. In my experience, the targets that age the worst share a trait. They are not built from a range. They are built from a narrative that assumes the best path keeps compounding and that competition, capital cost, and dilution stay polite.
When the path bends, the target often survives anyway. It gets a new date. It gets a caveat about “if adoption inflects.” It gets compared with an even wilder number so the original looks moderate. Investors who anchor on the first figure they heard are still mentally marked to a destination the stock left years ago. That anchor is expensive. It keeps people from asking a plainer question: what has this fund done versus a boring index since I could have bought either?
Wild targets are not a crime. Publishing them without a public autopsy when they fail is a choice. The choice teaches the audience that precision is a marketing format, not a forecast they should underwrite.
Flows Arrive Late And Leave Scarred
Here is the part that still bothers me more than the personality. The best returns in a hot fund often belong to early holders and to the manager’s own brand. The bulk of outside money tends to arrive after the spike is already on television. Those dollars buy the story at a rich moment, then sit through the giveback. Dollar-weighted returns, the ones that reflect when people actually invested, are frequently worse than the time-weighted line the factsheet prefers.
That is how a fund can be both a career-making trade for someone and a capital-destroying product for the crowd that followed. Both can be true. The fourteen-billion-style estimates that researchers publish are usually trying to capture that second truth. They are not a vibe check. They are an attempt to count what left the pockets of people who arrived because the lights were on.
Time-weighted glory and dollar-weighted pain can live in the same fund. If you only quote the first, you are telling a story about the manager. If you quote the second, you are telling a story about the clients.
A habit worth keeping when you read any hot-fund profile
Concentration Is A Feature Until It Is The Wound
High-conviction portfolios are easy to admire in a bull run. A few names do the lifting. The manager looks decisive. The problem is mathematical, not moral. When a fund is built so that a handful of positions dominate the outcome, the manager has not diversified away the chance of being spectacularly wrong. They have chosen it. That choice can be rational if the research edge is real and the client signed up for the ride. It stops being a talking point once the same concentration explains a multi-year gap versus the index.
I like managers who can name their best idea. I get uneasy when the best idea is also the second, third, and the reason the fund cannot keep up when that idea cools. Innovation is not a synonym for a portfolio. A theme can be correct in the economy and still be a poor way to own the economy, especially if you paid active fees to hold a cluster of correlated stories.
| What gets praised | What the account feels | Question worth asking |
| A famous early winner | Later buyers missed the spike | When did most assets arrive? |
| Bold long-range targets | Anchors that never reset | What happened to last year’s number? |
| Media fluency | Attention mistaken for edge | Does the benchmark agree? |
| High conviction | Correlated drawdowns | How many bets are really one bet? |
| “Just be patient” | Years of relative lag | Patient compared with what alternative? |
That table is not a verdict on any single person. It is a filter. If a pitch only fills the left column, you are being sold a trailer. The middle column is the film.
Media Incentives And The Oracle Costume
Financial television is a product. It needs guests who can speak in complete sentences, hold a point of view, and not melt when a chart goes red. Those are useful skills. They are not the same skill as compounding capital above a benchmark after fees. The costume of oracle sticks because it is convenient for everyone in the room except the viewer who might allocate savings based on the segment.
Producers are not running a due-diligence shop. A guest who was spectacularly right once remains bookable after being ordinary, or worse, for a long time. Controversy helps. A wild target helps. A calm voice explaining why the market is wrong helps. What rarely helps the booking is a flat sentence like “we have trailed the index since this date, and here is the attribution.” That sentence is a gift to an investor and a dead end for a segment producer. So it stays rare.
Retail audiences then do something human. They remember the face more than the footnote. Repeated exposure starts to feel like endorsement. It is closer to habit. I do not think most viewers are foolish for this. I think the format is built to create that feeling, and the format is very good at its job.
How Patience Gets Weaponized
Patience is a real investing virtue. Compounding needs time. Mean reversion needs time. A research process that is early by design needs time. The weaponized version is different. It asks you to ignore a completed stretch that was already long enough to test the thesis, and to treat any request for a score as short-term thinking.
Five years is not a tweet. A full cycle through a boom, a break, and a recovery is not impatience. If a fund had its heroic window, then lagged through the recovery that lifted the very sector it claims to own, “give it time” starts to mean “do not look.” Looking is the job. You can still decide the process is intact. You cannot decide that without the look.
A useful test I keep coming back to: would I describe this lag as patience if a manager I did not like posted it? If the answer changes with the logo, the analysis is not about the fund. It is about the fan club.
Process Talk Versus Outcome Math
Good managers talk about process because outcomes are noisy. Bad stretches happen to sound processes. That defense is fair for a year or two, sometimes longer if the style is out of favor for a documented reason. It stops being fair when the outcome gap is large, persistent, and poorly explained by the factor the manager claims to own.
Ask for the simple stack. What did the fund return. What did the stated benchmark return. What did a cheaper twin of the same theme return. What did fees take. What did timing of inflows do to the experience of the average dollar. If those answers live only in a footnote while the interview lives in adjectives, you are not in a research conversation. You are in brand maintenance.
A plain scoreboard, no poetry:
  Fund result
  minus benchmark
  minus fee drag
  minus the cost of arriving late
  = the experience most clients actually had
I have found that people who can say that stack out loud are usually fine to keep listening to, even when the number is ugly. People who change the subject toward a distant price target are asking you to fund the sequel before admitting how the last film did.
The Benchmark Is Not The Enemy
Active managers sometimes talk about indexes as if they were a cheap trick. They are a trick only if you pretend they do not exist. A broad tech index or a total market fund is the opportunity cost of the active bet. It is the thing the client could have held without a story, a guest spot, or a bold target. Beating it is the assignment. Trailing it is the news.
Style caveats belong in the conversation. A hyper-growth fund should not be graded like a dividend fund. Fine. Grade it against the growth and innovation exposure the buyer thought they were getting, and against the passive tools that deliver a cleaner version of that exposure. If the active version trails both the broad tech benchmark and the obvious passive cousin for years, the caveat has expired. The result remains.
One more annoyance. Relative gaps get quoted in ways that confuse people. A fund can be up and still fail. Up twenty when the alternative was up eighty is not a win with a sad face. It is a loss of what you came for. Language that celebrates absolute gains while skipping the relative hole is a soft form of the same art.
What Independent Researchers Tend To Notice First
Shops that rank funds on investor outcomes, not on narrative heat, tend to look at wealth created or destroyed, not at how quotable the manager is. Their lists are awkward because they include names the culture still treats as winners. That awkwardness is useful. It separates fame from client results.
When a research group estimates multi-billion wealth destruction and drops a manager onto a worst-of decade list, the correct response is not a shrug and not a pile-on. It is a demand for the worksheet. How were flows treated. Which share classes. Which period. If the worksheet holds, the marketing voice has a problem no interview can solve. Client capital left. The brand stayed.
I do not need every critic to be gentle. I need the number to be checkable. Once it is checkable, personality is a sideshow. You can respect a person’s early call and still decline to hire the later product. Those are not contradictory positions. They are what adult allocation looks like.
Retail Loyalty Is Not The Same As Due Diligence
There is a fandom layer in modern markets that older brokerage culture did not have in the same way. People clip interviews. They repeat targets. They defend a manager in comment sections the way they defend a team. Some of that is harmless community. Some of it is how underperformance gets social cover. If your peers treat doubt as disloyalty, you will hesitate to run the comparison that would have saved you a fee cycle.
Loyalty to a person is allowed. Loyalty to a person with your retirement money is a different contract. The contract should be cancelable when the evidence shifts. Staying is fine if you have rerun the evidence. Staying because the last interview felt reassuring is how the art succeeds.
- Write down the date you bought and the benchmark you could have bought instead.
- Pull both total returns, with dividends, through last month. No slogans.
- Subtract the fee difference. Do it in dollars, not in basis-point poetry.
- Ask whether the original thesis is the thesis you still hold, or a souvenir.
- Decide. Holding after that is a choice. Holding before that is a habit.
That sequence is boring on purpose. Boring is the opposite of the oracle segment. Boring is also where most of the money is kept or lost.
A Cleaner Way To Hear A Star Manager
You can still watch. I do. Charisma is not a sin, and a person who was early on a historic winner has earned a hearing. The hearing just needs rules, or the art walks right past you.
Rule one: separate the historic call from the current book. Credit the first. Score the second. Rule two: every new target has to sit next to the old target and the actual price path. No orphan numbers. Rule three: if the fund has trailed its honest benchmark since a date you can remember, that fact leads the conversation, not the theme. Rule four: flows matter. A strategy that only worked for the early dollar is a different product from the one being sold today. Rule five: fees are part of the result, not a technicality for the prospectus.
Follow those and the interview gets shorter in your head, which is the point. You are not there to be entertained, even if the segment is built that way. You are there to decide whether this person still has an edge you cannot replicate more cheaply.
When Underperformance Is Just Style, And When It Is Not
Not every lag is a scandal. A deep-value fund in a growth mania will look broken right up until it does not. A quality compounder will look sleepy in a meme year. Style cycles are real, and firing a sound process at the bottom of its cycle is a classic own goal. The distinction lives in the explanation and in the peers.
If every fund with a similar mandate lagged together, you are probably looking at a factor winter. If one famous fund lagged its own cousins by a wide margin, you are looking at implementation. Security selection, sizing, timing, costs, or all four. “The market does not get innovation” is not a peer comparison. A peer comparison is a list of other aggressive growth vehicles and what they did in the same months. If that list is kinder than the flagship, the macro alibi is thin.
I have watched investors forgive a unique gap because the story felt unique. Unique stories are cheap. Unique gaps versus peers are expensive. Spend your skepticism there.
The Personal Brand Is An Asset, Not A Return
Credit where it belongs. Building a recognizable franchise, speaking clearly, and turning a correct early bet into a business is skill. It is commercial skill. It can make the manager wealthy even when later clients are not. Those two outcomes diverge more often than the branding admits. A firm can grow assets on reputation while the reputation’s original evidence ages out.
There is nothing shady about a person doing well from a business they built. The shady part, when it appears, is the implication that the client is sharing in that success simply by being in the room. Sometimes they are. Sometimes they are the raw material. The chart after the spike is how you tell the difference. If the purple line, or whatever color the factsheet uses, cannot keep up with the plain index once the heroic window closes, the brand and the buyer have split.
I do not think that split requires a villain. It requires a correction in how we listen. Admiration for the business is allowed. Hiring the business with savings is optional, and the option should expire when the relative record says so.
Questions Worth Asking Before The Next Segment
Before the next confident interview pulls you in, a short list beats a long feeling. You can run it in ten minutes. Most people will not, which is why the art still works.
- What is the fund’s total return versus its stated benchmark since the peak of the story, not since inception cherry-picked around a win?
- What did a low-cost fund in the same neighborhood do over that stretch?
- When did assets peak relative to performance? Who bought the top of the narrative?
- Which old price targets were retired, and which were quietly given new birthdays?
- Is the portfolio one theme wearing several tickers?
- If this manager had no television presence, would the factsheet still earn the allocation?
If those answers are strong, ignore the cynics, including me. Edge shows up in the answers. If the answers are fog, the segment is entertainment. Entertainment is fine on a weekend. It is a rough way to pick a custodian for a decade of savings.
A Note On Being Early And Being Finished
Being early is glamorous because it photographs well. Being finished is not discussed, because “finished” sounds like an insult. Sometimes a great call is complete. The mispricing closed. The tenfold move happened. The job of that insight ended. Holding the aura of the insight after the mispricing is gone is how investors turn a closed trade into an open religion.
There is a generous reading and a strict one. The generous reading says a manager who saw one corner may see the next. The strict reading says each new book has to earn its own evidence. I lean strict with other people’s money and a little more generous with a tracking position I can afford to be wrong about. That is not cynicism. It is sizing. The art of explaining away underperformance depends on you sizing the story like the evidence, and the evidence like the story. Do not.
You can clap for the spike. You should. Then turn the page. The pages after 2022, in that well-known case, are the ones that separate fans from owners. Fans keep the clip. Owners keep the statement. Only one of those documents has to fund a life.
What I Would Want Said Out Loud
If I could pin one paragraph to the studio wall, it would be this. We were right on a major winner. That winner drove a period of outperformance you can see on the chart. Since that window, we have lagged the benchmark a client could have owned instead. Here is the gap. Here is what fees took. Here is what we changed, or here is why we refuse to change. The next target is a target, not a promise, and the last target missed by this much.
That paragraph would empty some chairs. It would also raise the quality of every chair that stayed. Investors do not need managers to be dull. They need them to be countable. The art thrives in the uncountable zone, where vision words outrun the line on the screen. Step out of that zone and the decision gets almost rudely simple. Either the edge is still there, or you are paying for a memory.
Memories can be worth something. They are just a strange thing to expense at an active-management fee, year after year, while a plain index does the quieter work of compounding. I would rather be slightly bored and roughly right than brilliantly narrated and durably behind. The chart, in the end, is ruder than any critic. It does not care who was good on television. It only cares what remained.



